


How Investors Are Reacting To Strategic Education (STRA) Weak Enrollment Trends
- Strategic Education has reported two years of disappointing domestic student enrollment trends, alongside only 3% annual earnings per share growth over five years and flat free cash flow margin expectations.
- The combination of soft student demand and stagnant profitability points to pressure on the core education model rather than just short term volatility.
- We will now examine how Strategic Education's investment narrative could be affected by weak domestic enrollment trends and muted earnings progress.
Pressure test your thesis on Strategic Education by comparing it with a curated 27 high quality undervalued stocks that pairs restrained earnings profiles with stronger cash generation and balance sheets.
Strategic Education Investment Narrative Recap
To own Strategic Education today, you need to believe the group can stabilize domestic enrollment while keeping its multi segment model earning its cost of capital. Weak U.S. student demand and only 3% annual EPS growth over five years keep the spotlight squarely on execution in core degree programs rather than on portfolio story telling.
The key short term swing factor is whether enrollment and pricing in U.S. Higher Education and Australia/New Zealand can hold up without eroding margins. The biggest risk is that scholarships, regulatory limits on international students, and higher operating costs in Education Technology Services all squeeze profitability at the same time.
With no fresh announcements tied directly to this enrollment update, the most relevant reference point is still the earlier commentary on Education Technology Services growth. Management has been leaning on Sophia Learning and corporate partnerships as a counterweight to softer domestic degree demand, which matters more when traditional student pipelines look fragile.
For you as a shareholder, this means the story hinges on execution in those faster growing services while containing the higher expenses already flagged in that segment. If ETS needs heavier investment to sustain momentum, the tension between near term earnings pressure and longer term product build out becomes a central part of the Strategic Education thesis.
Analysts currently frame the Strategic Education narrative around revenues reaching $1.4b and earnings of $216.0 million by 2029. This implies annual revenue growth of 3.6% and an earnings increase of $89.4 million from $126.6 million today.
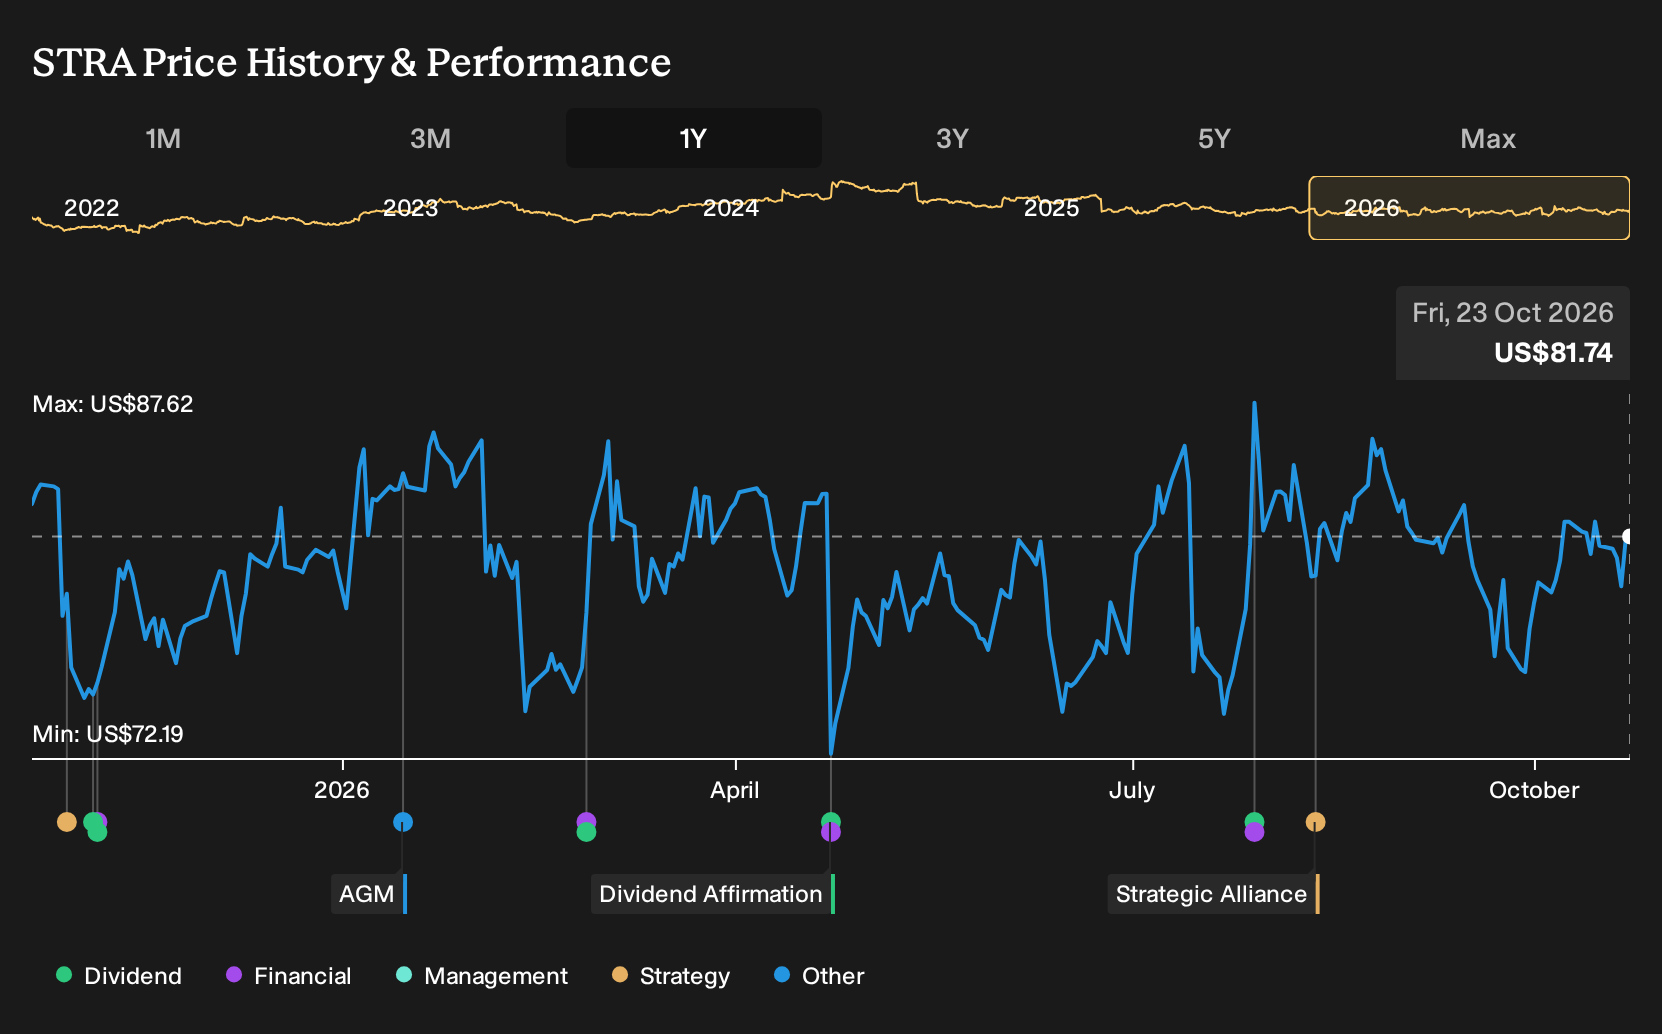
Uncover why Strategic Education's fair value indicates a 20% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
Fair value estimates for Strategic Education from four members of the Simply Wall St Community range from US$87.92 to US$230.24, reflecting a wide band of expectations. Before reacting to that spread, weigh the risk that tighter student visa settings or softer revenue per U.S. student could limit how much of that upside scenario actually materializes.
Explore 3 other Strategic Education fair value estimates, including one that suggests as much as 182% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Strategic Education research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Strategic Education. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Strategic Education's overall financial health at a glance.
Looking For More Investment Ideas Beyond Strategic Education?
If the Strategic Education story leaves you wanting a broader watchlist, it can help to line it up against other businesses with different strengths. Use the Simply Wall St Screener to compare this education group with companies that have stronger balance sheets, lower risk profiles, or higher income potential so you can see where it really fits in your portfolio.
- For investors who care most about capital protection and stability, start with a 30 resilient stocks with low risk scores that have held up well on our risk checks.
- If you want to keep the focus on quality and valuation discipline, weigh Strategic Education against a 27 high quality undervalued stocks that pair solid fundamentals with pricing that still looks reasonable.
- Income focused investors can round out their shortlist by scanning a 5 dividend fortresses that offer yields above 5% and an emphasis on resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com