


Ralph Lauren (RL) After Its AI Push And Asia Expansion Is The Bull Case Already Priced In
Ralph Lauren (RL) is back in focus after fresh coverage highlighted its push into artificial intelligence and digital tools, along with optimistic earnings estimates and faster international expansion, especially across Asia and Greater China.
Recent trading has been choppy, with Ralph Lauren’s share price down 1.19% over the last session and 2.10% over the past week. However, a 30 day share price return of 11.83% and a 1 year total shareholder return of 13.62% point to momentum that has been building rather than fading in the context of a very large 3 year total shareholder return of 258.50%.
Spot opportunities that follow a similar AI and premium consumer trend to Ralph Lauren by scanning our hand picked 38 AI small caps that connect data driven tools with brand power.After a choppy week but a powerful 3 year run, Ralph Lauren now poses a harder question for fresh capital: Does the current setup still skew the risk and reward toward buyers as valuation comes under closer scrutiny?
Most Popular Narrative: 16% Undervalued
Ralph Lauren’s most followed narrative points to a fair value of about $446.71 per share, compared with the recent close around $377.40. This puts the spotlight firmly on what could justify that valuation gap.
Accelerating international expansion, especially in Asia and Greater China where Asia revenue recently grew around the mid 20% range and China has risen to about 10% of company sales, positions Ralph Lauren to keep scaling in higher growth regions, which can support future revenue and earnings.
Strong digital adoption and a higher mix of direct to consumer activity, with direct to consumer now about 70% of revenue and global retail comps in the low to mid teens, increases exposure to higher margin channels and can support structurally stronger net margins.
See why 27 investors see Ralph Lauren as 16% undervalued.
Result: Fair Value of $446.71 (UNDERVALUED)
Still, the bullish Ralph Lauren narrative can crack if European weakness lingers or if wholesale partners like Harvey Nichols expose the business to more bad debt hits.
Find out about the key risks to this Ralph Lauren narrative.
Another View: Ralph Lauren On Earnings Multiples
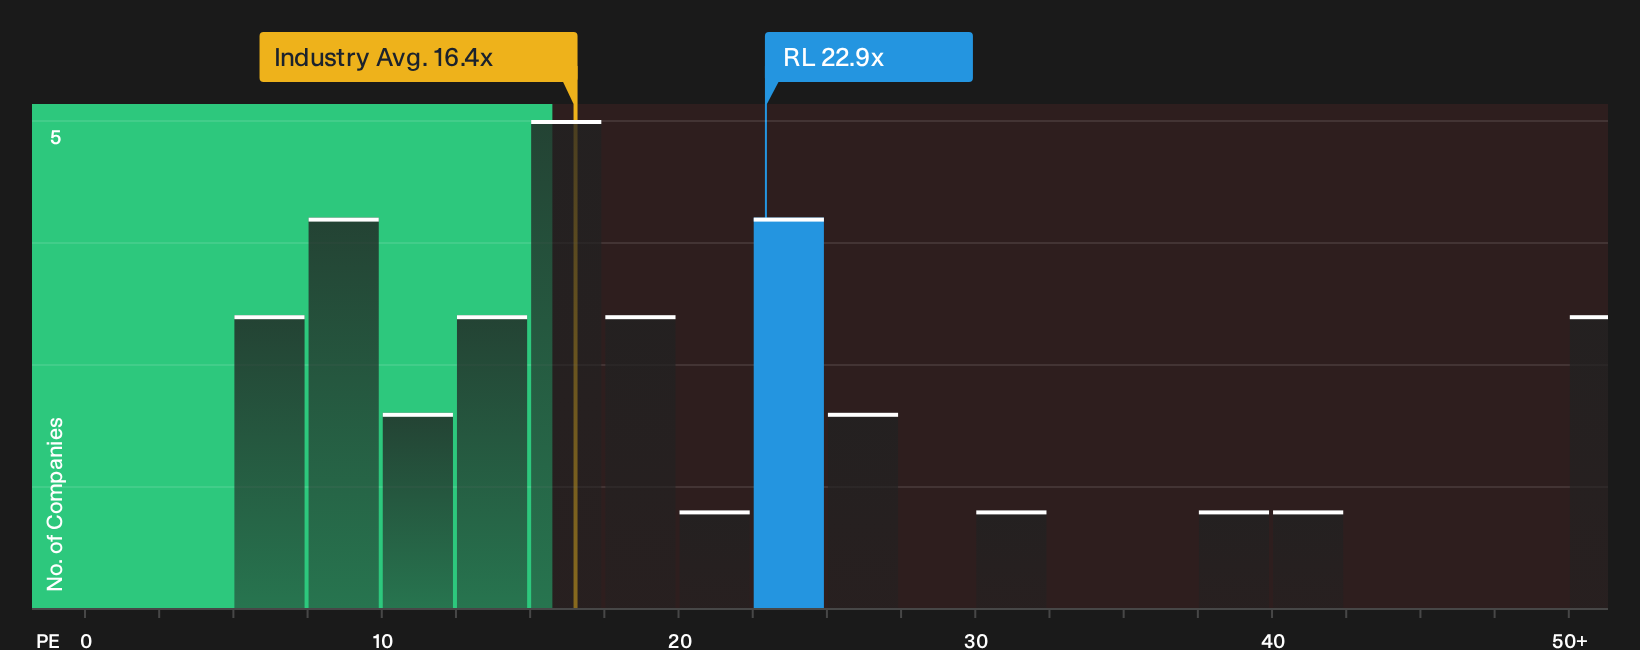
The bullish fair value of $446.71 leans on long term forecasts, yet Ralph Lauren currently trades on a P/E of 22.9x compared with 16.7x for the US Luxury group and a fair ratio of 18.5x. That richer tag can mean valuation risk if sentiment or earnings expectations cool.
To see how those numbers stack up in more detail and what they imply for upside and downside, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Ralph Lauren is split, with one camp focused on risks and another on potential rewards. Move quickly and review the same data investors are weighing today, then sharpen your own view with the 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond Ralph Lauren?
If you only stop at Ralph Lauren, you risk missing other opportunities that fit your style, risk tolerance, and return goals across different sectors and themes.
- Target potential bargains by scanning a curated 27 high quality undervalued stocks that filters for quality businesses trading below their assessed worth.
- Focus on resilience by reviewing a 30 resilient stocks with low risk scores built to spotlight companies with steadier profiles and fewer red flags.
- Hunt for future leaders by checking a 21 high quality undiscovered gems packed with under-the-radar stocks that still show strong fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com