


How Investors May Respond To Novanta (NOVT) Revenue Growth Outlook
- Novanta has reported a strong compounded annual sales growth rate over the past five years, while Wall Street analysts recently projected a further meaningful rise in revenue over the next 12 months tied to newer products and services.
- The same period of strong top-line momentum has coincided with a steady decline in return on invested capital, raising questions about how efficiently Novanta is turning incremental investment into profitable projects.
- We will now look at how Novanta's strong sales momentum and revenue outlook could reshape the existing investment narrative for the business.
Novanta Investment Narrative Recap
To own Novanta, you need to be comfortable with a story where strong sales momentum eventually lines up with more disciplined use of capital. The recent update that revenue is expected to climb further on newer products reinforces the top line, but it does not yet resolve the pressure from a falling return on invested capital. That is the key tension to keep in view.
The near term swing factor is whether margin expansion actually materializes as mix shifts toward higher value medical and automation offerings and as manufacturing changes bed in. The main risk is that integration costs, lower margin precision medicine products, and higher leverage from past deals keep ROIC and net margins from improving meaningfully.
The Riverpoint Medical acquisition still looks like the operational announcement that matters most in this context. Management used cash, a US$300 million equity placement, and credit facilities to fund the US$1.45b deal, which lifted gross debt to just over US$800 million and pro forma leverage to about 2.7x. That balance sheet move now defines the room for error on execution.
Riverpoint roughly doubled recurring medical consumables revenue to about US$300 million and pushed medical exposure toward 60% of sales. If cross selling and manufacturing consolidation run smoothly, this larger consumables base can support steadier revenue and more predictable cash generation. If integration synergies or pricing actions disappoint, the higher leverage and dilution could keep weighing on earnings quality.
What The Analyst Case Implies For Novanta
Novanta's narrative projects US$1.7b revenue and US$168.2 million earnings by 2029. This is based on 17.1% yearly revenue growth and an earnings increase of roughly US$106 million from the current US$61.8 million base.
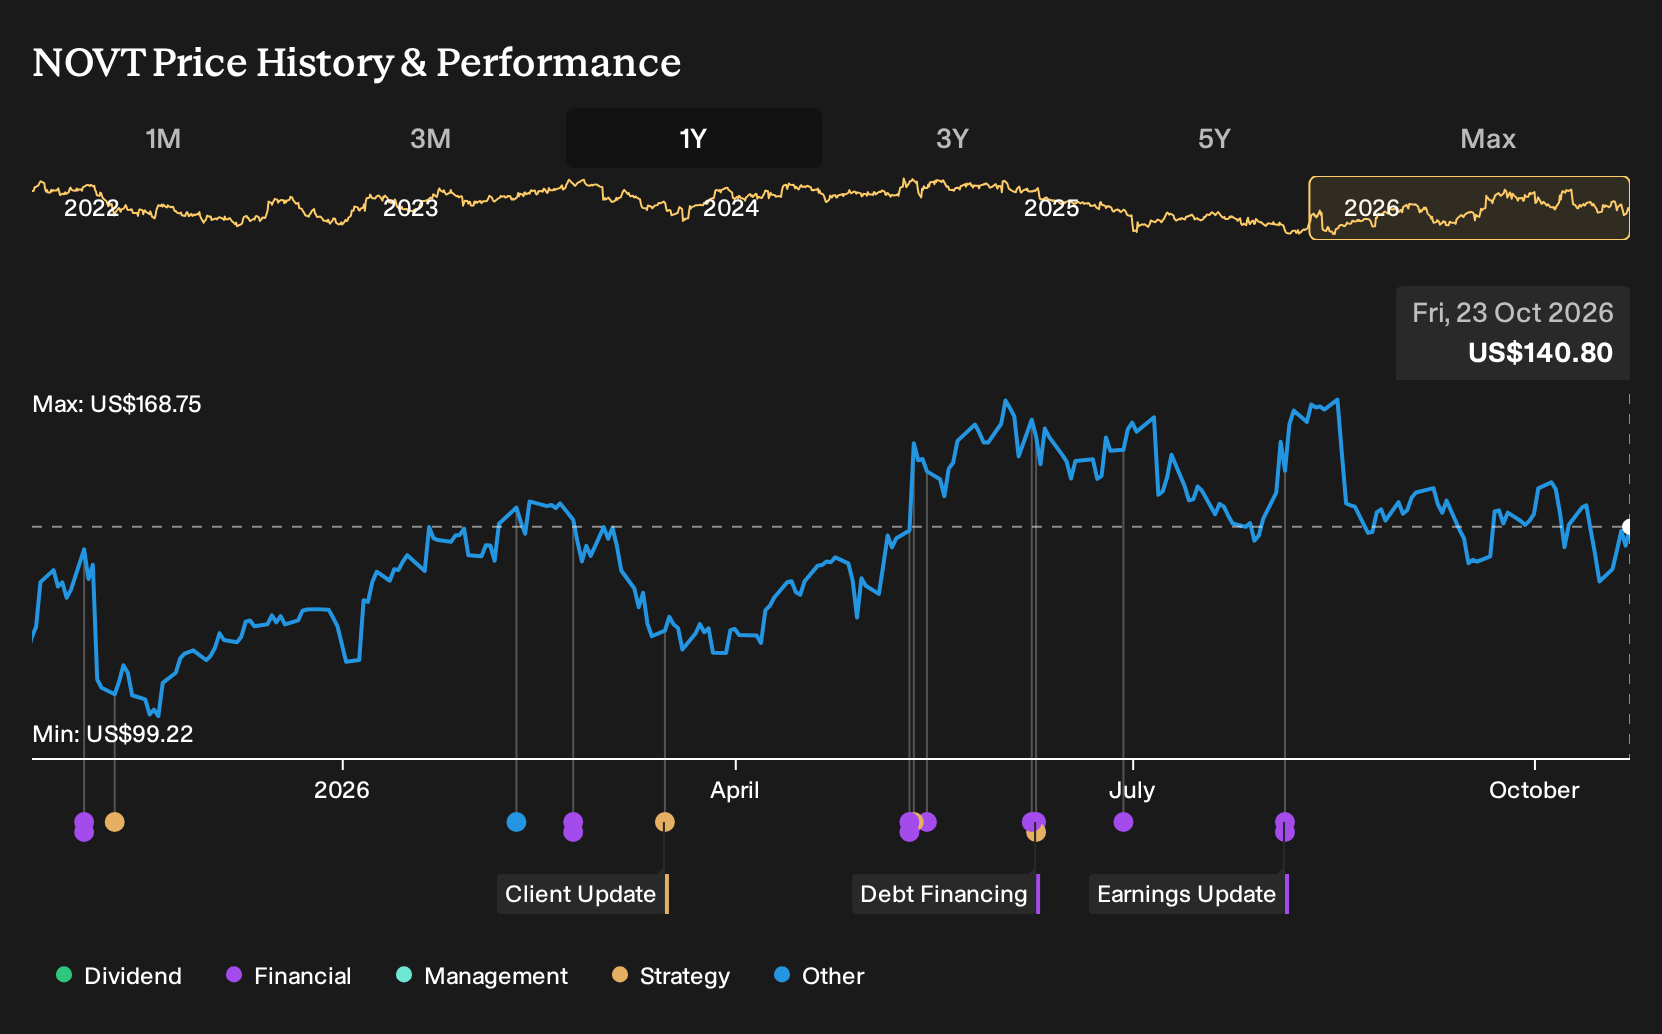
Discover why Novanta's fair value points to a 38% potential upside from its current price, an opportunity that could diminish quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$45.72 to US$194.50, which shows how far opinions on Novanta can stretch. Those views do not yet reflect the Riverpoint acquisition, higher leverage, or recent margin pressure, so you should weigh them against these risks and explore multiple viewpoints.
Explore 2 other Novanta fair value estimates, including one that suggests as much as 68% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Novanta research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Novanta. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Novanta's overall financial health at a glance.
Looking for more investment ideas beyond Novanta?
Once you have formed a view on Novanta, it can help to compare those conclusions with other opportunities that share similar qualities, whether that is valuation support, income potential, or balance sheet strength.
- If you want to focus on quality first and price second, start with a 27 high quality undervalued stocks that filters for companies where fundamentals and market pricing look out of sync.
- For readers who care most about income resilience, scan a curated 5 dividend fortresses that highlights businesses with higher yields and the financial footing to support them.
- When capital preservation matters as much as upside, you can narrow your watchlist using a 30 resilient stocks with low risk scores that tilts toward resilient balance sheets and steadier financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com