


Meta AI Spending Could Lift Rambus Stock And Other Data Center Plays
AI spending is no longer just a buzzword story; it is starting to reshape how mega-cap platforms like Meta fund, build, and own the digital plumbing behind it. When a company adds new share classes, leans into heavy infrastructure budgets, and still reports 26.1% Q3 FY2026 revenue growth, it can reshape expectations across the biggest stocks on your watchlist. This article walks through three large caps that screens suggest could be meaningful beneficiaries of that shift, and explains why the latest Meta news might matter for your portfolio decisions today.
The stocks covered below are a small sample of the idea, and the full screen surfaced 40 more large cap candidates with equally compelling AI-infrastructure narratives that do not fit into a single article. To go straight to the source and identify which tickers line up with your own thesis, analyze the AI-Driven Mega-Cap Capital Expenditure Beneficiaries screener.
Rambus (RMBS)
Overview: Rambus develops high performance memory interface chips and security focused silicon IP that help power AI and data center servers worldwide.
Operations: Rambus generates about US$756 million from semiconductors, with revenue concentrated in South Korea at US$363 million and Singapore at US$138 million.
Market Cap: US$9.3b
Rambus matters for this AI capex screen because its memory and interface technology sits directly in the data center servers that hyperscalers keep pouring money into.
"Ongoing rapid growth in AI and data center workloads is accelerating the industry's need for high speed memory interfaces and connectivity. Rambus is now tying this to record quarterly revenue of US$207.4 million with guidance for further sequential revenue and EPS growth in Q3 2026, which points to continued support for top line revenue and earnings."
What happens to that upbeat picture if one unseen pressure on future AI server demand quietly starts to cap the pricing power behind it?
If that pricing pressure is on your mind, read the full narrative for Rambus to see how Rambus could still accelerate or stall as AI capex evolves.

Giga-Byte Technology (TWSE:2376)
Overview: Giga-Byte Technology designs and sells motherboards, graphics cards, servers, and AI focused computing platforms that plug directly into cloud and data center buildouts.
Operations: Giga-Byte Technology generates roughly NT$417 billion from its Brand Business Division, with about NT$1 billion from its Other Business Group.
Market Cap: NT$234 billion
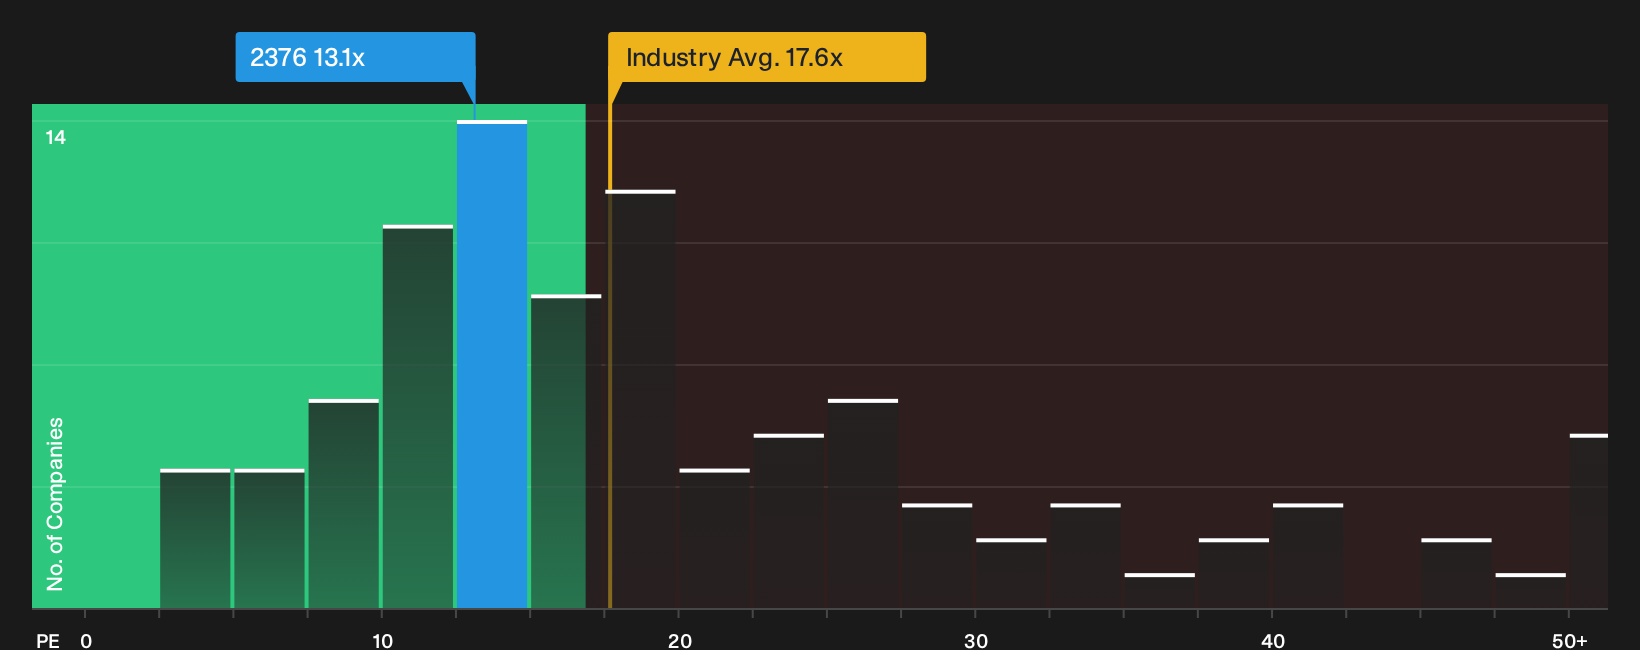
Giga-Byte Technology provides direct exposure to the hardware inside AI data centers, from GPU rich servers to cooling and rack systems. The shares trade on a P/E below both the Taiwan market and local tech peers. The growing reliance on debt funded expansion is a key factor in how much of that AI spending ultimately reaches shareholders.
That debt trend raises real questions about resilience, so review the Giga-Byte Technology financial health report to see how Giga-Byte Technology’s balance sheet pressure and AI upside intersect.
Silicon Motion Technology (SIMO)
Overview: Silicon Motion Technology designs controllers that sit inside solid state drives, helping AI ready data centers and devices access NAND storage quickly.
Operations: Silicon Motion Technology generates about US$1.31b from developing NAND flash controllers for solid state storage devices across global end markets.
Market Cap: US$6.37b
For an AI capex theme built around GPUs and hyperscale data centers, Silicon Motion Technology matters because every accelerator cluster still runs on fast, reliable flash storage.
"The rapid expansion of high performance storage demand from AI, data centers, cloud computing, and edge computing is still fueling adoption of advanced NAND controller solutions. Silicon Motion Technology now points to PCIe Gen 5 and Gen 6 client and enterprise controllers as well as MonTitan enterprise SSD controllers as key levers for future revenue and earnings growth."
The real swing factor is what happens to margins and growth expectations if one critical piece of that AI storage ramp falls short.
If that risk worries you, read the full narrative for Silicon Motion Technology to learn how Silicon Motion Technology could still turn AI storage demand into accelerating long term earnings power.

Seeking Alternatives Before Momentum Flies
Fresh ideas move first. Markets reward investors who spot quiet momentum, catch breakouts while they are under the radar for now, and react before signals drop. Act now.
- Target reliable cash generators and compare market hype against balance sheet strength with the curated list of solid balance sheet and fundamentals (25 results) before those stories get fully priced in.
- Hunt for income workhorses and stress test your yield watchlist against the hand picked 5 dividend fortresses while payout momentum still looks fresh.
- Track where AI infrastructure spend might ripple next by scanning the focused 55 AI infrastructure stocks and spotting potential beneficiaries before crowd enthusiasm flies.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com