


Fanuc (TSE:6954) Stock Drifts As Q2 Earnings Fail To Shift Doubts
Fanuc stock came into today on a weak run, down about 6% over the past week and roughly 16% over three months, then met a fresh Q2 2027 earnings print that did not hand speculators an obvious quick win. The headline number was clean enough for a mature factory automation group, with revenue of ¥242,673m and basic earnings per share of ¥66.30. However, the real story sits in the multi quarter pattern. Profit over the trailing twelve months has climbed while the share price has sagged, which puts the focus squarely on valuation rather than the latest tick in quarterly orders.
Like the earnings trend at Fanuc but uneasy about a share price that keeps drifting lower anyway? Check out 14 high quality undervalued stocks for a benchmark list of companies where profit strength and recent price pressure line up more cleanly.
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs. Q2 2026): ¥242,673m vs. ¥211,205m (up 14.9%)
- Net Income (Excl. Extra Items, Q2 2027 vs. Q2 2026): ¥61,595m vs. ¥41,976m (up 46.8%)
- Basic EPS (Q2 2027 vs. Q2 2026): ¥66.30 vs. ¥44.98 (up 47.4%)
- Trailing 12 Month Net Income (Excl. Extra Items, Q2 2027 vs. Q2 2026): ¥199,299m vs. ¥157,455m (up 26.6%)
Earnings headlines only tell part of the story, and investors who care about what they are paying for Fanuc increasingly focus on the cash moving through the business. Based on Fanuc's cash flows alone, the stock could be a clear 24% overvalued.
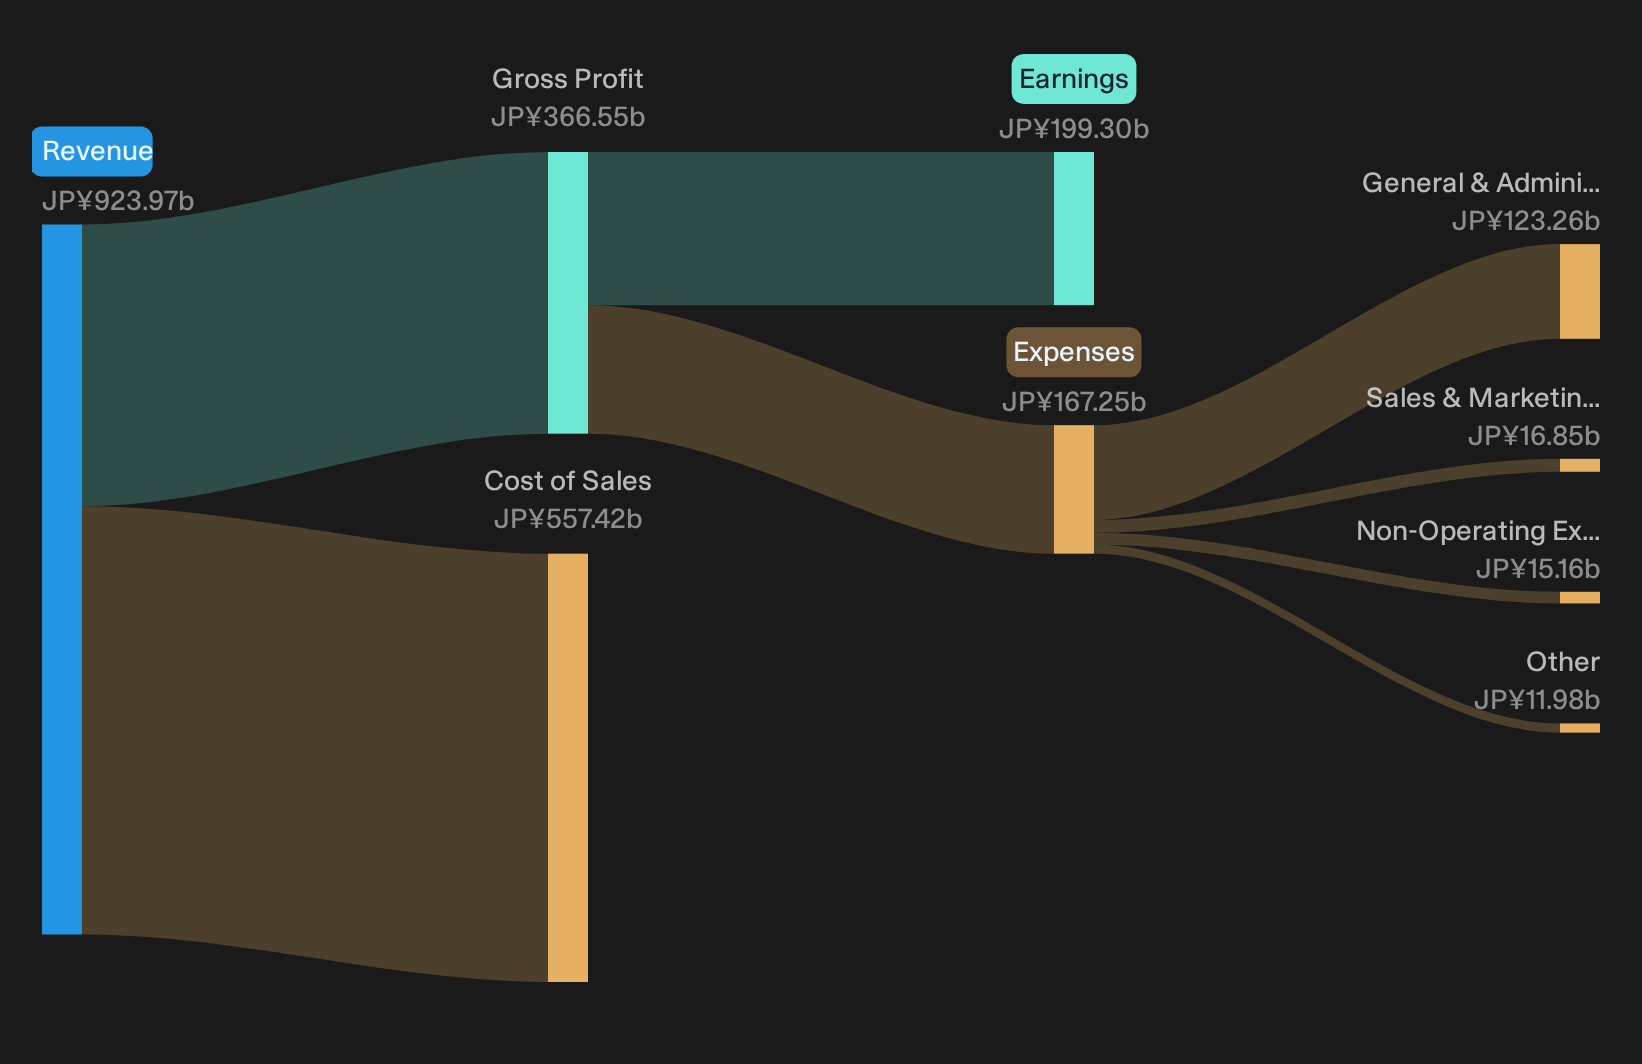
Fanuc earnings lean toward automation bull story
For anyone leaning bullish on Fanuc as an automation backbone, this quarter helps the case. Revenue is up 14.9% year on year and net income excluding extra items is up 46.8%, which points to healthy operating leverage rather than just a gentle upturn in demand. Trailing 12 month profit also moved higher versus the prior year, so the earnings trend lines back up the longer term automation and training push seen in the new U.S. academy and 5 axis initiative.
Cyclical worries still echo in Fanuc share slide
Bears focused on cyclicality will point straight to the share price. The stock is down about 7% over one month and roughly 16% over three months, even as profit over the past year has risen. That disconnect keeps alive concerns that investors still fear a capex air pocket. The recent U.S. capacity and training investment plus the 5 axis CNC initiative require ongoing customer spending, so any slowdown in autos, electronics or general machining would quickly test this stronger earnings run.
After a 3 month slide and an unstable dividend record, scan the independent risk analysis for Fanuc which shows 2 important warning signs to see whether volatility masks deeper structural issues.Hunt For The Quiet Disconnects
Fanuc illustrates how earnings strength and share price weakness can diverge for extended periods. The real opportunity sits in identifying stocks that could be undervalued before the market closes that gap.
- Company 1 - 38% below our estimate - designs and maintains complex air and water systems that facility owners upgrade when tightening energy use and contamination standards.
- Company 2 - 27% below our estimate - supplies performance ceramics and grinding tools that manufacturers switch to once precision requirements push beyond standard metalworking gear.
- Company 3 - 32% below our estimate - produces advanced photomasks that chip designers adopt when pushing into finer geometries and more demanding packaging formats.
Those are three of them. See all 14 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com