


Is Omnipod Discover Rollout Altering The Investment Case For Insulet (PODD)?
- Insulet has completed the full U.S. market release of Omnipod Discover, a web-based platform that delivers weekly insulin and glucose insight reports to Omnipod 5 users, caregivers, and healthcare professionals. This builds on limited release adoption by more than 15,000 users and 1,800 clinicians, as well as international availability across several countries.
- The early data linking Omnipod Discover use to improved time in range, paired with automated weekly engagement on users’ smartphones, indicates that Insulet is investing in data tools that aim to deepen usage of its existing Omnipod 5 customer base rather than only relying on new pump starts.
- We will now look at how Insulet's Omnipod Discover rollout and its reported time in range benefits could influence the broader investment narrative around the company.
See how Insulet's data-led approach compares with other companies that are turning real-world outcomes into an edge using our hand-picked 34 healthcare AI stocks.
Insulet Investment Narrative Recap
To own Insulet, you need to believe the Omnipod ecosystem can keep expanding while the firm tightens execution around retention, especially in type 2 diabetes. The Omnipod Discover launch fits that story. It aims to keep current users more engaged, which matters when a large part of value comes from recurring pod use, not just new system starts.
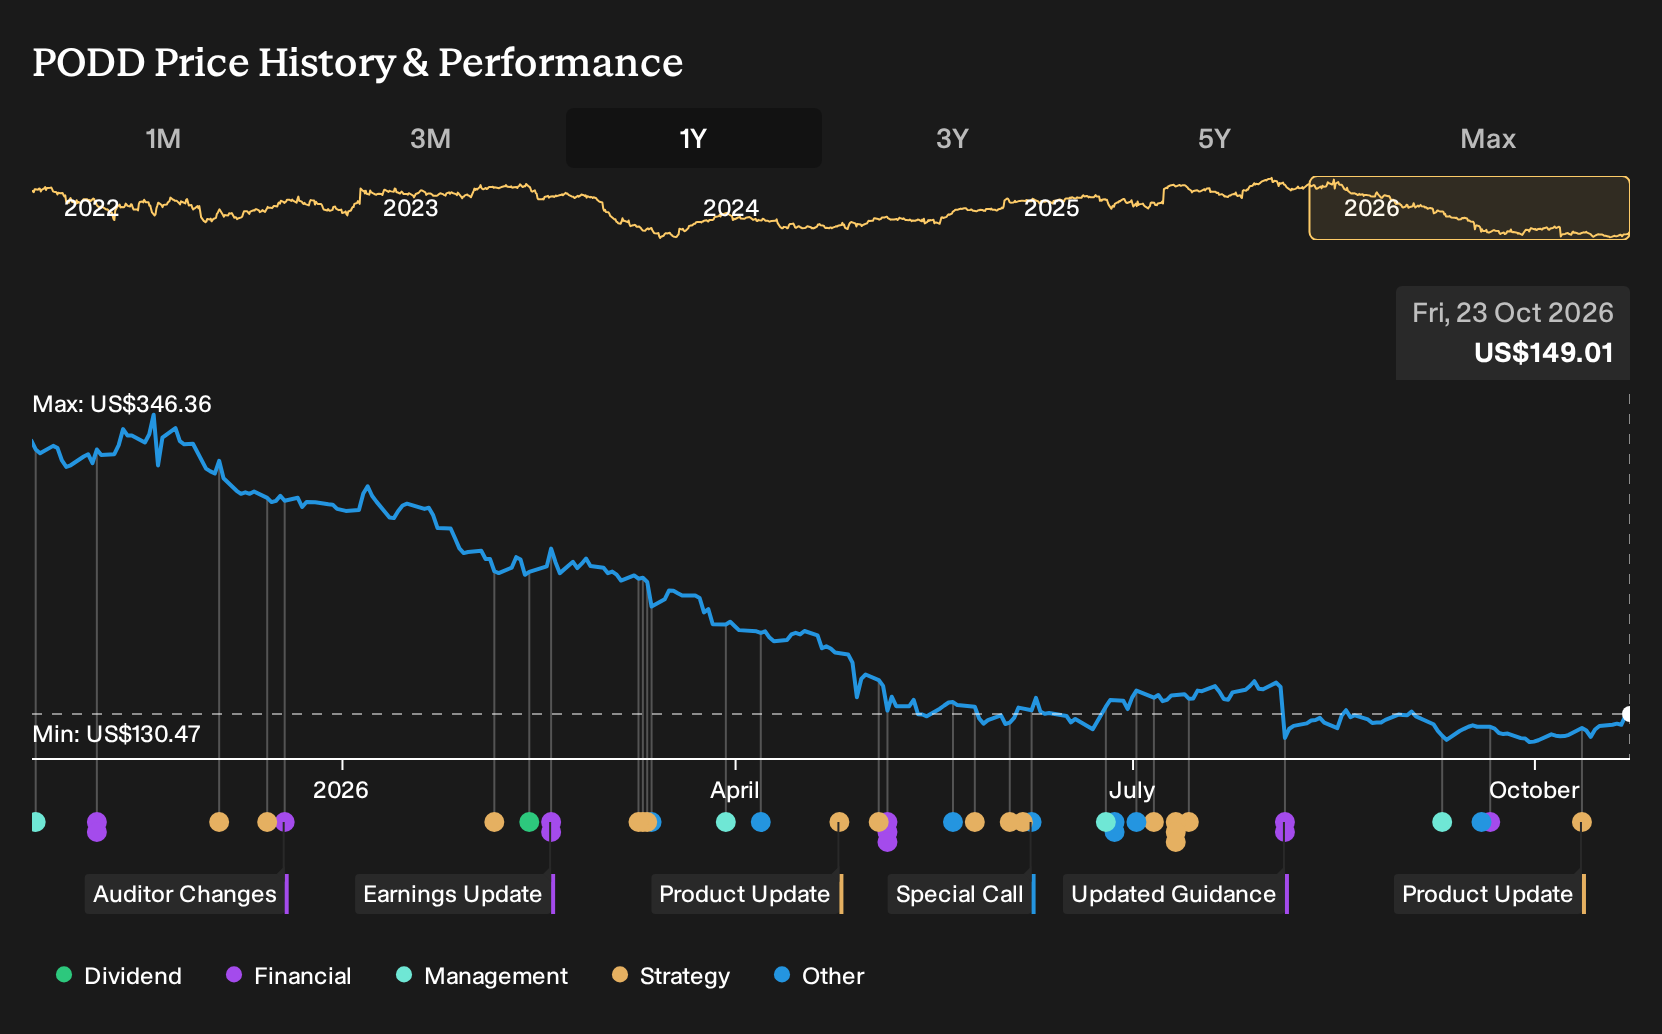
In the near term, the key swing factor is whether early utilization and churn in type 2 users improve after the guidance reset. The biggest risk is that softer retention, pricing pressure and recall related reputational issues linger. Omnipod Discover helps address engagement, but on its own the news does not radically change that risk profile.
Among recent developments, the Omnipod 6 pivotal data and fully closed loop type 2 system in trials line up most closely with the Discover rollout. Both push the story toward tighter automation and easier self management, which can make the whole suite more compelling for clinicians and patients who are already in the Omnipod funnel.
For catalysts, the important angle is how these future systems might work with tools like Omnipod Discover. If users transition to Omnipod 6 or a closed loop type 2 product with stronger time in range and fewer manual boluses, then clean, shared data reporting could help providers fine tune therapy, potentially supporting retention and reinforcing the high margin recurring pod model Insulet is leaning on.
Insulet's current analyst narrative points to revenues of US$4.5b and earnings of US$675.9 million by 2029, which reflects forecast yearly revenue growth of 13.7% and an earnings increase of about US$300.6 million from earnings today of US$375.3 million.
Uncover why Insulet's fair value indicates a 12% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view focuses on Omnipod 5 adoption risk. The most cautious analysts expected Insulet to reach about US$4.1b of revenue and US$682.2 million of earnings by 2029, using a lower 17.5x P/E. Those estimates were set before Omnipod Discover, so you may see those forecasts and opinions shift as data tools gain attention.
Explore 4 other Insulet fair value estimates, including one that suggests as much as 20% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Insulet research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Insulet. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Insulet's overall financial health at a glance.
Looking For More Investment Ideas Beyond Insulet?
Once you have a view on Insulet, it can be helpful to compare it with other opportunities that match your risk profile and income goals using the Simply Wall St Screener.
- If you want to focus on value and quality together, take a look at our 27 high quality undervalued stocks that combine solid fundamentals with potentially attractive pricing.
- For investors who care most about balance sheet strength and business resilience, filter candidates using the list of solid balance sheet and fundamentals (25 results) to see which companies meet your thresholds.
- If you are hunting for under-the-radar opportunities, you can scan a curated 21 high quality undiscovered gems that may not yet be widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com