


Why KLA (KLAC) Is Getting Attention Now
KLA (KLAC) is under pressure after fresh warnings that component shortages and cleanroom constraints could limit semiconductor equipment shipments into 2027, just as investors look ahead to an earnings update tied to AI infrastructure demand.
The recent warnings have landed on a stock that was already under pressure, with KLA’s share price down about 22% over the past month and roughly 31% over 90 days, even though the year-to-date share price return is still positive at 14.25% and the 1-year total shareholder return is 23.77%. This builds on very large 3-year and 5-year total shareholder returns that suggest long-term holders have benefited from a powerful compounding story, while short-term momentum has clearly faded as investors reassess supply chain risk against expectations for AI-driven demand.
Seize this pullback in KLA to reassess your exposure to chip equipment and AI infrastructure by scanning our curated list of 55 AI infrastructure stocks.KLA now trades at a sharp discount to consensus targets, yet intrinsic value estimates point even lower. Where does fair value actually sit after this slide, and how wide is the real gap between price and the models?
Most Popular Narrative: 38% Undervalued
KLA closed at $145.61 while the most followed narrative pegs fair value at $233.77. The current slide lines up with a sizeable valuation gap that hinges on how durable its backlog and AI linked equipment demand really prove to be over the next several years.
Rising AI infrastructure and high bandwidth memory investment is lifting wafer equipment demand, and KLA’s backlog of around US$12.5b with lead times that extend into 2027 and 2028 supports multi year visibility that can translate into higher revenue and earnings quality.
See why 117 investors see KLA as 38% undervalued.
Result: Fair Value of $233.77 (UNDERVALUED)
Still, this narrative can break if tariff and memory cost headwinds persist, or if KLA’s long dated US$12.5b backlog sees delays or cancellations.
Find out about the key risks to this KLA narrative.
Another View: What KLA’s P/E Is Really Saying
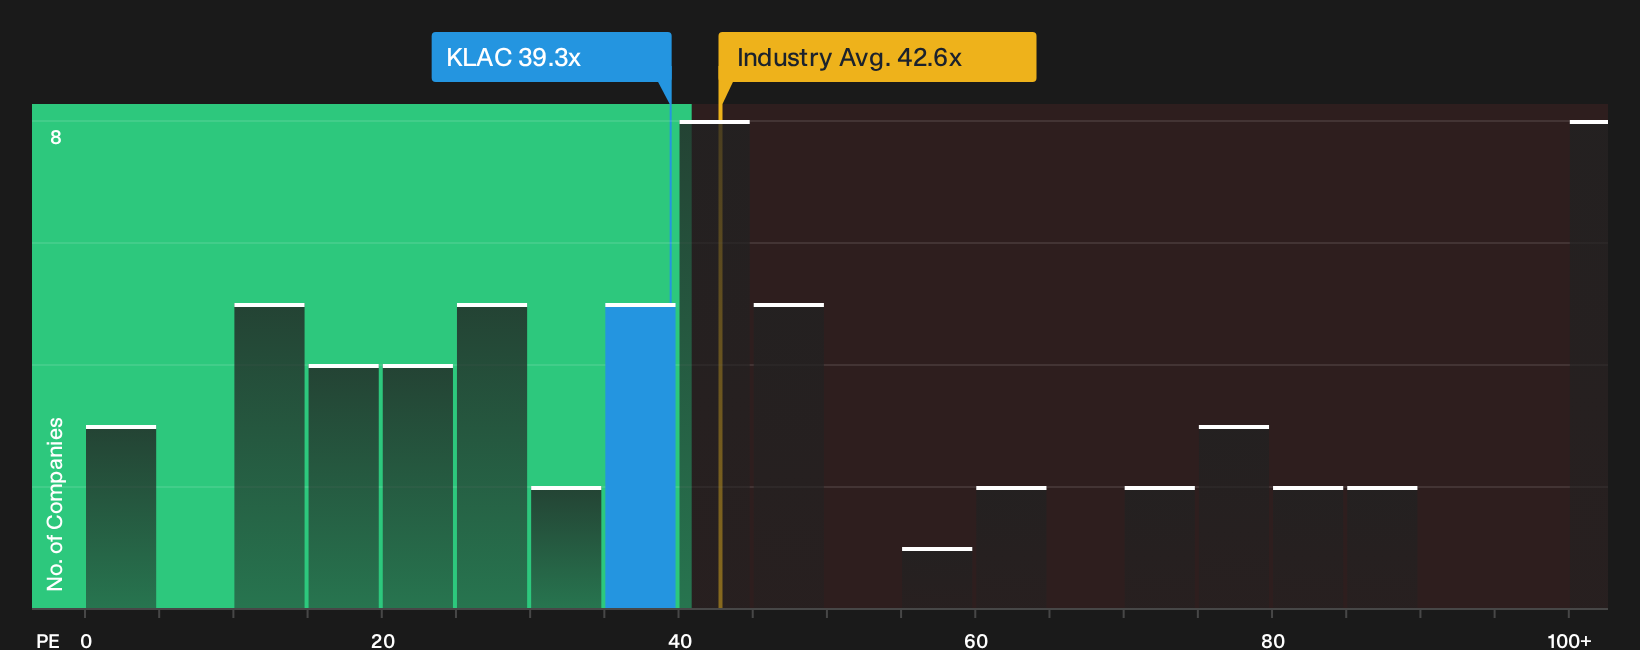
The first narrative leans on long term growth and backlog visibility. A simpler yardstick, the current P/E of 39.3x, paints a more mixed picture for KLA. It is below the broader US Semiconductor average of 42.6x, yet above the peer group on 36.9x and almost exactly in line with the fair ratio of 39.6x. That combination points to limited room for error if earnings forecasts or AI related demand soften.
For investors trying to weigh this against the 38% undervalued fair value story, the key question is whether today’s multiple already reflects enough of the good news or still leaves a margin of safety if the backlog or China exposure disappoints.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on KLA’s valuation and demand outlook make this a good moment to move quickly, review the data, and pressure test your own thesis against 3 key rewards and 1 important warning sign.
Looking for more KLA-sized opportunities?
Do not stop at KLA. Use this pullback as a prompt to refresh your broader watchlist and line up your next few potential ideas before the crowd moves.
- Target quality at a discount by scanning our 27 high quality undervalued stocks and focus on businesses where fundamentals and price still look out of sync.
- Lock in potential income streams with our 5 dividend fortresses and concentrate on companies that pair higher yields with resilient payouts.
- Protect your downside risk by reviewing the 30 resilient stocks with low risk scores and concentrate on stocks with sturdier balance sheets and steadier risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com