


Will New Product Launches Change Del Monte's (DMC) Narrative
- Del Monte has rolled out six fresh products, ranging from Red & Green Chimichurri sauces to Medjool dates and fruit-based snacks, alongside new Del Monte Gold Pineapple formats in 100% juice.
- The closer coordination between Del Monte Fresh and Foods teams around premium pineapple and ready-to-eat fruit points to a broader push into higher-value, convenience-led prepared offerings.
- We will now see how Del Monte's investment narrative could be influenced by this expanded premium pineapple and prepared foods lineup.
Scan how Del Monte’s push into premium fresh snacks compares with other producers going after the same convenience trend by reviewing list of solid balance sheet and fundamentals (25 results).
Del Monte Investment Narrative Recap
To own Del Monte, you need to believe the shift toward premium pineapple, branded prepared foods and fresh snacks can gradually reshape earnings, even while bananas, freight and farming costs stay tough. The current product push fits that story but does not change the near term focal point, which is execution on mix and efficiency.
The biggest swing factor still looks like whether higher margin prepared and value added lines can scale fast enough to offset weak banana profitability. On the risk side, cost inflation, disease pressure and a dividend that is not well covered by earnings remain clear pressure points for the business model.
Among the new items, the expanded Del Monte Gold Pineapple formats in 100% juice are most relevant for the existing catalyst list. They directly tie into the plan to move more Costa Rica acreage toward proprietary pineapples and give the company a way to extend that fruit into branded, higher value packaged offerings.
If these pineapple formats gain traction, they could help support the mix shift toward prepared and value added revenue that analysts already highlight, while still leaning on Del Monte’s long standing pineapple reputation. The operational test is whether sourcing, packing and distribution costs stay under control so that any lift in pricing power does not get absorbed by freight, packaging or farming expenses.
Del Monte's current analyst narrative points to revenue of US$5.8b and earnings of US$398.1m by 2029. That profile is built on 10.3% yearly revenue growth and an earnings increase of about US$364m from US$34.0m today.
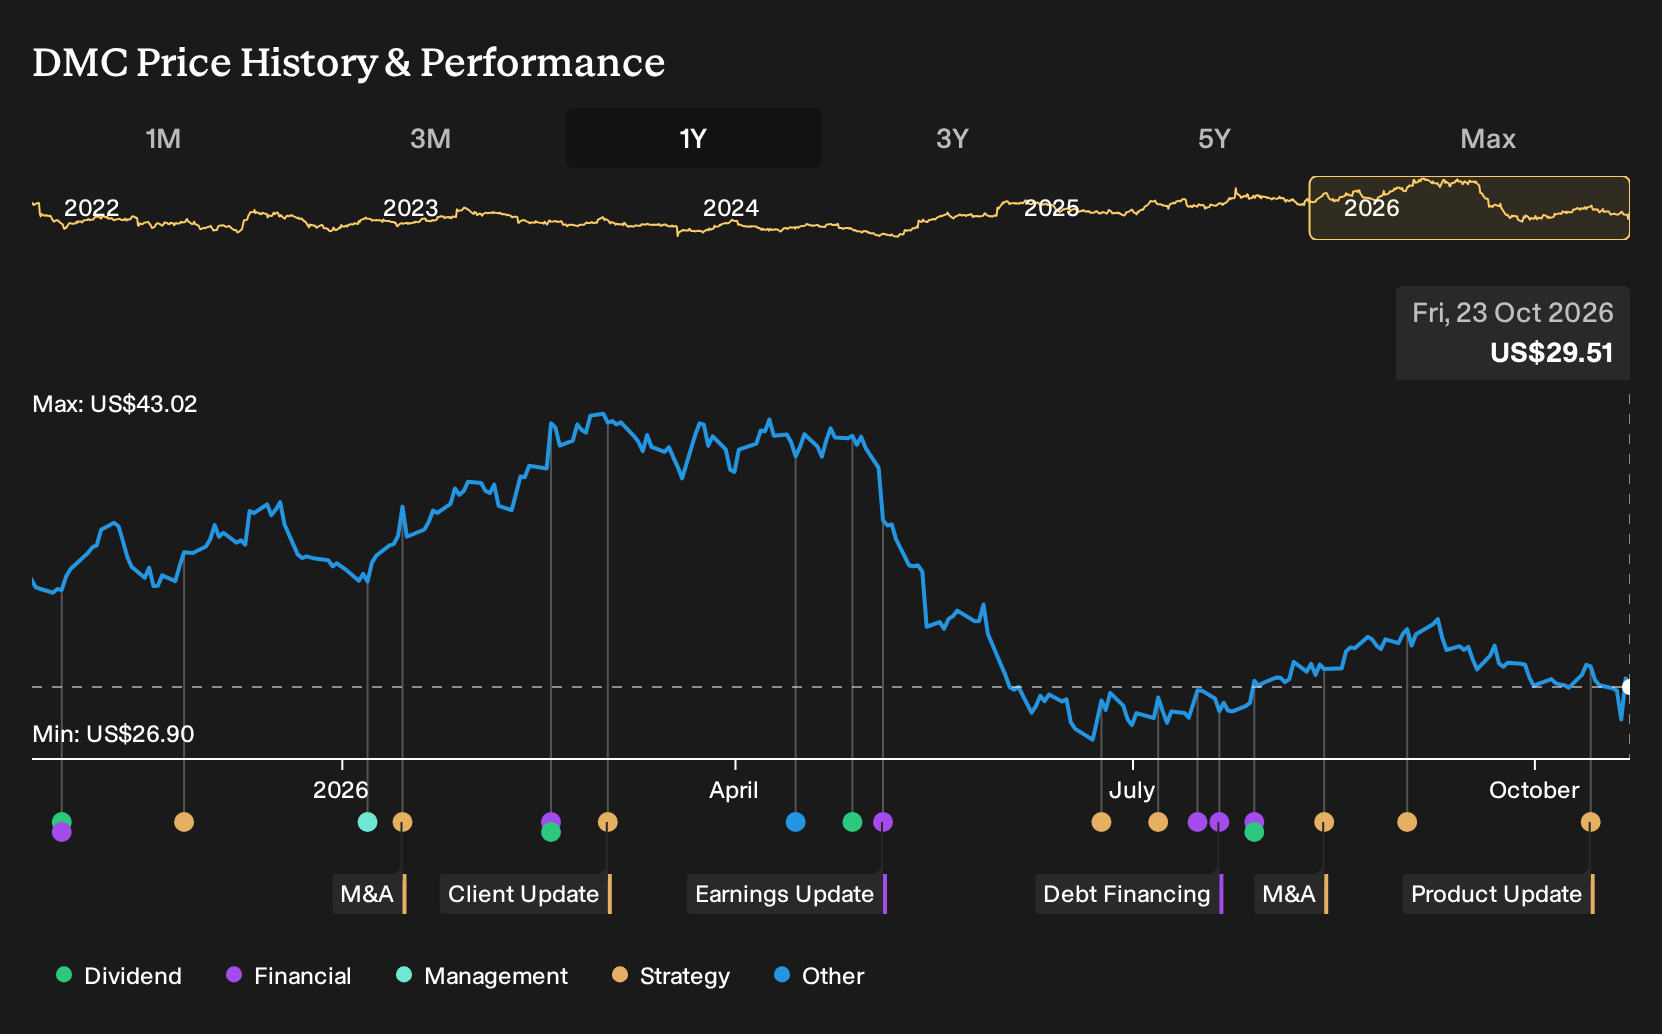
Discover how Del Monte's fair value indicates a 76% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community cluster between US$33.51 and US$52 per share, which leaves a wide gap between the most cautious and most optimistic Del Monte scenarios. Those private investors are not factoring in the new premium fruit and snack launches yet, so you are weighing their models against rising cost risks and fresh product catalysts that could pull actual performance in very different directions. Opinions clearly differ, so explore multiple angles before deciding how Del Monte fits your portfolio.
Explore 2 other Del Monte fair value estimates, including one that suggests as much as 76% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Del Monte research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Del Monte. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Del Monte's overall financial health at a glance.
Looking for more investment ideas beyond Del Monte?
If Del Monte has sharpened your focus on quality, income and resilience, use the Simply Wall St Screener to line up a broader watchlist that fits the way you like to invest.
- For investors hunting for quality at a sensible entry point, scan a curated set of value opportunities through the 27 high quality undervalued stocks.
- If reliable income is your priority, use the screener focused on dependable payers to surface 5 dividend fortresses that might suit a yield-focused strategy.
- When balance sheet strength matters most, filter for resilient businesses by reviewing a 30 resilient stocks with low risk scores that aims to keep downside risk in check.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com