


Did Expected Earnings Drop Just Shift Patrick Industries (PATK) Investment Narrative?
- Patrick Industries is expected to report year-over-year declines in earnings and revenue for the quarter ended September 2026, with market commentary pointing to a cautious outlook on the upcoming results.
- The combination of lower projected earnings and revenue, along with muted expectations for an earnings surprise, highlights operating pressure that contrasts with prior hopes tied to diversification and merger-driven efficiencies.
- We will now look at how Patrick Industries' investment narrative is affected by the anticipated earnings and revenue pressure flagged in recent estimates.
Compare Patrick Industries' set of earnings headwinds with other construction and manufacturing peers by scanning our hand picked list of list of solid balance sheet and fundamentals (25 results) for ideas with stronger fundamentals.
Patrick Industries Investment Narrative Recap
For a shareholder in Patrick Industries, the core belief is that a more diversified components platform across RV, Marine, Powersports and Housing can support earnings through cycles. The expected year over year decline in quarterly earnings and revenue challenges that thesis at the margin, but it mainly tests how resilient those non RV end markets and higher value product lines really are in a softer backdrop.
The key near term swing factor is how quickly the business can convert that broader footprint and higher content per unit into consistent cash generation, especially with debt not well covered by operating cash flow today. The biggest risk remains weaker than expected RV demand and dealer discipline that keeps working capital elevated. This would leave Patrick Industries with less flexibility around debt reduction and capital returns if the current pressure on results persists.
With no fresh company announcements tied directly to this earnings setup, the planned merger with LCI Industries is still the most relevant backdrop for the current news. Management has outlined a combined revenue base of about US$8.1b, roughly US$1b of adjusted EBITDA and a target of US$150m in annual cost synergies. Together, these figures frame how investors might think about the longer term earnings power behind a softer quarter.
That combination, if executed cleanly, could matter more for the medium term story than one weak reporting period. For you as a shareholder or prospective investor, the link is straightforward. Near term earnings pressure and any working capital strain increase the execution bar on extracting those procurement, supply chain and overhead efficiencies, because missteps here would compound the existing risk that margins do not improve meaningfully from current levels.
Patrick Industries Forecast Setup To 2029
Patrick Industries' narrative projects US$4.4b revenue and US$229.9 million earnings by 2029. This aligns with analyst expectations for revenue to grow by 3.6% a year and for earnings to rise by about US$82.6 million from US$147.3 million today.
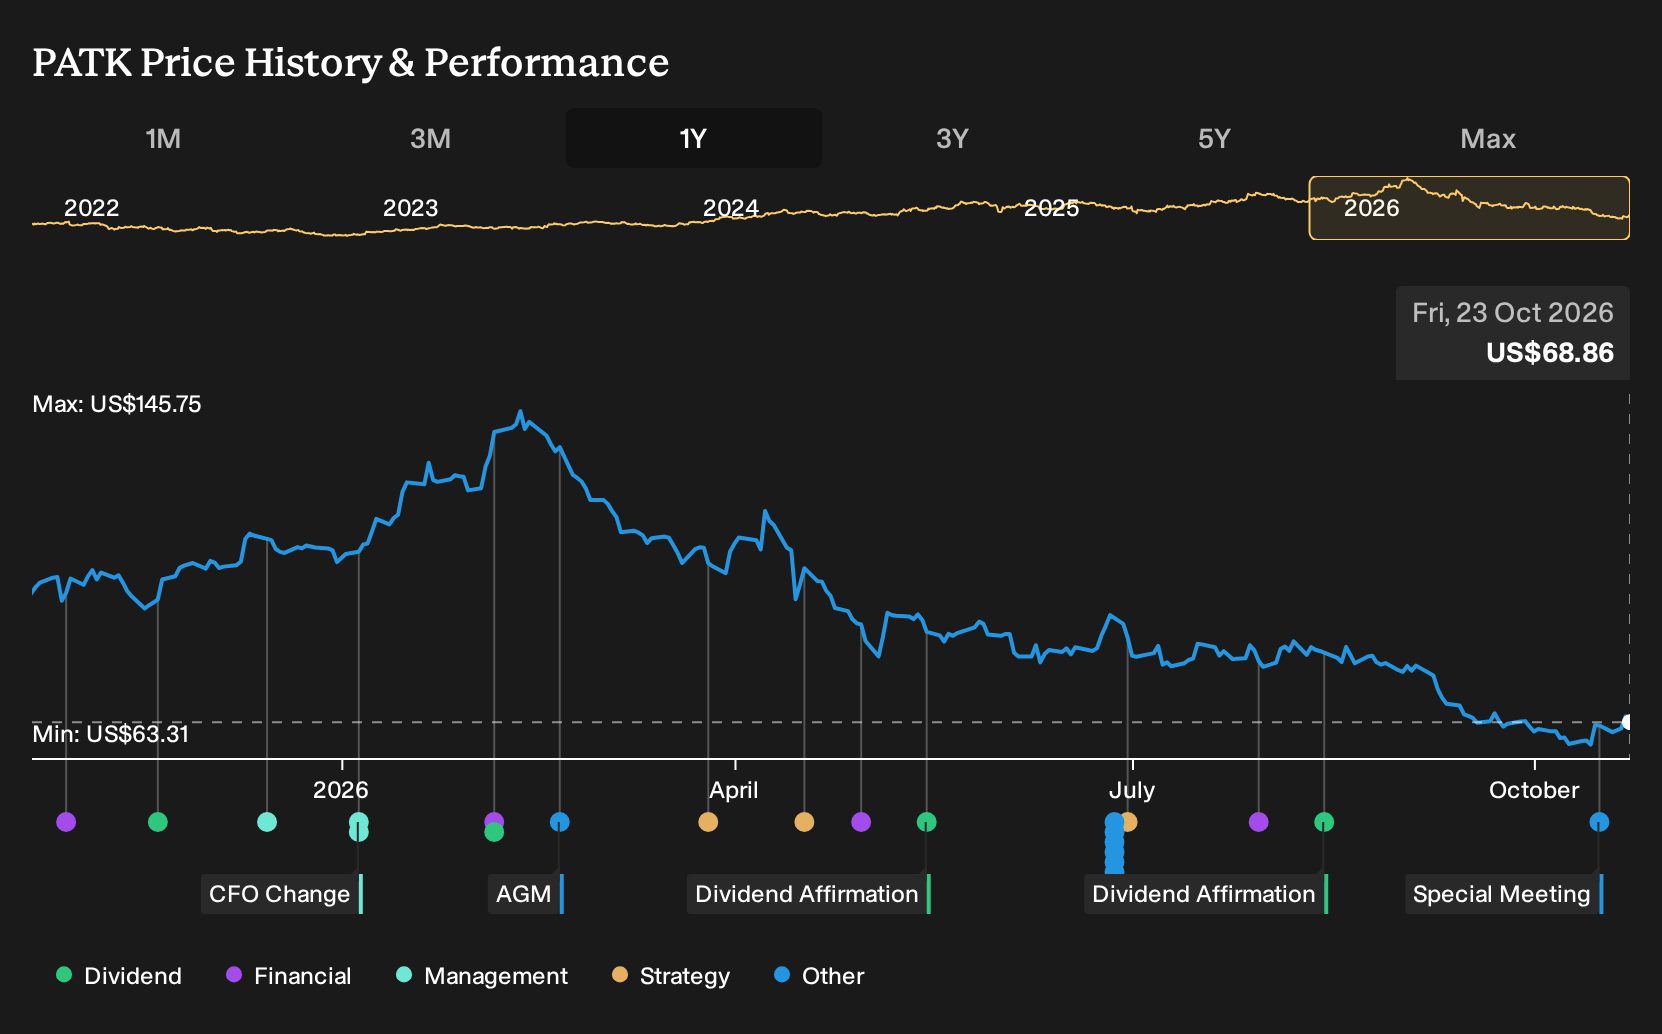
Uncover why Patrick Industries' fair value indicates a 46% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the lowest analysts focus on a slower dealer restock as the key risk for Patrick Industries, which feeds into a more cautious story than the consensus. They were modeling about US$4.5b of revenue and US$252.5 million of earnings by 2029, yet still pinned fair value near US$68. Opinions could easily shift once this earnings news lands, so treat these pre news narratives as starting points and compare a few viewpoints before deciding how you feel.
Explore 3 other Patrick Industries fair value estimates, including one that suggests it could be worth just $75.00.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Patrick Industries research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Patrick Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Patrick Industries' overall financial health at a glance.
Looking for more Patrick Industries style ideas?
If this Patrick Industries setup has you rethinking your watchlist, broaden the field and let data do more of the heavy lifting by scanning for other businesses that better match your risk, income, or quality preferences.
- For investors who want potential upside without ignoring quality, scan a curated group of 21 high quality undiscovered gems that combine solid fundamentals with relatively low market attention.
- If capital preservation sits higher on your list than headline growth, filter for 30 resilient stocks with low risk scores that score well on balance sheet strength and earnings stability.
- Income focused readers can zero in on 5 dividend fortresses that pair yields above 5% with an emphasis on resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com