


Why Valero Energy (VLO) Is Back In The Spotlight
Valero Energy (VLO) is back in focus after third quarter 2026 earnings showed much higher net income, reflecting stronger refining margins, tight fuel supply, and increased contributions from Renewable Diesel and Ethanol operations.
Recent trading shows that momentum in Valero Energy has cooled in the very short term, with the share price down 1.64% over one day and 5.72% over seven days. This is despite a 30 day share price return of 11.56% and a year to date gain of 153.63%, which indicate a strong upswing. That move comes alongside record third quarter results, a dividend increase to US$1.20 per share, and heavier cash returns to investors. Together, these factors help explain why long term total shareholder return sits at 150.32% over one year and more than 5x over five years.
Scan beyond Valero Energy and see how other refiners and energy producers stack up in the current fuel supply squeeze with the 27 high quality undervalued stocks.
After a run that has already rewarded Valero Energy shareholders heavily, and with earnings power now far higher than a year ago, does the balance of risk and reward still lean toward new buyers or recent holders taking profits?
Most Popular Narrative: 4% Overvalued
The most followed narrative pegs Valero Energy's fair value at about $401.53, a little below the recent $419.28 close. This frames today’s price as slightly ahead of that model and puts the focus firmly on how durable current refining strength really is.
The numbers imply that Valero Energy’s current share price, after an 88.1% rise over the past year and new price targets in the $400 to $450 range, already reflects a full valuation with limited room for error.
See why 63 investors see Valero Energy as 4% overvalued.
Result: Fair Value of $401.53 (OVERVALUED)
Still, the narrative can crack if large asset impairments or a renewed slump in renewable diesel profitability drag on Valero Energy's earnings power and investor confidence.
Find out about the key risks to this Valero Energy narrative.
Another View: Valero Energy Through The P/E Lens
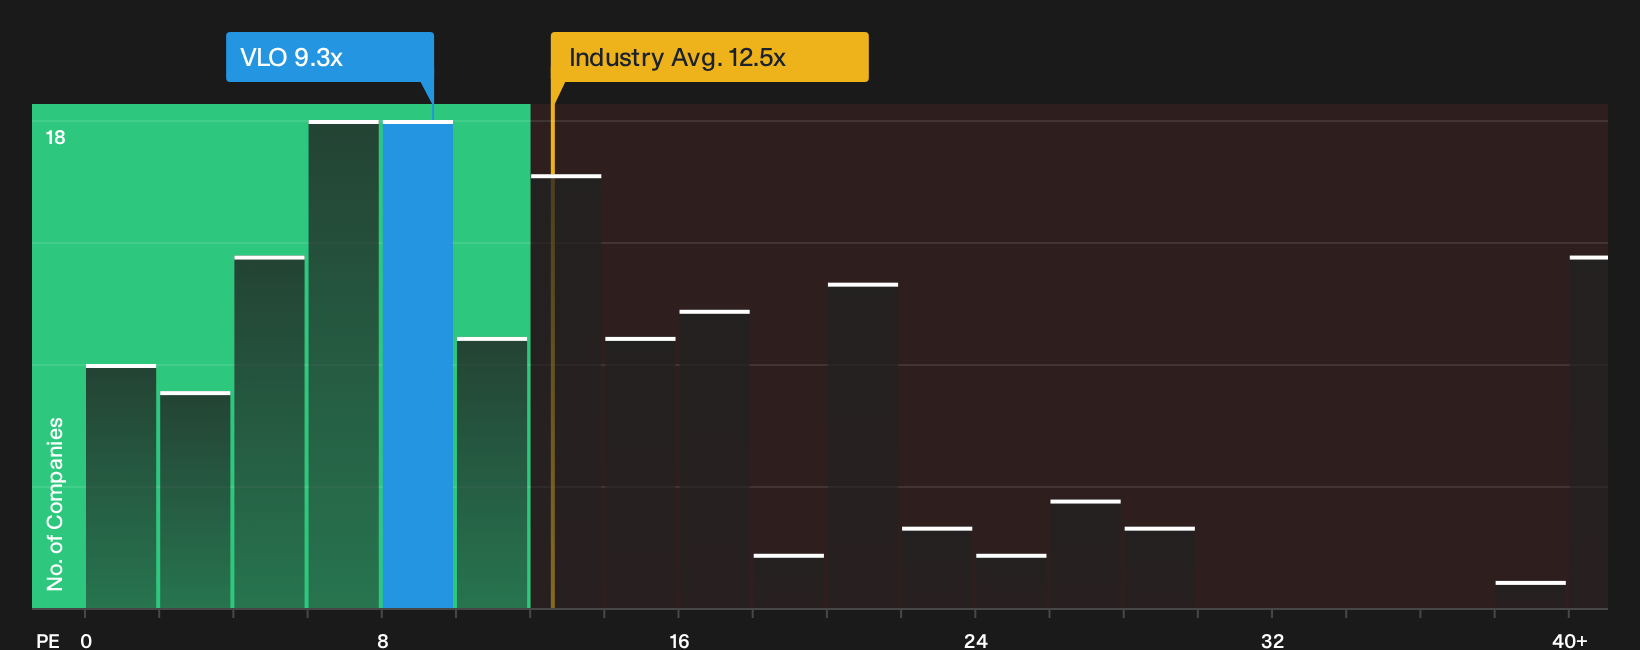
Analyst targets frame Valero Energy as slightly overvalued around $419, yet the P/E picture tells a different story. The stock trades on 9.3x earnings, while the US Oil and Gas industry averages 12.5x and the fair ratio points to 10.1x. That gap suggests the market is pricing in more risk than peers. Are investors being too cautious, or are analysts simply more conservative than usual?
To stress test that earnings multiple against today's assumptions and price, and to see what the numbers imply about this valuation, find out in our valuation breakdown.See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the data or a clear signal forming? Act while the information is fresh and check both sides of the story through the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Valero Energy?
If you stop with Valero Energy, you miss a wider field of potential opportunities that might fit your goals just as well or even better.
- Target faster potential gains by scanning focused opportunities through the 7 elite penny stocks with strong financials.
- Strengthen your portfolio core by filtering for companies on the list of solid balance sheet and fundamentals (25 results).
- Hunt for overlooked potential by checking the 21 high quality undiscovered gems before others catch on.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com