


Wix.com (WIX) K Health Tie Up Puts Its Valuation Back In Focus
Why Wix.com (WIX) is back in focus after the K Health tie up
Wix.com (WIX) is back on investor radar after partnering with K Health to plug PatientGPT, a clinical AI assistant, into its web platform for health systems.
The agreement pushes Wix.com further into healthcare technology, where PatientGPT’s tailored guidance is paired with Wix’s visual tools to build patient experiences that adjust in real time across care journeys.
Recent headlines around Wix.com’s AI partnerships arrive after a sharp 90 day share price return of 59.39% and a 7 day share price gain of 9.24%. However, the stock is still down 18.85% on a year to date share price basis, and long term total shareholder returns remain negative over one and five years. This leaves investors weighing whether the fresh AI and healthcare deals mark a shift in momentum or just a recovery rally within a longer, weaker stretch of performance.
Spot opportunities beyond Wix.com by scanning a curated group of 38 AI small caps that are also leaning into AI driven products and partnerships.After a 59% three month surge, yet still weak one and five year returns, Wix.com now sits at a tricky point on the chart. Does the current valuation still leave enough upside to justify the risk?
Most Popular Narrative: 3% Overvalued
On the latest numbers, the most widely followed narrative puts Wix.com’s fair value at $79.65, slightly below the last close at $81.94. This leaves only a narrow valuation gap for new buyers to consider.
AI powered feature rollouts and internal productivity gains have broadened from user facing tools to areas like customer care. Headcount has fallen by more than 40% since 2022 while service levels are reported as stable or better, which supports a path to higher operating margins as AI models and products such as Symphony and Harmony scale.
See why 35 investors see Wix.com as 3% overvalued.
Result: Fair Value of $79.65 (OVERVALUED)
Still, if AI tools make traditional websites less useful or no code rivals squeeze pricing power, the bullish Wix.com story could look stretched.
Find out about the key risks to this Wix.com narrative.
Another View: What Wix.com’s P/S Ratio Is Saying
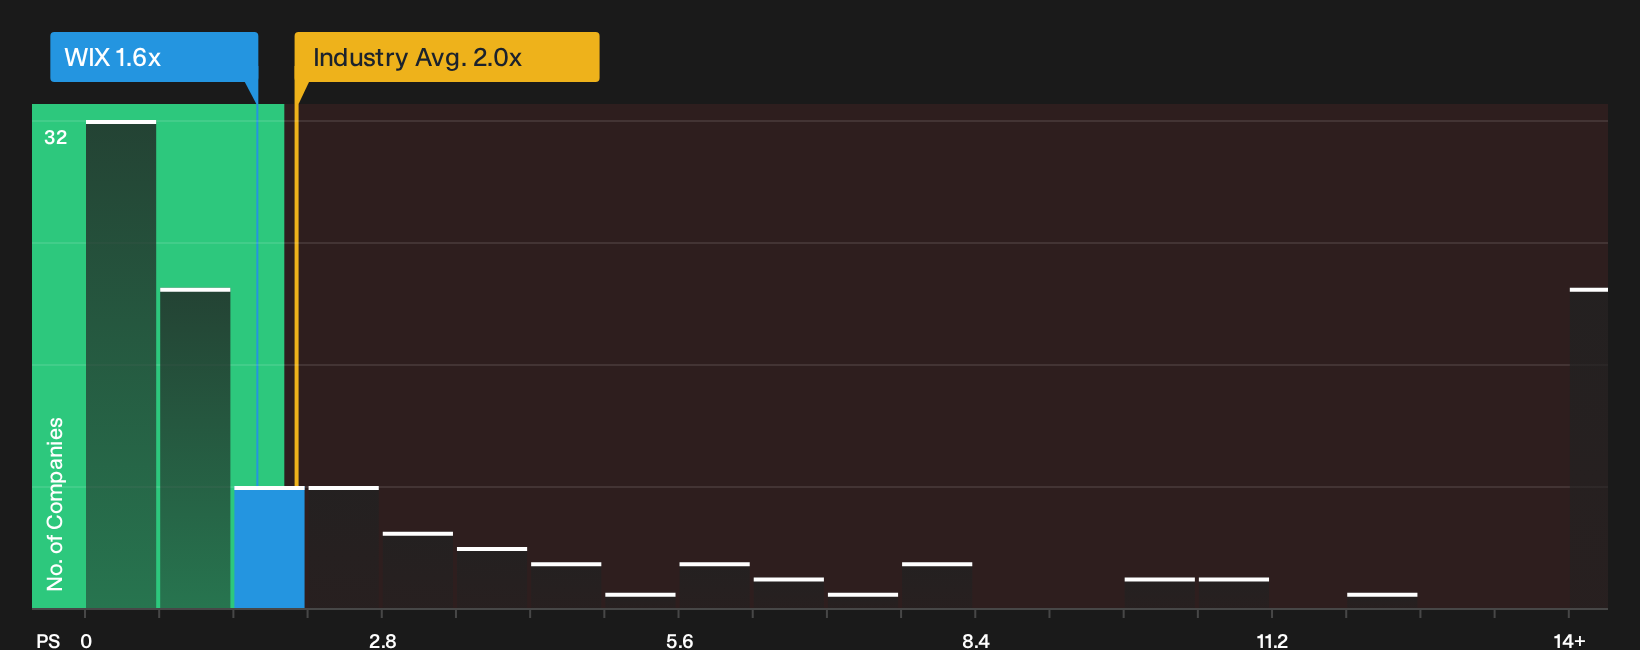
The first narrative frames Wix.com as only 3% overvalued on a fair value of $79.65 versus the recent $81.94 share price. On a pure P/S basis though, the picture is very different.
Wix.com trades on a P/S of 1.6x against a US IT sector average of 2x and a peer group average of 3x. The Simply Wall St fair ratio sits higher again at 3.8x. That gap suggests the market is pricing in far less optimism than either peers or the fair ratio might imply, and it raises a simple question for investors: Is this discount a signal of risk the consensus narrative is underplaying, or an opening that patient buyers are quietly watching?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Wix.com is clearly split, with fresh AI headlines set against mixed long term returns. Move quickly to review the underlying data, weigh both the potential upside and the flagged concerns, and ground your stance in 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Wix.com?
If Wix.com has your attention, do not stop there. Broaden your watchlist and give yourself more options before the next round of headlines hits.
- Target potential bargains early by scanning a focused list of companies trading below estimated value using the 27 high quality undervalued stocks.
- Strengthen your downside protection by filtering for businesses with clean finances and healthy balance sheets through the list of solid balance sheet and fundamentals (25 results).
- Spot under followed opportunities by zeroing in on financially solid but less crowded ideas in the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com