


Learn Why The Bull Case For Sandvik (OM:SAND) Could Change Following Earnings Beat
- Sandvik reported third quarter 2026 sales of SEK 37,728 million and net income of SEK 5,770 million, with adjusted EBITA margin reaching 22.5%.
- Stronger profitability was helped by vertical integration in tungsten and solid mining and automation exposure, even as the machining division prepares for a leadership change.
- We will examine how Sandvik's higher 22.5% adjusted EBITA margin reshapes the investment narrative around mining, automation and execution.
Scan other margin driven industrials that appear positioned for a similar execution story to Sandvik by reviewing our hand picked list of 95 robotics and automation stocks.
Sandvik Investment Narrative Recap
To own Sandvik, you need to be comfortable with a group that leans heavily on mining, automation and higher margin digital activities, while some more cyclical end markets stay mixed. The Q3 report, with SEK 37,728 million in sales and SEK 5,770 million in net income, supports the idea that the operating model can deliver solid profitability in that mix.
In the near term, the main swing factor is how resilient that 22.5% adjusted EBITA margin proves to be as tungsten benefits ease and machining leadership changes. The biggest risk is that weaker general engineering, automotive and Rock Processing margins drag on group profitability if demand or execution in those areas softens.
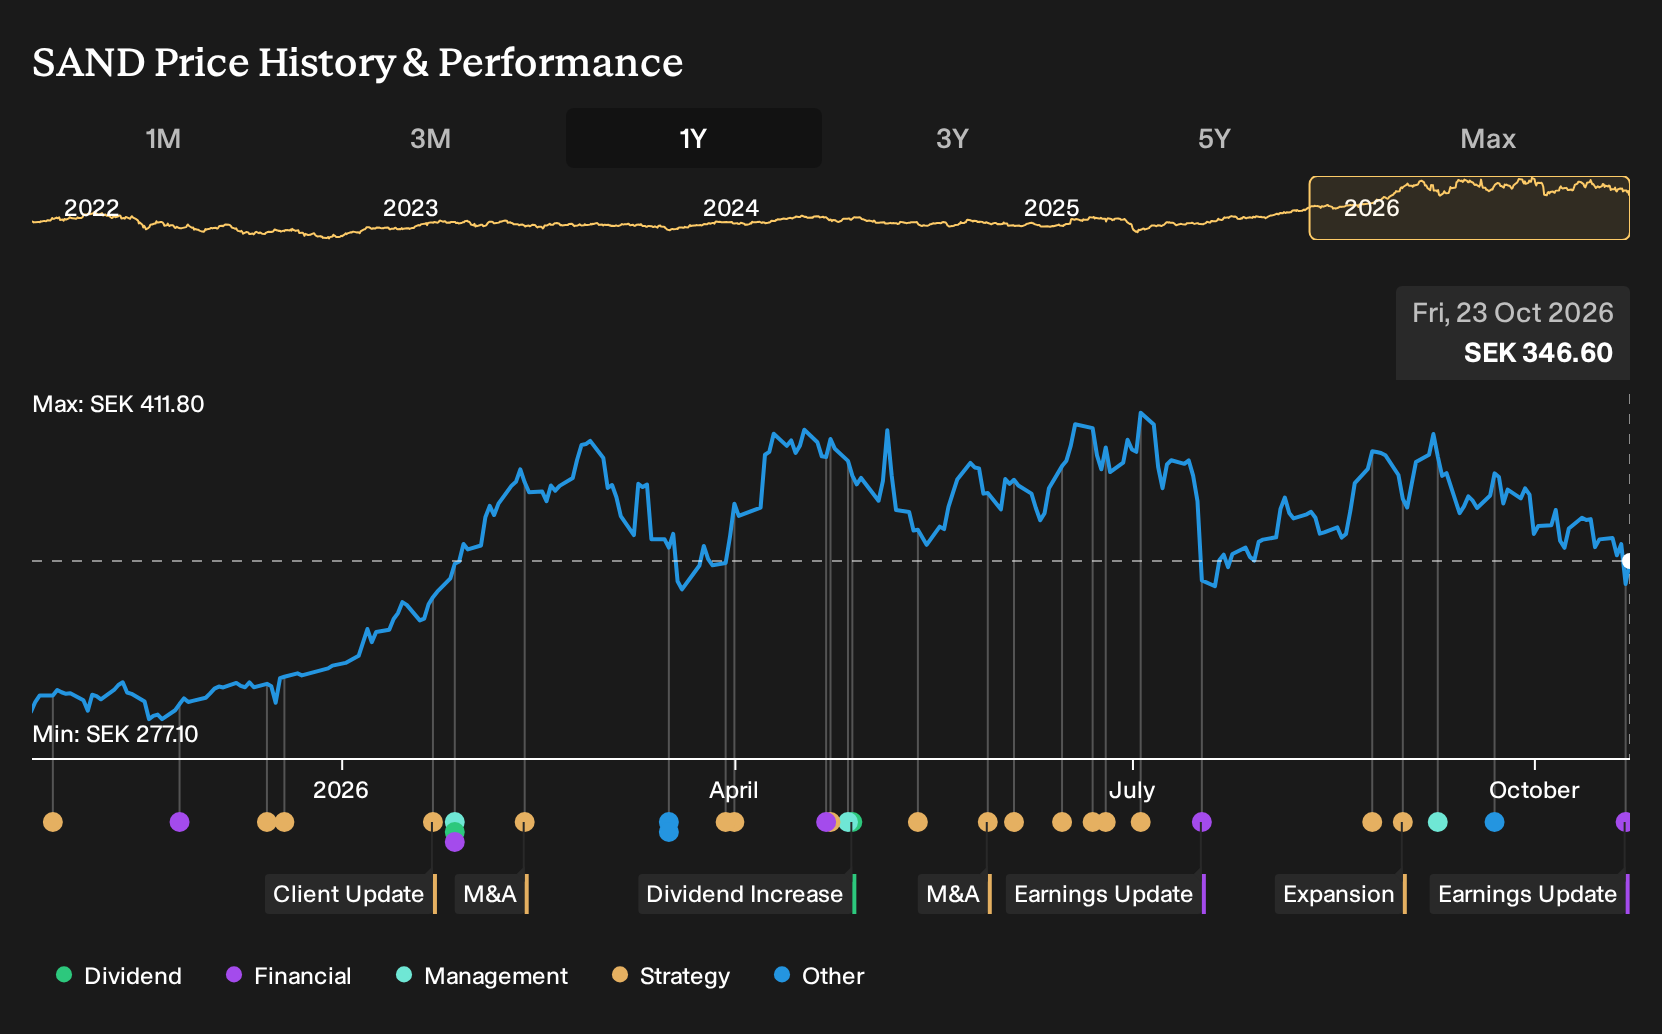
The most relevant update for this story is the third quarter and nine month 2026 earnings release on 22 October 2026. Sales for the first nine months reached SEK 105,164 million with net income of SEK 14,883 million, which keeps attention firmly on how Sandvik converts strong mining and automation demand into sustained earnings quality.
That report also highlighted higher basic EPS from continuing operations, at SEK 4.6 in Q3 and SEK 11.86 for the nine month period. For you as a shareholder, the key question is whether that profitability level can hold while tungsten timing effects fade and while management works on lifting structurally lower Rock Processing margins.
Sandvik's analyst narrative points to SEK 175.6b in revenue and SEK 26.7b in earnings by 2029. This assumes revenue grows at 10.8% per year and earnings rise by SEK 9.8b from SEK 16.9b today.
Uncover how Sandvik's fair value indicates a 13% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view zooms in on mining aftermarket normalisation. The most cautious Sandvik analysts were only baking in about 6.3% annual revenue growth and earnings of roughly SEK 22.1b by 2029 before this Q3 report. That is a much more restrained story than consensus, so treat today’s margin surprise as a prompt to compare several conflicting narratives.
Explore 4 other Sandvik fair value estimates, including one that suggests up to 14% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so consider relying on your own analysis.
- A great starting point for your Sandvik research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sandvik. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sandvik's overall financial health at a glance.
Looking for more investment ideas beyond Sandvik?
Once you have formed a view on Sandvik, it can help to compare it with other companies that share some of the same quality, income or risk traits using the Simply Wall St Screener.
- If capital preservation and steadier profiles matter most to you, start with a basket of 221 resilient stocks with low risk scores that score well on resilience.
- For readers hunting for quality at a reasonable entry point, consider scanning our 192 high quality undervalued stocks that pair healthy fundamentals with attractive pricing signals.
- Income focused investors who care about consistency rather than headlines may prefer to review a curated 226 dividend fortresses built around higher yielding payout streams.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com