


Will Raised Data Center Outlook Change American Tower Stock Narrative
- American Tower is set to report third quarter 2026 results on Oct. 27, with recent updates pointing to higher revenue and adjusted funds from operations expectations, alongside a raised full year outlook for data center revenue growth to about 15% on the back of record leasing activity.
- The stronger data center outlook highlights how CoreSite’s interconnected facilities and robust leasing pipeline are becoming a more meaningful earnings driver within American Tower’s broader tower and connectivity portfolio.
- We will now look at how American Tower's investment narrative could be influenced by the upgraded 15% data center growth outlook.
Scan beyond American Tower and evaluate other infrastructure plays that are riding similar data and connectivity trends through our curated list of 55 AI infrastructure stocks.
American Tower Investment Narrative Recap
To own American Tower, you need to believe that carrier demand for tower space and CoreSite data center capacity stays healthy enough to support steady tenant billings and AFFO growth, even if it is not rapid. The raised 15% data center revenue outlook puts more weight on CoreSite execution as a key short term earnings driver.
The flip side is that higher funding costs and elevated leverage still hang over the story. The October quarter will probably matter most for clarity on interest expense, refinancing timing and churn offsets. If the print only tweaks expectations around these items, the upgraded data center guide may not be a major catalyst by itself.
The most relevant update here is management lifting full year data center revenue growth guidance to about 15%, tied to record leasing activity at CoreSite. That points your attention firmly at how quickly American Tower can fill its existing capacity and bring new powered shell into revenue producing status.
For catalysts, the key questions now are whether that leasing flows through cleanly to AFFO per share and how it interacts with churn and debt service. Execution risk sits in keeping utilization high while funding development and refinancing obligations. Analyst expectations around modest earnings growth simply frame how much headroom there is if operations track the current outlook.
American Tower's narrative projects US$12.5b revenue and US$3.8b earnings by 2029. This assumes 4.4% yearly revenue growth and a US$0.4b earnings increase from US$3.4b today.
Uncover how American Tower's fair value indicates a 14% potential upside to its current price before the market closes the gap.
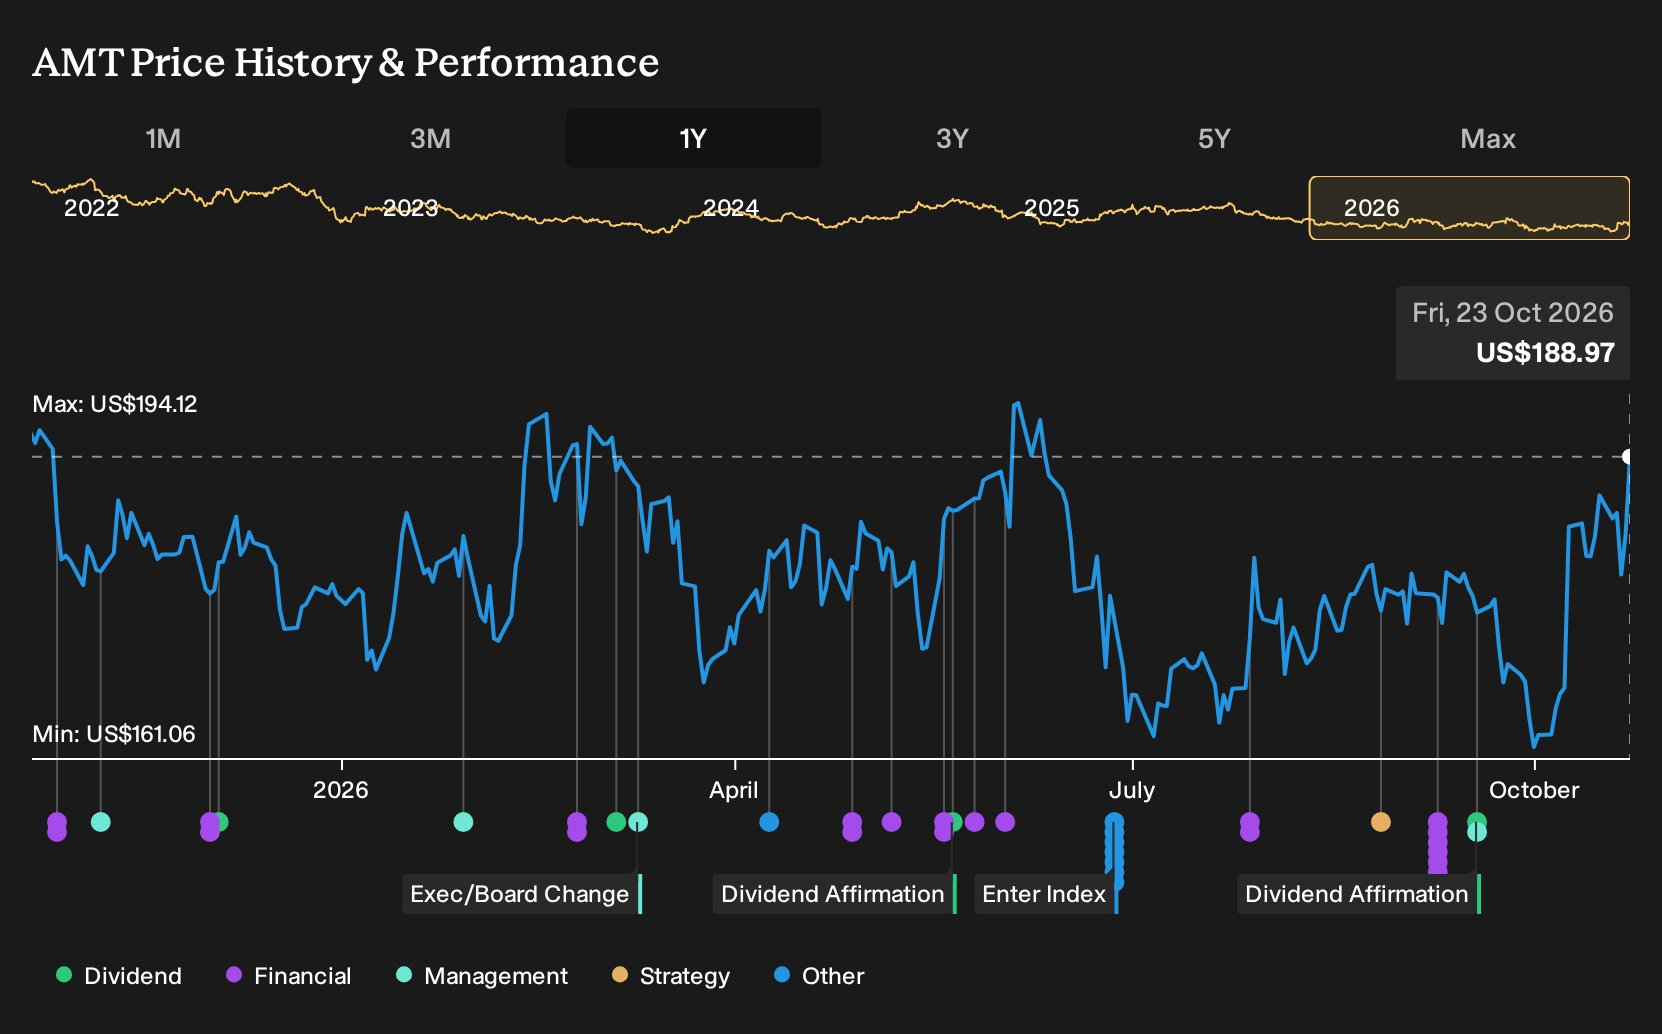
Exploring Other Perspectives
Across four fair value estimates from the Simply Wall St Community, American Tower lands in a wide band from about US$216 to US$298 per share. That is a big gap for the same ticker. Layer in the 15% data center growth outlook and interest rate risk, and you can see why opinions differ so much. Explore the full spread of views before deciding how this story fits your portfolio.
Explore 3 other American Tower fair value estimates, including one that suggests it could be worth just $215.70.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your American Tower research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for American Tower. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate American Tower's overall financial health at a glance.
Looking For More Investment Ideas Beyond American Tower?
Once you have a handle on American Tower, it can help to widen the lens and compare it with other opportunities that fit different risk and income profiles. The Simply Wall St Screener lets you do that quickly by filtering for traits that match how you like to invest.
- If capital preservation matters most to you, focus on companies that score well on resilience and balance sheet strength by reviewing a curated set of 30 resilient stocks with low risk scores.
- If dependable income is the priority, scan for businesses with higher yields and consistent payouts using a tailored group of 5 dividend fortresses.
- If you want ideas that are less picked over by the market, look through a targeted collection of 21 high quality undiscovered gems that pair quality fundamentals with lower profile coverage.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com