


Is IDEAYA Biosciences (IDYA) A Bargain After New ESMO Trial Data?
IDEAYA Biosciences (IDYA) is back in focus after new Phase 1 data for IDE849 in relapsed small cell lung cancer and other neuroendocrine tumors landed at ESMO 2026, highlighting updated survival and safety outcomes.
IDEAYA Biosciences shares have been choppy around the recent ESMO news, with the 1-day share price return down 3.9% and the 30-day share price return down 7.34%. However, the 1-year total shareholder return of 18.95% and 5-year total shareholder return of 61.89% suggest longer term holders have still seen meaningful gains as sentiment swings with each clinical update.
Scan other precision-oncology opportunities moving on fresh trial data with a curated set of 34 healthcare AI stocks aligned to themes similar to IDEAYA Biosciences.
IDEAYA Biosciences has pulled back on strong IDE849 and darovasertib updates, so the debate now is simple: Is the bigger opportunity still ahead, or did most of the upside already play out in the past year’s run and volatility?
Most Popular Narrative: 34% Undervalued
Analysts following IDEAYA Biosciences see a gap between the last close at $34.71 and a narrative fair value of $52.75, and that gap rests heavily on how the pipeline translates into durable oncology franchises over time.
The main factor that needs to go right is successful execution on multiple registrational programs, including darovasertib in uveal melanoma and IDE849 in extensive-stage small-cell lung cancer, while managing trial pivots and competitive pressure in DLL3 therapies.
The current valuation implies that the market is not fully crediting IDEAYA Biosciences for the potential of darovasertib, the MTAP/CDKN2A/KRAS franchise, the DLL3 Topo-ADC program, and a cash balance of about US$1.24b with a stated runway into 2030.
See why 1 investors see IDEAYA Biosciences as 34% undervalued.
Result: Fair Value of $52.75 (UNDERVALUED)
Still, two pressure points could upend the IDEAYA Biosciences bull case, including any delay to darovasertib approvals and weaker than expected IDE849 differentiation in the crowded DLL3 therapy space.
Find out about the key risks to this IDEAYA Biosciences narrative.
Another View: SWS DCF Model Flags Overvaluation
While the popular narrative pegs IDEAYA Biosciences at a fair value of $52.75, the SWS DCF model points in the opposite direction. On this framework, IDEAYA Biosciences screens as overvalued, with an estimated future cash flow value of $20.76 against the current $34.71 share price. That sort of gap raises a simple question for you as an investor: Which story feels more realistic for how cash generation might actually evolve over time?
Look into how the SWS DCF model arrives at its fair value.
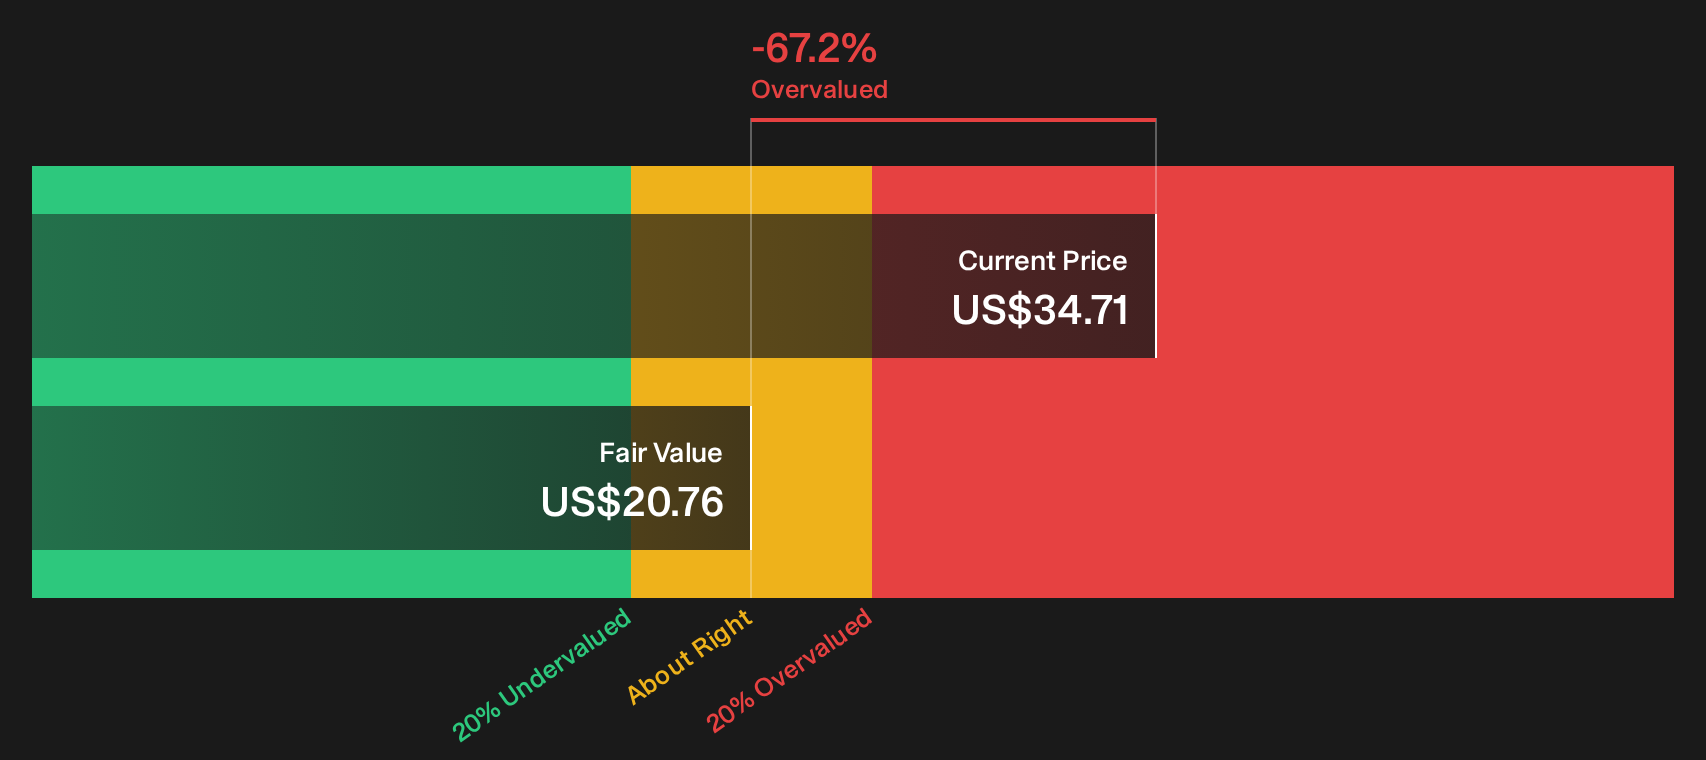
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out IDEAYA Biosciences for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around IDEAYA Biosciences can feel confusing, so review the key data points promptly and anchor your own stance with 1 key reward and 1 important warning sign.
Looking for more IDEAYA Biosciences style investment ideas?
If IDEAYA Biosciences has your attention, do not stop here. Use focused screeners to surface fresh candidates before they move and sharpen your watchlist.
- Target steady cash generators and stress test your income focus with a curated set of 5 dividend fortresses that may suit a yield oriented approach.
- Hunt for potential mispricings and widen your opportunity set by scanning a tailored pool of 21 high quality undiscovered gems before they land on everyone else's radar.
- Prioritise resilience and sleep easier at night by filtering the market for a 30 resilient stocks with low risk scores that fits your comfort with volatility and downside.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com