


Agree Realty (ADC) Has The Market Watching, But What Is Behind The Attention?
Agree Realty (ADC) has investors’ attention after third quarter 2026 earnings showed higher revenue and net income than a year earlier, along with raised AFFO guidance and a higher monthly common dividend.
Yet Agree Realty’s share price has moved the other way, with the stock down about 17% on a 90 day share price return and 7.5% year to date, even as the 3 year total shareholder return of roughly 40% points to much stronger longer run momentum.
Contrast Agree Realty's recent pullback with a curated 30 resilient stocks with low risk scores that have held up better on quality, balance sheet strength, and consistency in tougher market conditions.
Agree Realty’s share price has retreated while both analyst targets and intrinsic value estimates sit materially higher. The question now is how far that gap runs and where fair value plausibly anchors within that range.
Most Popular Narrative: 17% Undervalued
Agree Realty is priced at $66.70 against a widely followed fair value narrative of about $80.67, so the market is treating the current share price as a discount to that longer run view.
Record capital deployment in Q2 2026 of more than US$500 million across acquisitions, development and developer funding, together with higher 2026 investment guidance of US$1.6 to US$1.8 billion and a medium term goal of at least US$250 million of annual development and developer funding commencements, points to a wider asset base that can support higher rental revenue and AFFO over time.
See why 118 investors see Agree Realty as 17% undervalued.
Result: Fair Value of $80.67 (UNDERVALUED)
Still, the whole Agree Realty narrative relies on continued access to reasonably priced equity and debt, as well as on construction costs not eroding returns on new projects.
Find out about the key risks to this Agree Realty narrative.
Another View: Agree Realty Through The Earnings Multiple Lens
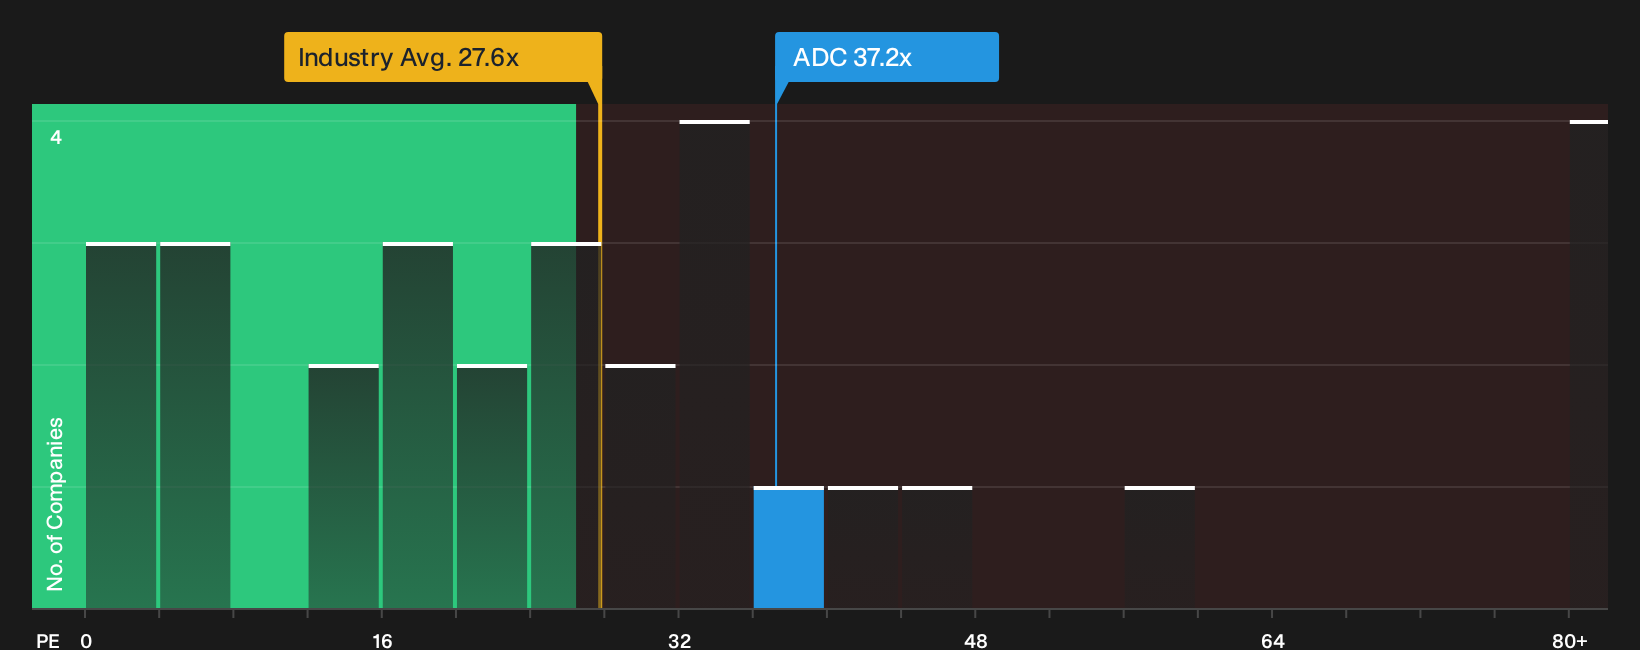
The first story around Agree Realty leans on fair value estimates and long term cash flow. A different picture appears when looking at the P/E ratio. ADC trades on 37.2x earnings, which is richer than the Retail REITs industry at 27.6x, the peer average at 24.3x, and even the 35.3x fair ratio estimate. That kind of premium can signal quality or it can signal valuation risk, so which side of that line do you think it falls on?
To see how those earnings multiples stack up against fundamentals and scenario work, See what the numbers say about this price — find out in our valuation breakdown..
Compare where the current P/E sits against both the broader industry and Agree Realty's own history in this context, using the visual snapshot in
Next Steps
Mixed messages around Agree Realty's valuation and earnings multiple only matter if you put them in context yourself, so weigh both the upside case and the concerns while there is still time to react, and then test that view against the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Agree Realty?
If Agree Realty has you rethinking valuation and risk, use that momentum. Broaden your watchlist now so you are not relying on a single story.
- Target resilient balance sheets first and filter for businesses with financial sturdiness using the list of solid balance sheet and fundamentals (25 results).
- Spot potential mispricings early by scanning companies that combine quality fundamentals with room for re rating through the 21 high quality undiscovered gems.
- Lock in income ideas by focusing on companies built around durable payouts with the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com