


Will New Green Ship Change Matson (MATX) Narrative
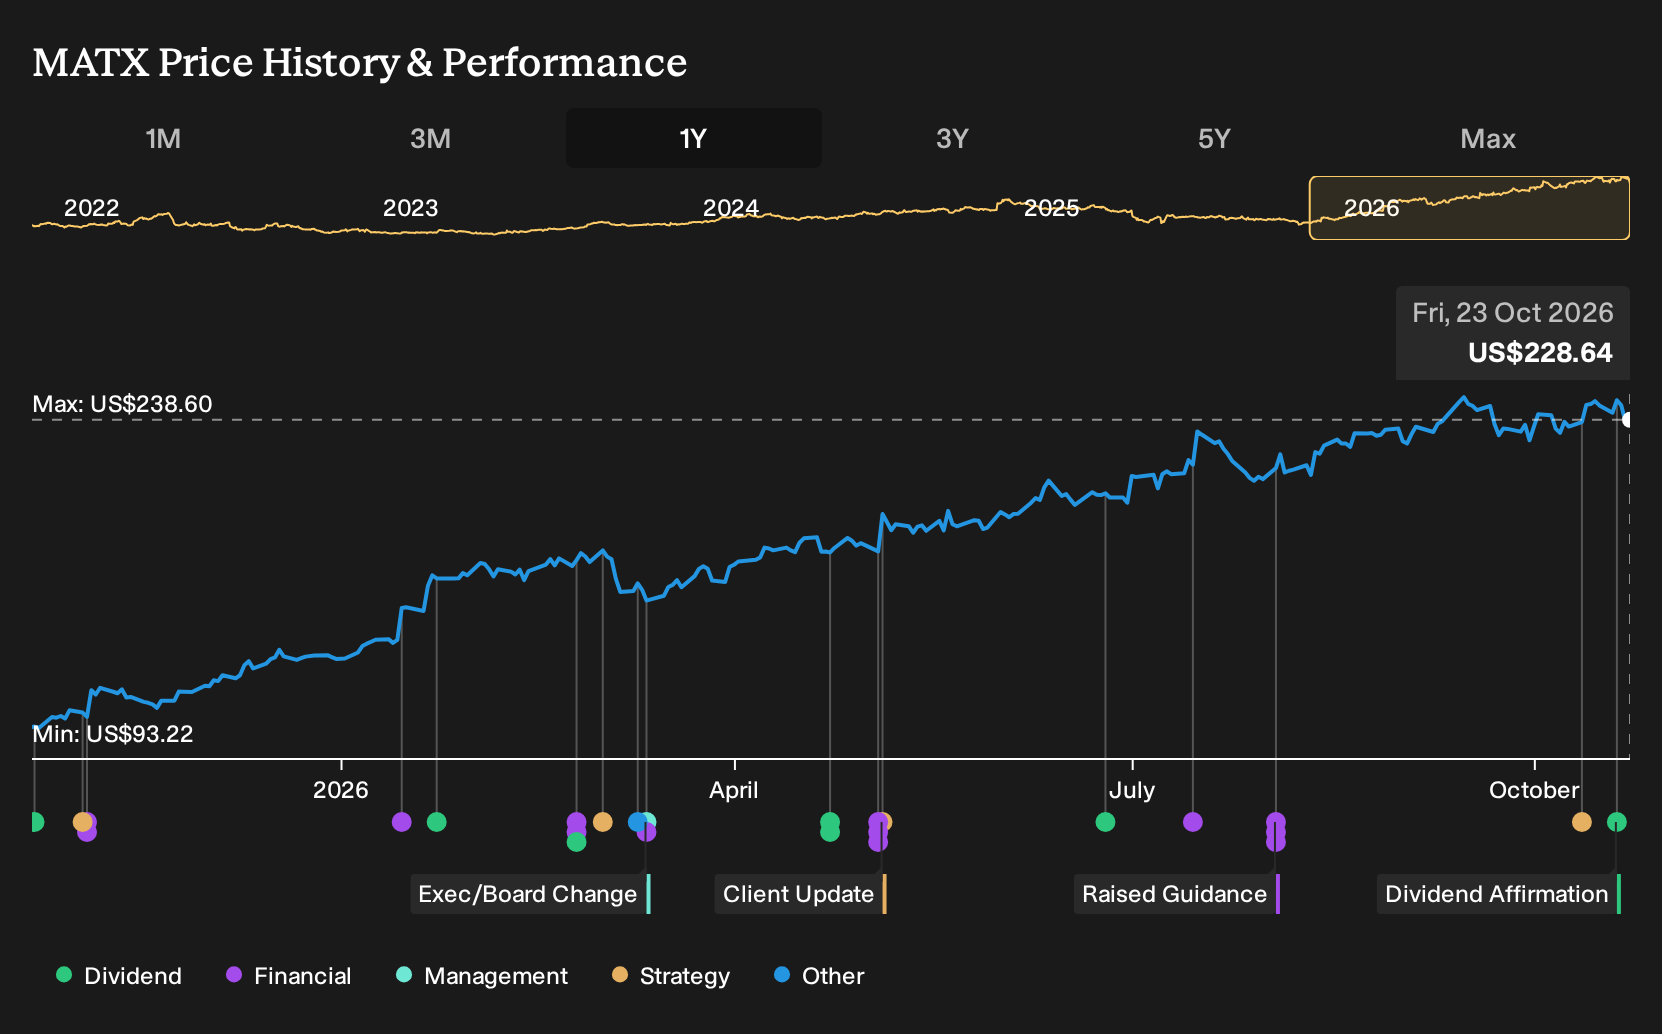
- Matson declared a fourth quarter dividend of US$0.38 per common share, payable on December 3, 2026 to shareholders of record on November 5, 2026. The company also recently christened the first of three LNG capable Aloha Class containerships at Hanwha Philly Shipyard for its China Long Beach Express and Hawaii services.
- The roughly US$1b spend on three Jones Act compliant, LNG ready Aloha Class vessels points to Matson focusing on fleet efficiency, environmental performance and reliability on its core Pacific routes, while continuing regular cash returns through dividends.
- We will look at how Matson's investment narrative is affected by the LNG ready Aloha Class fleet build and ongoing dividends.
Expand your watchlist beyond Matson by scanning a curated 5 dividend fortresses that delivers regular cash returns alongside ongoing investment in fleet efficiency and infrastructure.
Matson Investment Narrative Recap
To own Matson, you need to believe its premium Pacific services can keep attracting enough higher value freight while it refreshes the fleet without stretching the balance sheet. The short term swing factor is still volume and pricing in China and Southeast Asia services. The latest dividend affirmation does not materially change that central operating lever.
The bigger risk remains capital intensity. Around US$1b earmarked for LNG capable Aloha Class vessels can pressure free cash flow and margins if trade volumes soften or unit economics tighten. Regular dividends add another fixed cash commitment, so execution on vessel deployment and cost control matters more than the dividend headline.
The most relevant announcement here is the US$0.38 per share fourth quarter dividend. That payout indicates Matson is maintaining its regular cash return pattern even while the shipbuilding program ramps, which shows management is running both priorities in parallel rather than pausing one for the other.
For catalysts, recurring dividends can support investor interest while the LNG ready ships move through construction and into service between 2027 and 2028. The trade off is straightforward. Shareholders receive ongoing income today, while the real test for value comes when the new vessels replace older ships and their impact on operating costs and service reliability becomes clear.
Matson's current analyst narrative points to forecast revenue of US$3.9b and earnings of US$497.0m by 2029, based on an assumed 4.4% yearly top line growth rate and an earnings increase of about US$33.2m from US$463.8m today.
Uncover why Matson's fair value indicates a 21% potential upside to its current price, a discount that could narrow quickly if sentiment shifts.
Exploring Other Perspectives
One alternative angle on Matson focuses less on the dividend and new LNG ships and more on whether free cash flow can keep up with all that spending. The most cautious analysts were only looking for about US$4.0b of revenue and US$470.4m of earnings by 2029 before this news, so their fair value story is tighter. That gap with consensus shows how wide opinions can run, and it invites you to weigh both sets of expectations in light of the dividend affirmation and fleet expansion.
Explore 6 other Matson fair value estimates, including one that suggests as much as 52% downside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Matson research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Matson. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Matson's overall financial health at a glance.
Looking for more ideas beyond Matson?
If the Matson story has sharpened your thinking about income, balance sheets, and long term reinvestment, you can use that same lens on a wider set of companies with the Simply Wall St Screener.
- For investors who want income streams that aim to be both sizable and resilient, scan a focused group of 5 dividend fortresses that prioritize cash returns to shareholders.
- If capital preservation sits high on your list, focus on steadier businesses through a 30 resilient stocks with low risk scores that concentrates on lower risk profiles.
- When you are hunting for future leaders before they are widely followed, explore a 21 high quality undiscovered gems that combines quality fundamentals with limited current attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com