


Missed UBS Group's Rally? Here's The Bet Holders Made
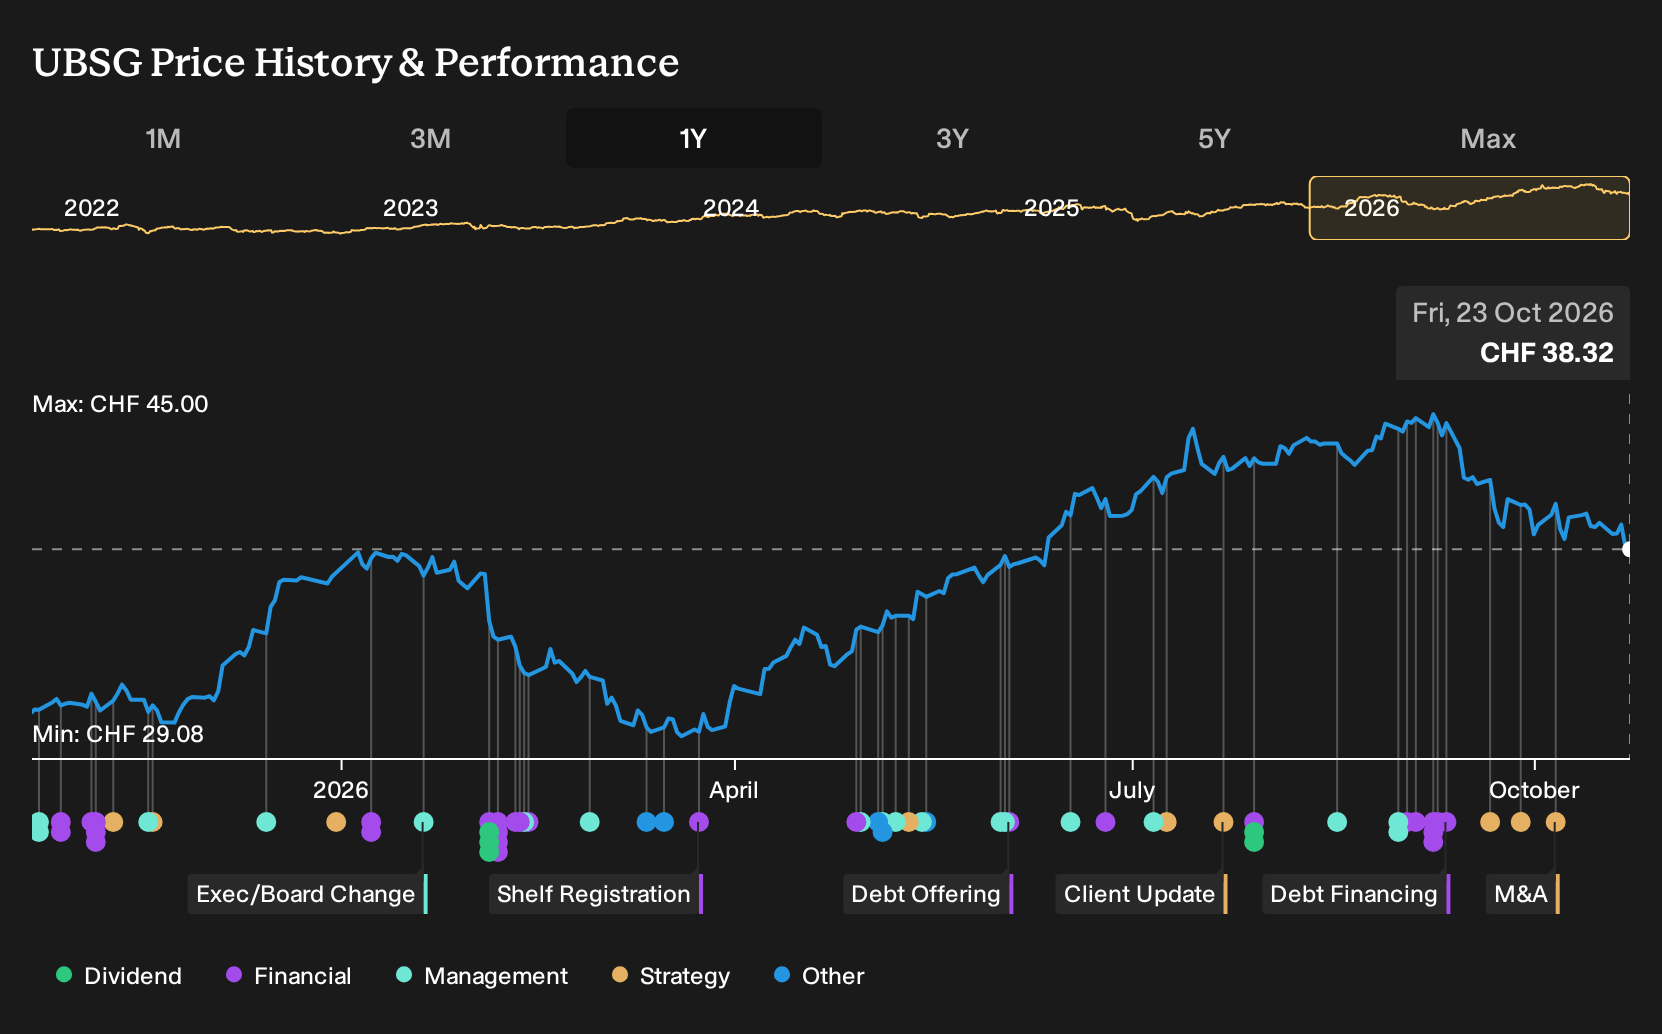
If you only glanced at the headlines about tougher Swiss capital rules and fresh compliance fines, UBS Group might have looked like a problem waiting to happen rather than a rewarding holding. Holding UBS Group over the past year would have returned 29.3%, including dividends. If you had been weighing up those opposing analyst views in October 2025, what did that clash between regulatory risk and integration promise really signal about the business you were backing?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
The easy part of this move is behind UBS Group. Zero in on 192 high quality undervalued stocks for companies trading below our estimates.
The Two UBS Group Stories Investors Had To Weigh
The shares cost CHF30.4 at the start of the period, and anyone looking at UBS Group then had to pick between two very different stories that both sounded plausible.
On the optimistic side, the Fair Value was set at CHF32.69, which sat 8% above the start price. That view leaned on Credit Suisse integration and digital investment helping revenue grow 4.1% with profit margins reaching 24.3% within three years.
The more cautious narrative put Fair Value at CHF21, or 31% below the start price. This camp focused on Swiss capital reforms that could require CHF24b to CHF42b of extra capital, which might constrain profitability and future shareholder distributions.
What The UBS Group Results Actually Tested
UBS Group posted Q2 2026 revenue of US$13,581m and net income of US$2,800m, both above Q2 2025, with net margin edging up from 20.2% to 20.6%. That pattern, together with Q1 and Q2 2026 profit growth and advancing Credit Suisse integration, leaned toward the optimistic case. Rising capital demands and the US$125m AML fine still gave the cautious story real weight, so the evidence cut both ways.
The lesson is simple. When a bank promises efficiency gains, do not just watch profit. Track net margin and the capital ratio together to see whether higher earnings rely on taking on more regulatory strain.
What UBS Group's Current Price Already Assumes
UBS Group now trades at CHF38.32, above where it started the past year and above the Fair Value that this Narrative outlines. That gap reflects a view inside the Narrative that the market price already builds in strong earnings power and successful Credit Suisse integration.
The Narrative highlights that a buyer today is effectively assuming resilient returns despite capital reform and legal overhangs. The core question is how those pressures interact with the belief that UBS Group can keep turning its integration, fee growth and technology spending into durable profitability.
"The numbers imply the UBS Group share price already reflects continued strong earnings power, successful Credit Suisse integration and resilient fee growth, leaving limited room for disappointment if capital rules or legacy risks prove more challenging than expected."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
Find Your Own Contrarian Opportunity
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 37% below our estimate - helps clients unravel complex AI related failures involving human factors and regulation.
- Company 2 - 30% below our estimate - builds AI centric hardware and software tools supporting hybrid work and video collaboration.
- Company 3 - 28% below our estimate - converts a single tech platform plus AI tools into lower cost to serve investors.
Those are three of them. See all 204 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com