


DorianG (LPG) Could Be 1% Undervalued Following Debate Over Peak Tanker Pricing
DorianG (LPG) is back in focus after a strong run that has split opinion between investors who point to its solid balance sheet and upgraded fleet, and others who see pricing already reflecting peak tanker conditions.
Recent trading has been brisk, with DorianG’s share price up 5.09% over the past day and 19.29% over 90 days. This has contributed to a 118.42% year to date share price return and an 867.73% five year total shareholder return that many investors interpret as strong momentum rather than a fading story.
Scan opportunities beyond DorianG by reviewing our hand picked 27 high quality undervalued stocks that also pair firm balance sheets with cash flow support for their tanker or energy exposure.
Bulls see DorianG as a cash rich LPG pure play, while bears see a tanker stock already priced for perfection after its sharp run. Which story do the current valuation markers actually support next?
Most Popular Narrative: 1% Undervalued
DorianG closed at $54.06 against a narrative fair value of $54.60, which puts the stock almost exactly in line with that framework while still highlighting how much has to go right for current pricing to hold.
The main thing that has to go right is that DorianG continues to execute on its irregular dividend and fleet renewal approach, while managing exposure to rising VLGC supply and costly canal or routing constraints.
The current valuation and the view that DorianG is fairly valued and bearish implies the share price already reflects high freight earnings, sizable past cash dividends, and premium market expectations that leave limited room for further rerating without new positive surprises.
See why 43 investors see DorianG as 1% undervalued.
Result: Fair Value of $54.60 (ABOUT RIGHT)
Still, the thesis around DorianG can be shaken if the enlarged VLGC orderbook pressures freight rates or if high Panama Canal fees keep eating into realized TCEs.
Find out about the key risks to this DorianG narrative.
Another View: DorianG Through A Cash Flow Lens
The narrative fair value for DorianG sits at $54.60, almost on top of the recent $54.06 share price, yet the SWS DCF model presents a different picture. On that cash flow view, future value is estimated at $34.98, which indicates the stock is trading on a richer footing than those assumptions imply. Which framework do you find more convincing?
For a closer look at how this cash flow view is built, Look into how the SWS DCF model arrives at its fair value.
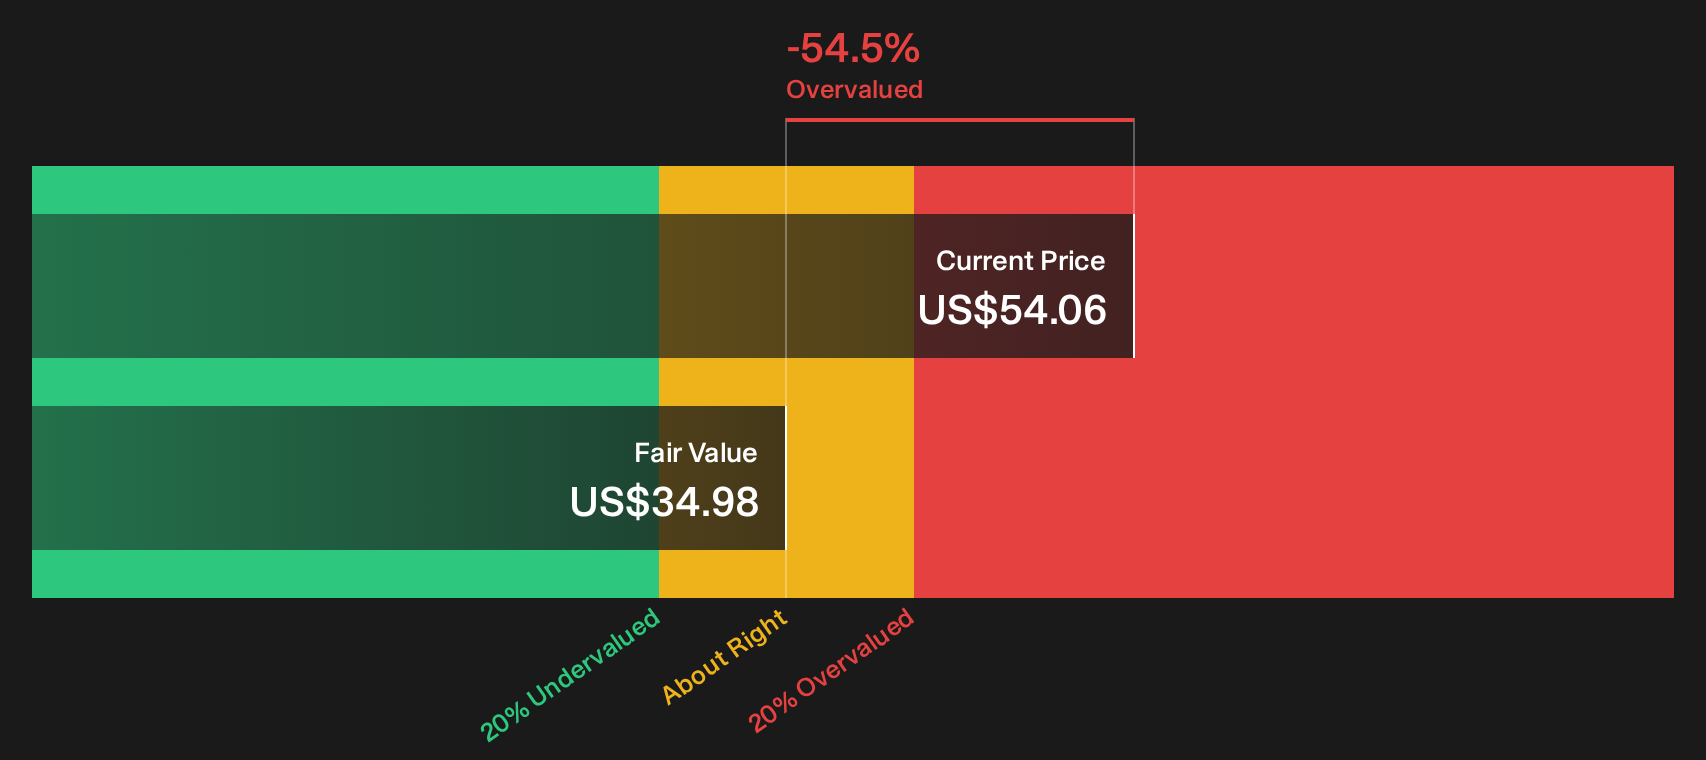
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out DorianG for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around DorianG is mixed and the numbers point in different directions, so consider acting promptly, review the underlying data, and weigh both the potential upside and downside. To see both sides laid out clearly, review 2 key rewards and 3 important warning signs.
Looking for more DorianG investment ideas?
Do not stop with a single LPG specialist when the wider market holds so many different ways to balance risk, income, and potential growth across your portfolio.
Use the Simply Wall St Screener to scan other opportunities that match your style before the next move in shipping, energy, or income-focused plays passes you by.
- Target resilient balance sheets and steady fundamentals by reviewing our curated list of solid balance sheet and fundamentals (25 results). It can help anchor the more cyclical parts of your holdings.
- Hunt for potential mispricing by running through the focused 21 high quality undiscovered gems, where quality financials meet lower market attention.
- Build a cash flow focused income stream with our yield oriented 5 dividend fortresses, which filters for higher payouts with disciplined financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com