


Zymeworks (ZYME) Could Be 32% Undervalued On Fresh ZW191 Phase 1 Data
Zymeworks (ZYME) drew fresh attention after presenting Phase 1 data for ZW191 at ESMO 2026, highlighting anti-tumor activity and manageable tolerability in heavily pretreated patients with platinum-resistant ovarian cancer.
Investors have been reacting to a steady stream of clinical and partnering updates around Zymeworks, with the 7-day share price return of 12.74% and 90-day gain of 23.45% suggesting momentum has picked up recently. At the same time, the 1-year total shareholder return of 59.08% and very large 3-year total shareholder return of over 3x paint the picture of a story that has already rewarded patient holders.
Scan other oncology-focused opportunities that are moving on fresh clinical data with our curated shortlist of 21 high quality undiscovered gems. Like Zymeworks, they pair complex science with ambitious development pipelines.
After a run like this and fresh ZW191 data in the mix, Zymeworks tempts investors who want in now, while others prefer to wait. Does the current price already reflect the story?
Most Popular Narrative: 32% Undervalued
On the most followed view of Zymeworks, a fair value of $41.75 sits well above the recent $28.22 close. This puts the stock in clear discount territory and raises the question of whether the gap reflects risk or opportunity.
The analysts have a consensus price target of $41.75 for Zymeworks based on their expectations of its future earnings growth, profit margins and other risk factors.
However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of $60.0, and the most bearish reporting a price target of just $32.0.
See why 8 investors see Zymeworks as 32% undervalued.
Result: Fair Value of $41.75 (UNDERVALUED)
Still, the story can break if key partners delay regulatory milestones or if Zymeworks has to fund its early pipeline with fresh, dilutive capital.
Find out about the key risks to this Zymeworks narrative.
Another View: What Zymeworks’ P/B Ratio Is Telling You
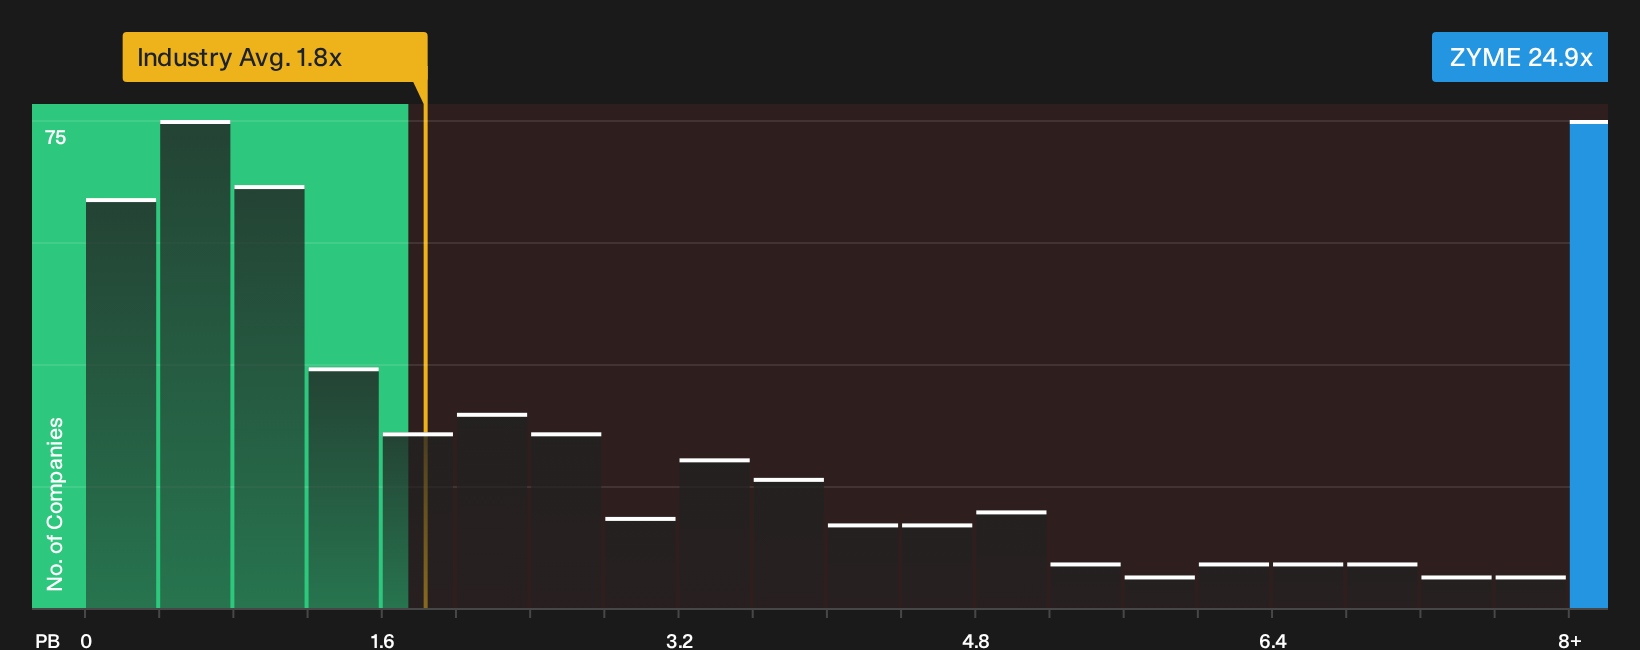
Some analysts describe Zymeworks as undervalued, yet the trading multiples present a tougher picture. The P/B ratio stands at 24.9x, which is significantly higher than both the US Biotechs sector at 1.9x and peer levels around 11x. That kind of gap can indicate that high expectations are already reflected in the current price. If sentiment changes, that premium could compress.
For a closer look at how this valuation compares with peers and what it could mean for risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Does Zymeworks really deserve this kind of optimism, or is sentiment getting ahead of itself? Weigh the data, decide quickly where you stand, and then see how those potential upsides compare in the 2 key rewards
Looking for more Zymeworks-like investment ideas?
Do not stop with Zymeworks. Broaden your watchlist now with focused stock ideas that match your risk profile, cash flow needs, and balance sheet preferences.
- Hunt for potential mispricing by scanning a curated pool of quality candidates in the 27 high quality undervalued stocks.
- Strengthen your income stream by reviewing companies in the 5 dividend fortresses that offer higher yields with clear, data driven support.
- Sleep easier at night by checking companies in the 30 resilient stocks with low risk scores that pair resilience scores with fundamentals you can actually track.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com