


Is Albemarle (ALB) Cheap After A 60% Five Year Drop?
Albemarle has seen its share price fall steeply in recent years, and that drop raises a simple question for investors who care about valuation. Is the current price still in line with what the business is generating in sales, or has the stock moved out of sync with its revenue base?
- The stock is down about 60.2% over the past 5 years, which puts the focus squarely on whether the current valuation can still be explained by its sales profile.
- Recent commentary around Albemarle highlights both its role as a key lithium supplier for energy storage and the operational strain of idling the Kemerton processing facility. Together, these factors can shape expectations for future revenue and capital needs.
- Your read on Albemarle is one view; the desks covering it have another. See what analysts think Albemarle's shares could be worth.
The issue now is whether Albemarle's latest share price truly lines up with what investors are paying for each dollar of its sales.
If you want to pressure test how Albemarle's valuation compares with other materials and energy names tied to electrification themes, scan the 32 best rare earth metal stocks.
Is Albemarle Getting Expensive on Sales?
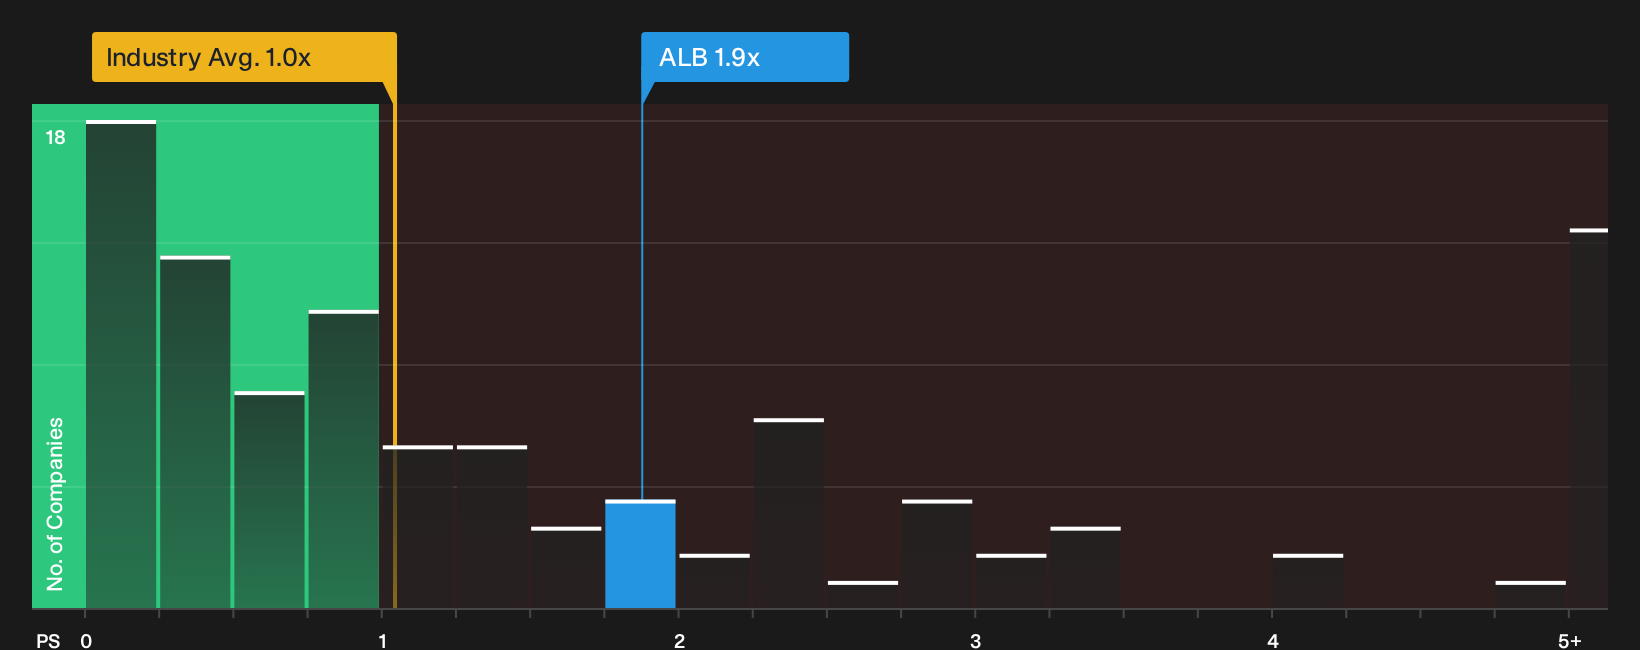
P/S is a useful lens for Albemarle because lithium pricing and volumes can swing earnings more than revenue. On that measure, the stock trades on a P/S of about 1.9x, which is above the broader chemicals sector at roughly 1.0x but below the peer group around 2.3x. That mix suggests investors are paying more for each dollar of Albemarle sales than for the average chemicals business, yet not as much as for closer lithium and electrification plays.
The Fair Ratio model, which adjusts for Albemarle's growth profile, profitability, size and risk, points to a lower P/S than where the shares currently change hands. That gap screens as overvalued on this framework. Because recent broker upgrades have highlighted strong lithium demand and Albemarle's position in US supply, the premium to Fair Ratio implies investors already price in a fair amount of that story. To decide if that mark up is acceptable, you would need to judge how durable Albemarle's lithium contracts and processing footprint look across the cycle. Explore the numbers behind Albemarle's P/S valuation.
The Albemarle Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this Albemarle valuation puzzle leaves off. The tool spells out which combinations of future growth, margins and earnings would need to unfold for the stock to look meaningfully cheaper or richer than today’s price on the Community page. Each scenario ties a fair value estimate to a clear storyline about Albemarle's potential catalysts and key risks so you can track which path reality starts to resemble over time.
One of the top community narratives on Albemarle: 41% undervalued
"With approximately 50% of sales volumes locked under long-term agreements with major Western OEM and battery customers, Albemarle benefits from enhanced revenue stability…"
Discover why this Narrative puts Albemarle at 41% undervalued.
Before acting on Albemarle's valuation, one more factor deserves a closer look
Numbers tell you what Albemarle is worth today, but the people deciding capital allocation, risk appetite and long term priorities, and how they are rewarded for those choices, can heavily influence what happens next. See who runs Albemarle and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com