


Bolloré (ENXTPA:BOL) Revenue Jumps As Bluebus Ends, Is The Stock Above Fair Value?
Bolloré (ENXTPA:BOL) has moved back into focus after reporting third quarter 2026 group revenue of €937 million, compared with €630 million a year ago, alongside a decision to stop producing Bluebus electric buses.
Despite today's revenue headline, Bolloré’s 1-day share price return of 1.05% comes after a year-to-date share price decline of 23.04%. At the same time, the 1-year total shareholder return of 4.59% hints that dividends have softened the impact of weaker recent momentum.
Scan how Bolloré compares with other potential rebound stories in the energy and infrastructure space by reviewing the hand picked 192 high quality undervalued stocks list.
So is Bolloré now a contrarian value idea built on cash returns and a refocused battery business, or a value trap tied to fossil fuels and shrinking Bluebus? Which case does the current valuation lean toward?
Price-to-Earnings of 43.9x: Is it justified?
Bolloré closed at €3.67, and the share is trading on a P/E of 43.9x, which looks steep when set against both its peers and its own fundamentals.
The P/E ratio links the current share price to earnings per share. For a group like Bolloré, with activities in energy, media and industrial battery applications, this metric reflects how much investors are paying today for each euro of current profit.
With annual revenue of €3,022.7m and net income of €235.0m, the 43.9x P/E suggests the market is placing a high value on these earnings. At the same time, recent signals are mixed, since net profit margins currently sit at 7.8% compared with 14.3% a year earlier and Return on Equity of 1.1% is described as low.
The comparison with the wider European Oil and Gas group is stark. Bolloré’s P/E of 43.9x is more than three times the industry average of 13.8x, and also much higher than the peer average of 16.2x. It also sits above the estimated fair P/E of 17.4x that our models suggest the market could eventually gravitate toward if sentiment normalises.
Explore the SWS fair ratio for Bolloré.
Result: Price-to-Earnings of 43.9x (OVERVALUED)
Still, the Bluebus shutdown and a revenue growth rate that currently shows a slight decline of 0.4% each year could pressure the Bolloré rerating story.
Find out about the key risks to this Bolloré narrative.
Another View: What The DCF Says About Bolloré
The P/E points to an expensive Bolloré, and the SWS DCF model tells a similar story in a different way. On that framework, the share price of €3.67 sits above an estimated future cash flow value of €2.61, which implies limited downside protection if sentiment turns.
For readers who want to see how sensitive that outcome is to the assumptions used, Look into how the SWS DCF model arrives at its fair value.
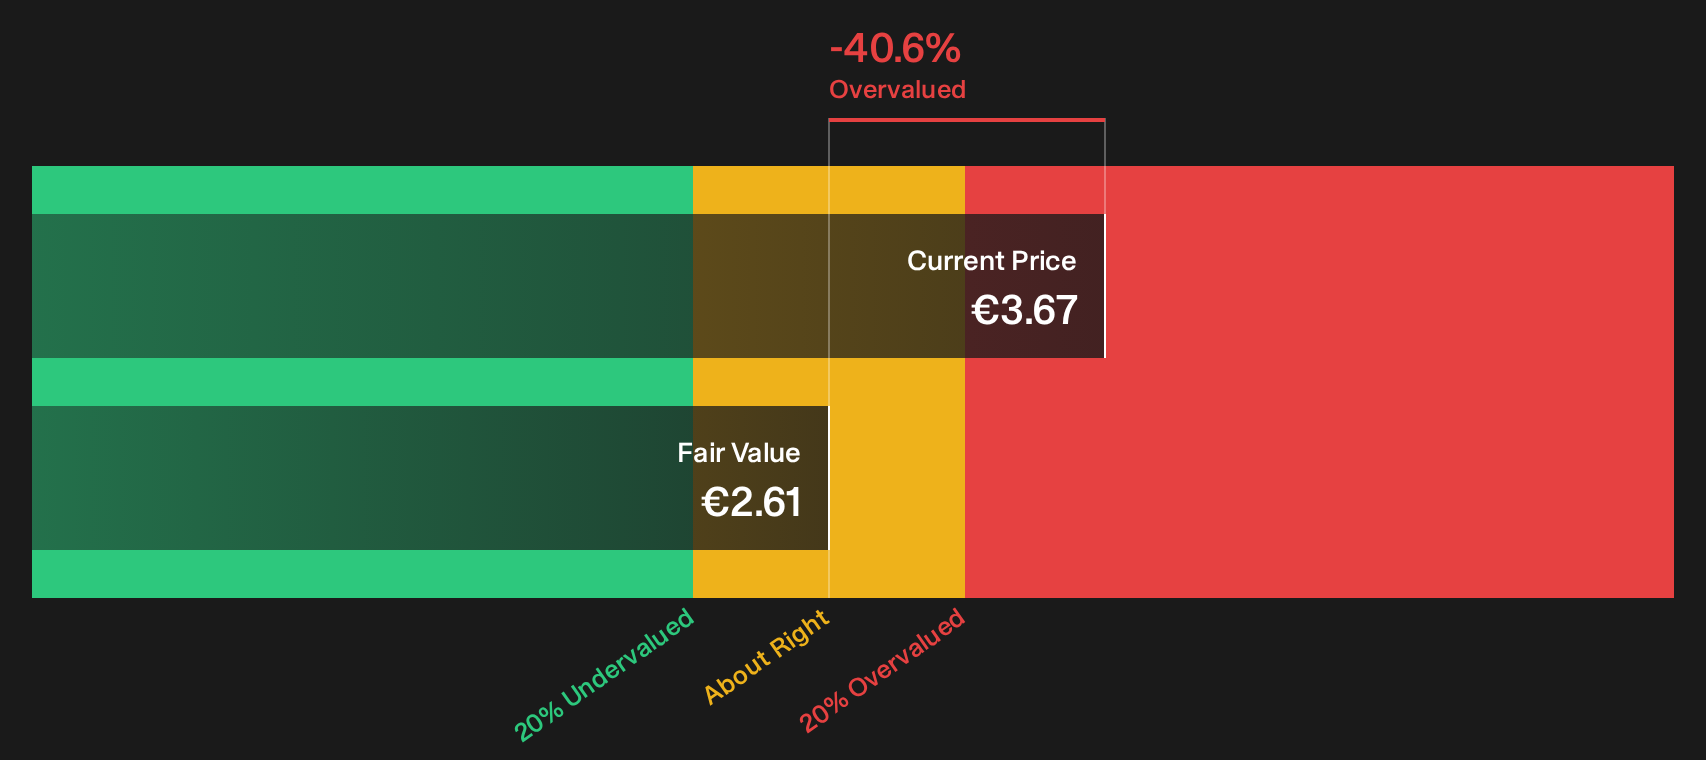
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Bolloré for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 192 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages so far from Bolloré, right. If you want to move quickly and firm up your own view, start with the 1 key reward and 2 important warning signs.
Looking for more Bolloré sized investment ideas?
If you want fresh angles beyond Bolloré, use the Simply Wall Street Screener to look for clear stories, cleaner balance sheets, and different risk profiles.
- For stability seekers who want consistent income, review a curated group of potential income payers in the 226 dividend fortresses.
- Focus on financial strength and aim to reduce unpleasant surprises by using a list of solid balance sheet and fundamentals (204 results).
- Look for opportunities that may be receiving less attention by scanning the 615 high quality undiscovered gems before they gain wider interest.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com