


Learn Why The Bull Case For DocuSign Stock Could Change Following Salesforce AI Integration
- On 13 October 2026, DocuSign, Inc. announced an expanded partnership with Salesforce to embed its Intelligent Agreement Management platform directly into Salesforce, Agentforce, and Slack, allowing revenue, legal, and contract teams to handle the full agreement lifecycle without leaving their existing tools.
- The deeper integration makes DocuSign a key agreement layer for AI agents inside Salesforce and Slack, which could influence how effectively large customers tie contract data, renewal insights, and risk checks into everyday workflows at scale.
- We will now look at how DocuSign's investment narrative could be affected by this deeper AI powered integration into Salesforce workflows.
DocuSign Investment Narrative Recap
To own DocuSign, you need to believe that Intelligent Agreement Management and eSignature stay essential to how large customers run contracts, and that AI heavy workflows keep pulling more agreement volume into the platform. The Salesforce, Agentforce, and Slack expansion sits right on that thesis, but it does not instantly change the current reality of high single digit revenue growth and cautious guidance.
The sharper near term swing factor still looks like whether IAM keeps gaining share of ARR without eroding DocuSign's strong non GAAP operating margins, especially while cloud migration weighs on gross margin. The biggest risk remains that large enterprise and international deals do not ramp as expected, which would leave ARR and billings trailing what many holders are hoping for.
The most relevant prior development here is DocuSign's broader ecosystem push, including deeper Salesforce ties already flagged as a key growth lever. That earlier framing helps explain why this native IAM rollout into Salesforce, Agentforce, and Slack matters operationally. It lines up with the idea that integrated workflows can influence deal sizes and retention rather than relying on standalone eSignature wins.
For you as an investor, the central question is how effectively DocuSign turns those embedded agents into measurable agreement volume, IAM adoption, and renewal visibility, while keeping cloud migration and hosting costs in check. Execution on ecosystem centric expansion, along with maintaining non GAAP operating margins above 30% and solid free cash flow, remains central to the current catalyst story and to how much risk you are comfortable taking here.
What The Salesforce Integration Means For DocuSign's Numbers
DocuSign's Salesforce, Agentforce, and Slack tie up plugs directly into a set of expectations that analysts have already quantified. The story is not just about smoother agreement workflows inside CRM screens. It is linked to forecasts for how fast revenue could grow, how profit margins might evolve, and what level of earnings could support the current stock price and analyst targets.
Analysts are building their models on the view that DocuSign's top line can grow at 7.9% a year over the next three years. That assumption sits alongside a projected lift in profit margins from 9.8% today to 14.8% over the same period. In simple terms, the models are pairing mid single digit to high single digit revenue expansion with a meaningful improvement in profitability as Intelligent Agreement Management and AI infused products spread across the customer base.
Earnings expectations are more specific. Consensus points to profit of US$624.4 million by about 2029, compared with US$329.9 million today and a more optimistic camp that models up to US$700.9 million. That step up would require earnings to rise by roughly US$294.5 million over the period just to reach the central forecast. For you, the important takeaway is that these figures already assume DocuSign converts its agreement data, IAM usage, and large customer integrations into much higher profit dollars than today.
Valuation assumptions tie these operating forecasts back to what you see on screen in your brokerage account. To line up with the analyst price targets, the projections imply DocuSign would be earning that US$624.4 million in 2029 on revenues of US$4.2b while trading on a P/E multiple of 21.8x. That would be down from a current P/E of 42.6x and below the present US Software industry P/E of 30.7x. This tells you the consensus case leans on earnings growth and margin progress more than on investors paying a richer multiple in future.
DocuSign's narrative projects US$4.2b revenue and US$624.4 million earnings by 2029. This rests on 7.9% yearly revenue growth and an earnings increase of about US$294.5 million from US$329.9 million today.
Analyst targets also bake in capital allocation choices. The forecast calls for shares outstanding to shrink by about 6.68% a year over the next three years, which would mechanically lift earnings per share if profit dollars move in line with expectations. Buybacks, in that setup, are not just returning cash. They are part of how the per share earnings math gets to US$2.91 by 2029 on those consensus earnings, assuming the business hits the projected profit pool.
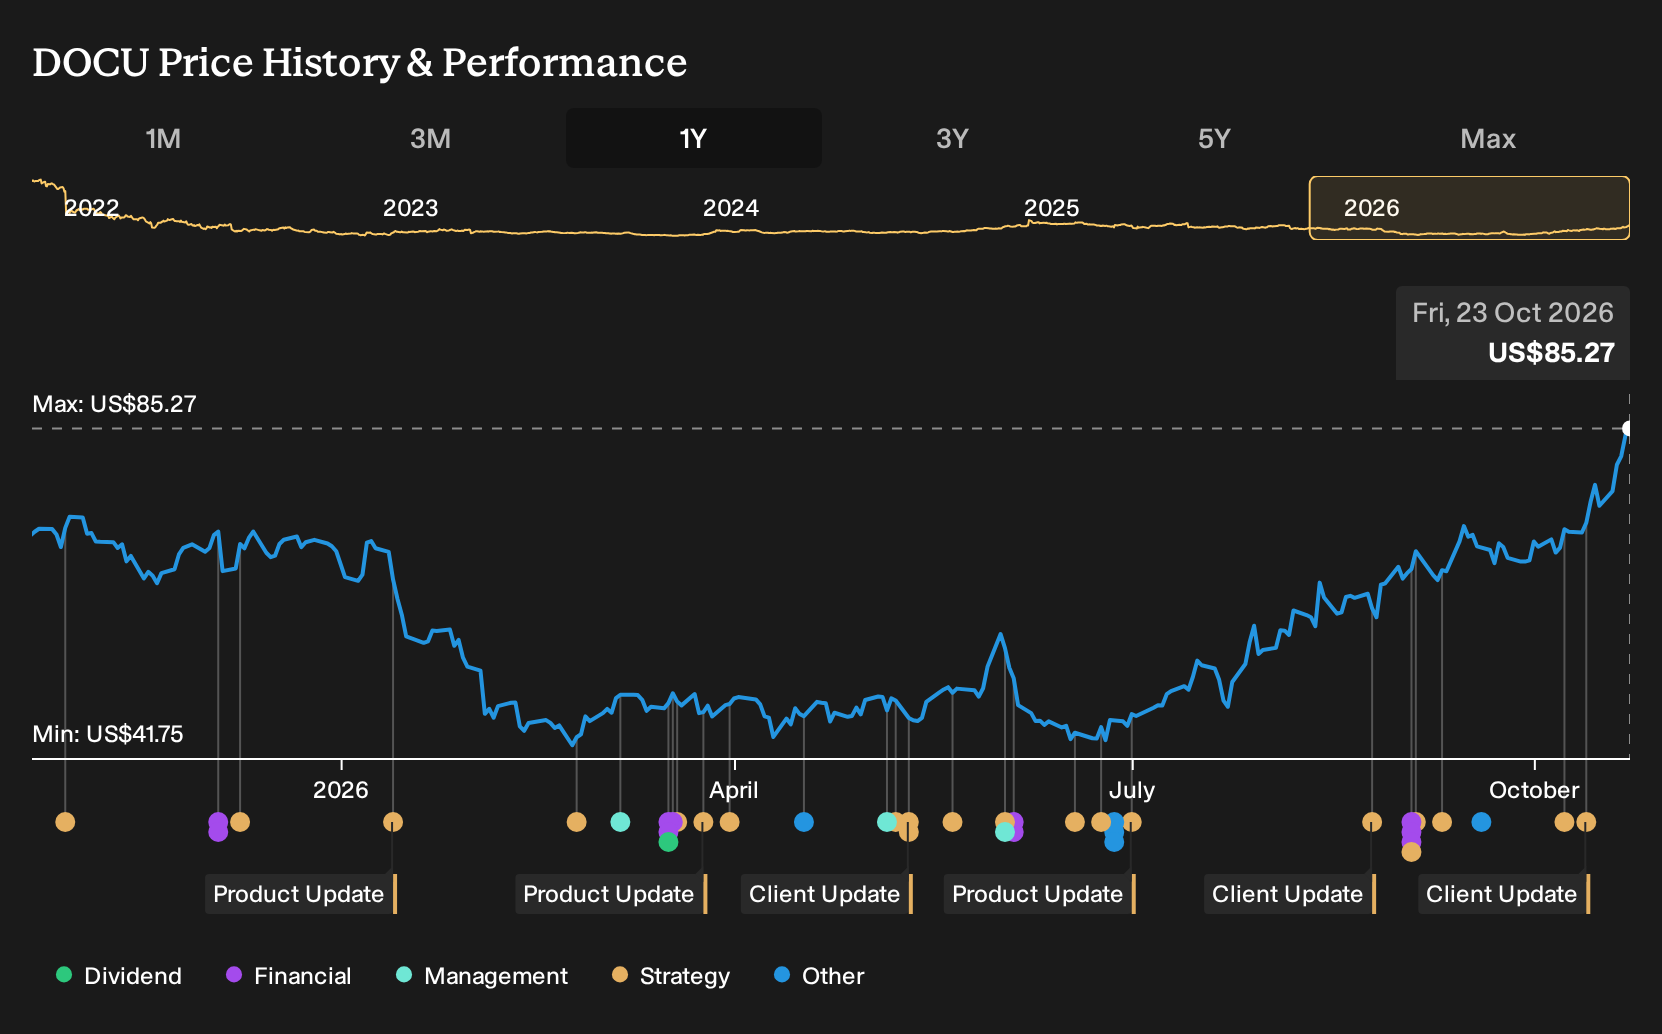
The price targets themselves are fairly tight around the current quote. On a share price of US$75.23, the average analyst target of US$69.99 sits about 7.5% lower, with a range from US$46.89 at the low end to US$86.00 at the top. That distribution suggests the market already reflects a lot of the IAM and AI workflow promise in DocuSign, while still leaving room for different views on how much agreement volume and margin uplift the Salesforce integration and broader ecosystem push can actually deliver.
Uncover why DocuSign's fair value indicates an 18% potential downside to its current price that leaves little room for error.
Exploring Other Perspectives
One alternate angle you might consider is the risk that DocuSign’s deep Salesforce integration still leaves most usage stuck in lower priced eSignature. The most bearish analysts were already modelling revenue growth of only 6.7% a year and earnings of about US$567.7 million by 2029 before this news. This shows how sharply expectations can differ and why it helps to study several narratives before deciding how this update could reshape your own view.
Explore 6 other DocuSign fair value estimates, including one that suggests as much as 38% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your DocuSign research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for DocuSign. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate DocuSign's overall financial health at a glance.
Looking For More Ideas Beyond DocuSign?
If this DocuSign update has sharpened your thinking about AI workflows and agreement software, it can help to compare it with other opportunities that match your preferred mix of quality, value, and resilience. The Simply Wall St Screener gives you a quick way to line up different businesses against the same yardstick so you can pressure test your thesis instead of relying on a single stock story.
- If you want resilient businesses that aim to keep risk in check, start with a set of 30 resilient stocks with low risk scores that may better fit a capital preservation mindset.
- If value is your focus, you can line up potential bargains by scanning our curated 27 high quality undervalued stocks that pair solid fundamentals with more modest pricing.
- If balance sheet strength matters most to you, you can zero in on companies from our list of solid balance sheet and fundamentals (25 results) where financial footing takes center stage in your comparison.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com