


How HPV Testing Expansion At Labcorp Has Changed Its Investment Story
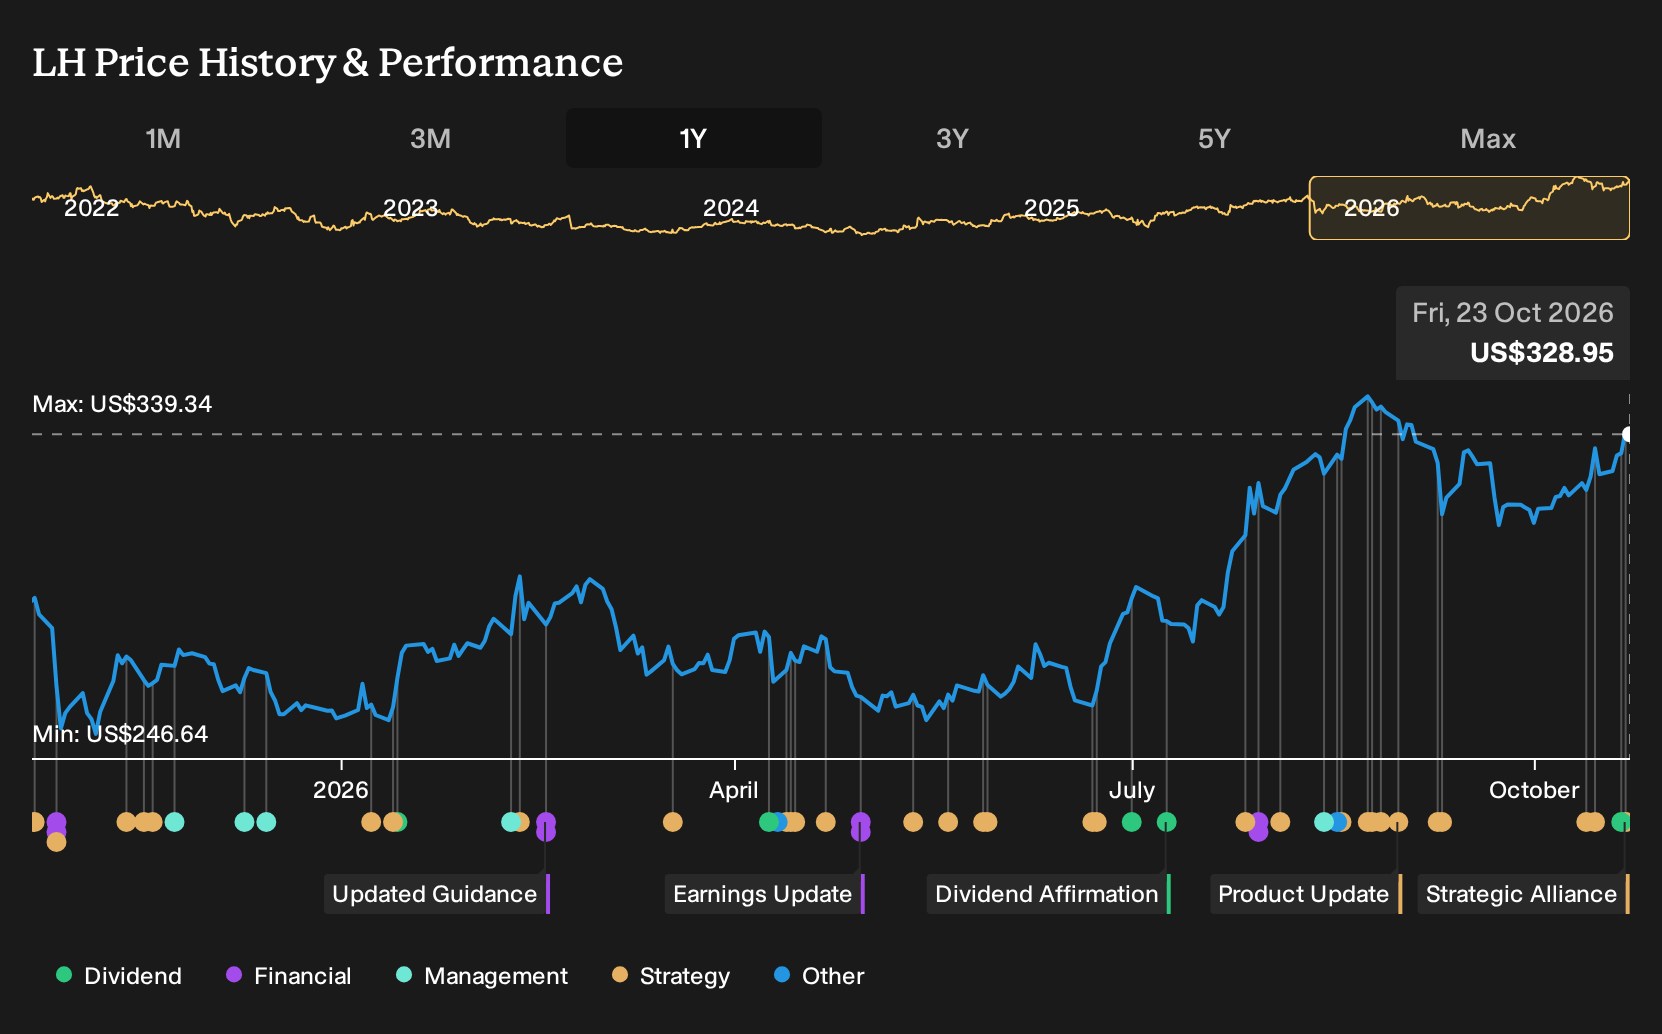
- Labcorp Holdings announced several October agreements, including a nationwide rollout of the FDA approved BD Onclarity HPV Assay by late 2026 and a collaboration with the FDA and Charles River Laboratories to refine how medicine abuse potential is assessed.
- Together with the new Thrive 5 Health Test launch, these moves indicate that Labcorp Holdings is focusing more on higher complexity diagnostics and consumer facing health programs that can influence mix, utilization of its lab network and future capital allocation priorities.
- This article examines how Labcorp Holdings' investment narrative is affected by its FDA abuse potential collaboration and HPV testing expansion.
Labcorp Holdings Investment Narrative Recap
To own Labcorp Holdings, you need to believe the diagnostics and biopharma lab model can keep shifting toward higher complexity testing, durable pharma contracts and more direct consumer touchpoints. The current story leans on multi year efficiency programs, acquisitions and specialty test mix to support margins, while reimbursement and regulation, including potential PAMA cuts, lean the other way.
In the near term, the key swing factor is whether core diagnostics volumes and central lab backlog execution stay solid enough to keep earnings momentum after a strong 12 month profit recovery. The main risk is that reimbursement pressure or softer demand leaves the company short of its 2029 revenue and margin ambitions.
The BD Onclarity HPV Assay rollout looks most relevant because it speaks directly to Labcorp Holdings’ women’s health and higher value test mix effort. Extended HPV genotyping, tied into clinician programs, Gaps in Care initiatives and the Labcorp OnDemand and MyLabcorp channels, pushes more complex screening into existing collection and digital platforms.
If execution is smooth, this assay can influence test mix and use of the nationwide lab network without relying on large volume gains. Operationally, investors will likely watch adoption by health plans and clinicians, integration into risk based cervical cancer screening workflows and any impact on how resilient the diagnostics segment looks against reimbursement headwinds.
Labcorp Holdings' current analyst narrative points to revenues of US$16.6b and earnings of US$1.4b by 2029, based on an assumed 5.0% yearly revenue growth rate and an earnings increase of US$0.4b from US$1.0b today.
Uncover why Labcorp Holdings' fair value indicates a 5% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
The Simply Wall St Community currently has only two fair value estimates for Labcorp Holdings, clustered tightly between about US$326 and US$344 per share, which signals very concentrated opinions. Those views sit beside clear swing factors. PAMA cuts, execution on abuse potential studies and the HPV assay rollout could all reshape how you judge future resilience. Investor opinions can differ widely, so explore several of these community viewpoints before deciding how this story fits your own expectations.
Explore another Labcorp Holdings fair value estimate, including one that suggests it could be worth just $326.00.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis.
- A great starting point for your Labcorp Holdings research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Labcorp Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Labcorp Holdings' overall financial health at a glance.
Looking For More Ideas Beyond Labcorp Holdings?
Once you have a view on Labcorp Holdings, it can help to compare it with other opportunities that fit clear, rule based criteria. The Simply Wall St Screener gives you a way to scan wider without losing discipline around fundamentals, balance sheet strength or risk profile.
- If you care most about durable balance sheets and straightforward fundamentals, start with this list of solid balance sheet and fundamentals (25 results) that keeps financial resilience front and center.
- When value is the priority, run a wider search across companies trading below their estimated worth using the 27 high quality undervalued stocks to spot potential mispricings.
- If capital preservation comes first, focus on stability and risk controls by checking the 30 resilient stocks with low risk scores that filters for historically resilient businesses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com