


Walker & Dunlop (WD) Arranges SoHo Bridge Loan, Is The 29% Undervalued Case Enough?
Walker & Dunlop (WD) just arranged a US$216 million bridge loan to refinance 568 Broadway, a mixed-use SoHo property. This transaction puts its capital markets expertise front and center for anyone tracking the stock.
For context, Walker & Dunlop’s 1-day share price return declined 1.5%, the 30-day share price return is down 7.6%, and the 90-day share price return has fallen 29.1%. Meanwhile, the 1-year total shareholder return is down 57.9%, which points to fading momentum despite this SoHo refinancing win grabbing fresh attention.
Compare Walker & Dunlop’s SoHo refinancing move with other real estate finance players by scanning our curated list of solid balance sheet and fundamentals (25 results) for potential alternatives in the same space.
Bulls see Walker & Dunlop’s SoHo deal as proof the franchise still commands marquee mandates. Bears point to the long share price slide and low value score. Which story does the valuation support next?
Most Popular Narrative: 29% Undervalued
Walker & Dunlop’s most followed narrative pegs fair value at about $48.33 a share, compared with the latest close near $34.16. That gap puts the focus on whether refinancing fees, equity deployment, and capital markets reach can justify the implied upside under that storyline.
Ongoing refinancing and construction activity in a higher rate setting, including recent large multifamily, mixed use, office and workforce housing deals in Miami, Manhattan, Jersey City and other markets, keeps Walker & Dunlop well positioned to generate fee income from a sustained recapitalization cycle that can support revenue and earnings.
See why 1 investors see Walker & Dunlop as 29% undervalued.
Result: Fair Value of $48.33 (UNDERVALUED)
Still, if high financing costs keep weighing on commercial real estate volumes or Walker & Dunlop misjudges complex projects, the 29% undervaluation thesis can quickly fray.
Find out about the key risks to this Walker & Dunlop narrative.
Another Take On Walker & Dunlop’s Valuation
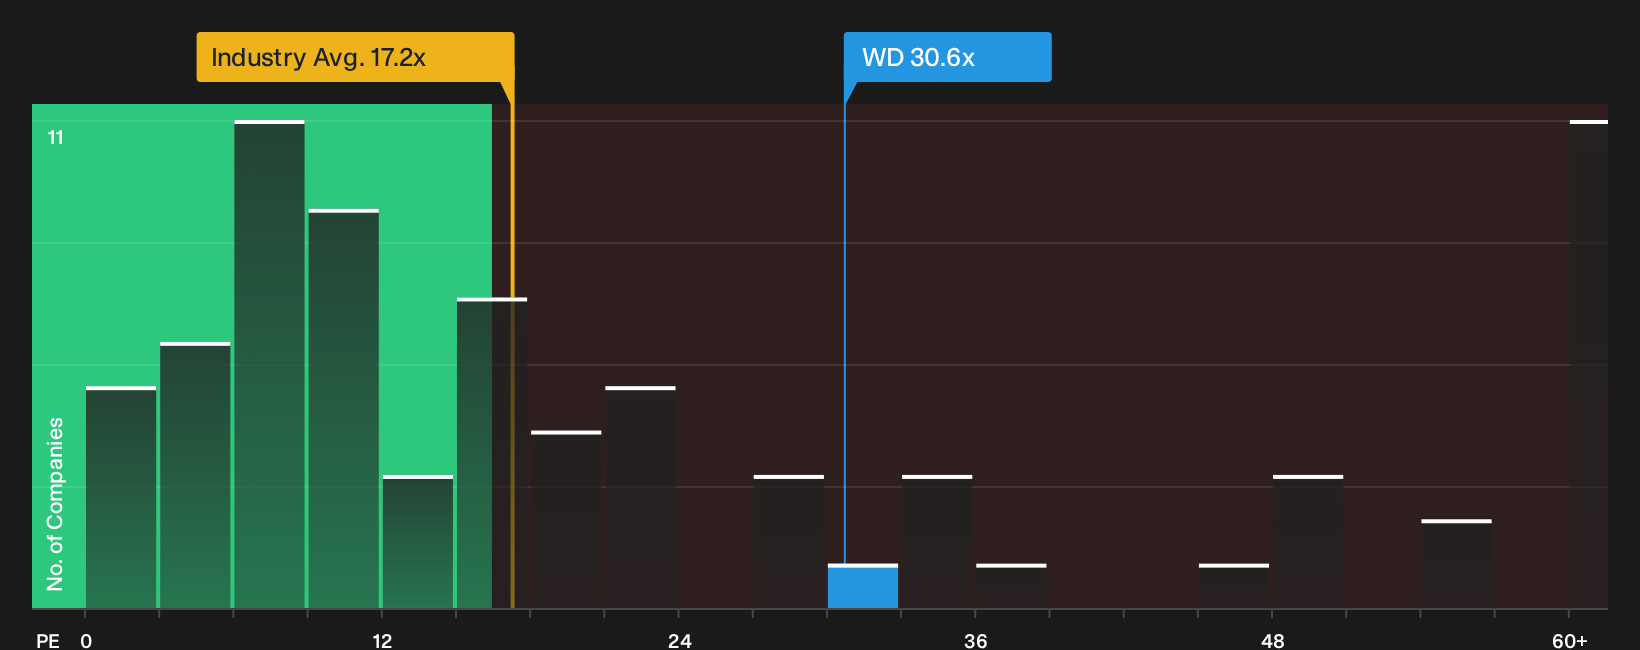
The story changes once you stop looking at fair value per share and focus on what the current P/E implies. Walker & Dunlop trades on a P/E of 30.6x, while peers average 10.2x and the fair ratio points to 19x. That gap raises a simple question for investors: is this premium really the side of the debate you want to lean on?
To see what the numbers say about this price in practical terms, have a look at our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around Walker & Dunlop’s story are clear, with both pressure and promise in play. Move fast, review the data, and weigh the 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Walker & Dunlop?
You do not need to stop at Walker & Dunlop. Broaden your watchlist with focused ideas that match your risk profile, income goals, and return expectations.
- Target potential turnaround stories by scanning carefully selected smaller opportunities through 7 elite penny stocks with strong financials that pair higher risk with focused financial filters.
- Zero in on value candidates by using the curated 27 high quality undervalued stocks that highlights companies combining solid fundamentals with prices below their assessed worth.
- Build a steadier income stream by reviewing dividend-focused picks in the 5 dividend fortresses that filters for higher yields backed by stronger balance sheets.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com