


China Hongqiao Group (SEHK:1378) Could Be 71% Below Fair Value Following Profit Rebound
China Hongqiao Group (SEHK:1378) is back in focus after key subsidiary Shandong Hongqiao Aluminum reported 13.67% operating revenue growth and a 69.86% jump in net profit, alongside a sharply improved core profit profile.
Despite the upbeat subsidiary figures, China Hongqiao Group’s share price tells a different short term story. The HK$19.02 quote comes after a 1 month share price return that is down 10.7% and a year to date share price decline of 44.09%, while the 5 year total shareholder return of 241.17% still points to a very strong longer run outcome.
Capitalize on the renewed interest around China Hongqiao Group by scanning a curated set of aluminum and materials peers that currently screen as 192 high quality undervalued stocks.China Hongqiao Group now trades at a steep discount to both intrinsic estimates and analyst targets after a sharp year to date slide. Is the market rightly cautious, or mispricing the recent profit rebound and value signals?
Preferred P/E of 5.8x: Is it justified?
On valuation, China Hongqiao Group screens as inexpensive on earnings. The stock trades at a P/E of 5.8x while our fair P/E estimate sits at 9.1x, and the last close of HK$19.02 also reflects a wider discount to both intrinsic and analyst valuation markers already discussed.
The P/E ratio compares the current share price with earnings per share, so it gives you a quick sense of what investors are paying for each unit of profit. For a large aluminum producer with HK$168,820.53m in annual revenue and HK$27,485.37m in net income, this kind of earnings based gauge is a central reference point for many investors in heavy industry and materials.
China Hongqiao Group also screens as good value versus peers, with its 5.8x P/E well below the Hong Kong Metals and Mining industry average of 8.4x and far below the peer average of 33.3x cited in the checks. The gap to the 9.1x fair P/E level is wide. This indicates that the market is currently assigning a materially lower earnings multiple than the regression based fair ratio that our process identifies as a reference level.
Explore the SWS fair ratio for China Hongqiao Group.
Result: Price-to-Earnings of 5.8x (UNDERVALUED)
Still, China Hongqiao Group faces clear risks, including exposure to cyclical aluminum demand and heavy reliance on revenue from the PRC market.
Find out about the key risks to this China Hongqiao Group narrative.
Another view on China Hongqiao Group's value
The earnings multiple points to a cheap stock, yet the SWS DCF model presents a different perspective. At HK$19.02, China Hongqiao Group is described as trading below an estimated future cash flow value of HK$65.46, which also screens as undervalued on that framework.
For anyone weighing which signal to rely on, the question is straightforward. Are cash flow assumptions or earnings multiples giving the clearer read on risk today, and which approach fits your own process.
Look into how the SWS DCF model arrives at its fair value.
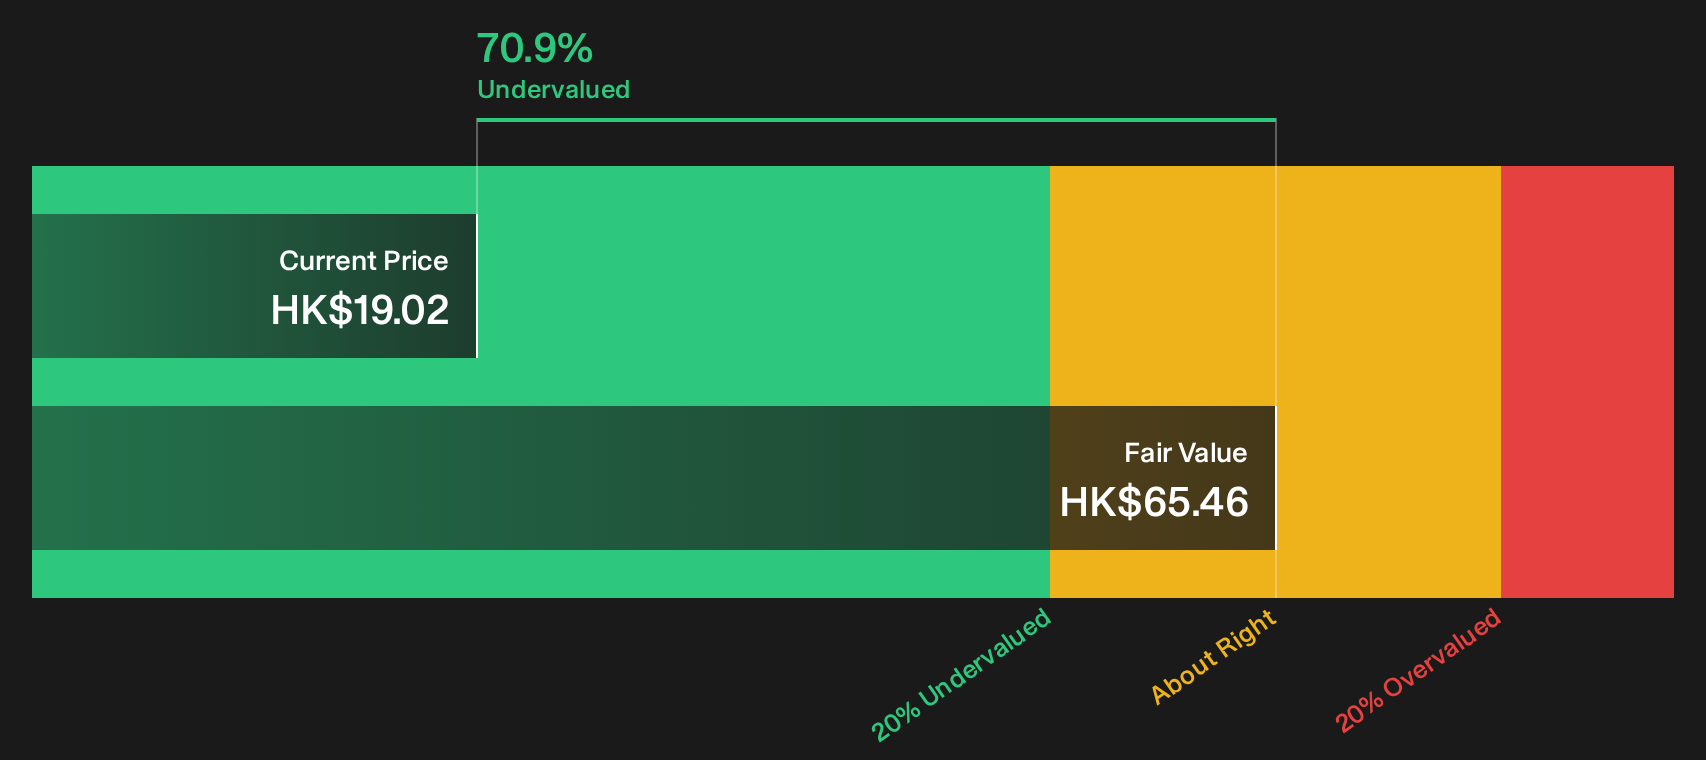
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out China Hongqiao Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 192 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around China Hongqiao Group often create as many questions as answers, so move quickly, review the underlying data, and weigh both sides of the story using the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond China Hongqiao Group?
If China Hongqiao Group has your attention, do not stop there. Broaden your watchlist so you are not relying on a single opportunity.
- Tap into potential income resilience by scanning a hand picked pool of high yield candidates through the 226 dividend fortresses.
- Hunt for quality at a discount by filtering companies that currently appear mispriced using the 192 high quality undervalued stocks.
- Prioritize capital protection by focusing on businesses that show healthier finances via the list of solid balance sheet and fundamentals (204 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com