


Did Earnings Beat Hopes Just Shift Starbucks (SBUX) Stock Narrative?
- Wall Street recently projected that Starbucks could report higher earnings on lower revenue for the quarter ended September 2026, with the Most Accurate Estimate above the broader consensus.
- This mix of expected profit growth and softer sales highlights how the Back to Starbucks efficiency push and cost programs may be doing more work than pure demand.
- Next, the focus turns to how this expected earnings resilience on lower revenue may reshape Starbucks' broader investment narrative.
Scan how Starbucks fits into this earnings resilience theme by lining it up against a hand-picked 27 high quality undervalued stocks that also pair efficiency gains with cautious revenue expectations.
Starbucks Investment Narrative Recap
To own Starbucks, you need to believe the Back to Starbucks plan can turn cost work into healthier margins without leaning on strong revenue growth. The recent expectation of higher earnings on softer sales leans directly into that idea. It suggests current efficiency efforts may be pulling more weight than the top line right now.
The near term catalyst is clear. Investors are watching whether operating margin moves closer to or above levels seen two years ago as cost savings, store remodels, and labor investments work through the system. The largest risk remains store level cost pressure from unionisation, wage increases, and any further legal or regulatory actions.
There have been no fresh company announcements tied directly to this earnings setup, which makes the existing Back to Starbucks commitments even more central to the story. Management is working against a backdrop of lower net profit margins than last year and a global margin that still trails where it was two years ago.
For you, the link is straightforward. Expected earnings resilience on lower revenue puts a spotlight on whether the US$2b cost savings program, store uplift across 8,000 to 9,000 North American locations, and Starbucks Rewards engagement can offset labor, compliance, and debt related pressures. Execution on those projects is what will decide how durable this margin rebuild really is.
Starbucks' narrative projects US$42.8b revenue and US$4.7b earnings by 2029. This assumes 3.7% yearly revenue growth and an earnings increase of US$2.7b from US$2.0b today.
Uncover why Starbucks' fair value indicates an 11% potential upside to its current price that could narrow quickly.
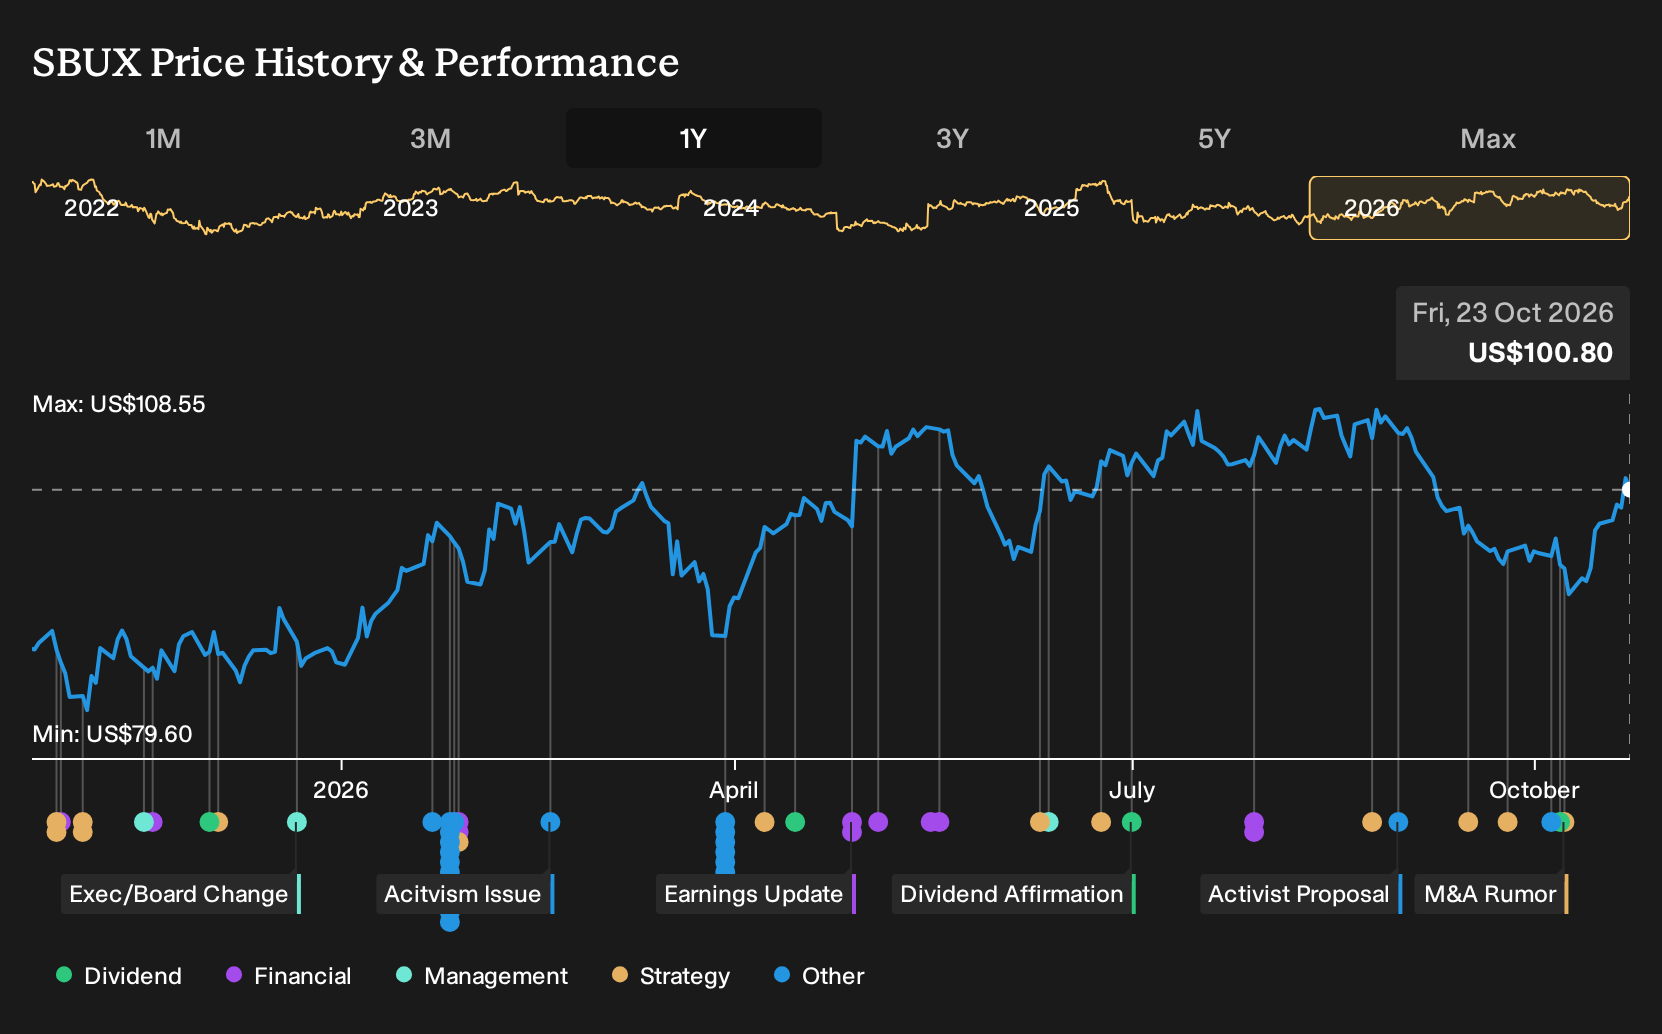
Exploring Other Perspectives
One alternate view on Starbucks leans hard into remodel and restructuring risk. The most cautious analysts were working off revenue of about US$42.5b and earnings of roughly US$4.9b by 2029, with a P/E near 26x. That is a more muted story than consensus, and the latest earnings surprise talk could shift both narratives.
Explore 3 other Starbucks fair value estimates, including one that suggests it could be worth just $100.26.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your Starbucks research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Starbucks. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Starbucks' overall financial health at a glance.
Looking for more Starbucks investment ideas and peers?
If you want to put Starbucks in context, it can help to line it up against other stocks with different strengths, risk levels, and income profiles. The Simply Wall St Screener lets you filter by the traits that matter most to you so you can build a watchlist that matches your investing style.
- For investors who care most about quality at a reasonable entry point, scan a curated set of companies with pricing that looks appealing using our 27 high quality undervalued stocks.
- If capital preservation sits higher on your list than aggressive upside, consider stocks that score well on stability and risk using the 30 resilient stocks with low risk scores.
- When you want resilience built on strong finances, focus on businesses backed by healthier balance sheets using this list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com