


Q3 Results Ahead Could Be A Key Test For Public Storage Stock
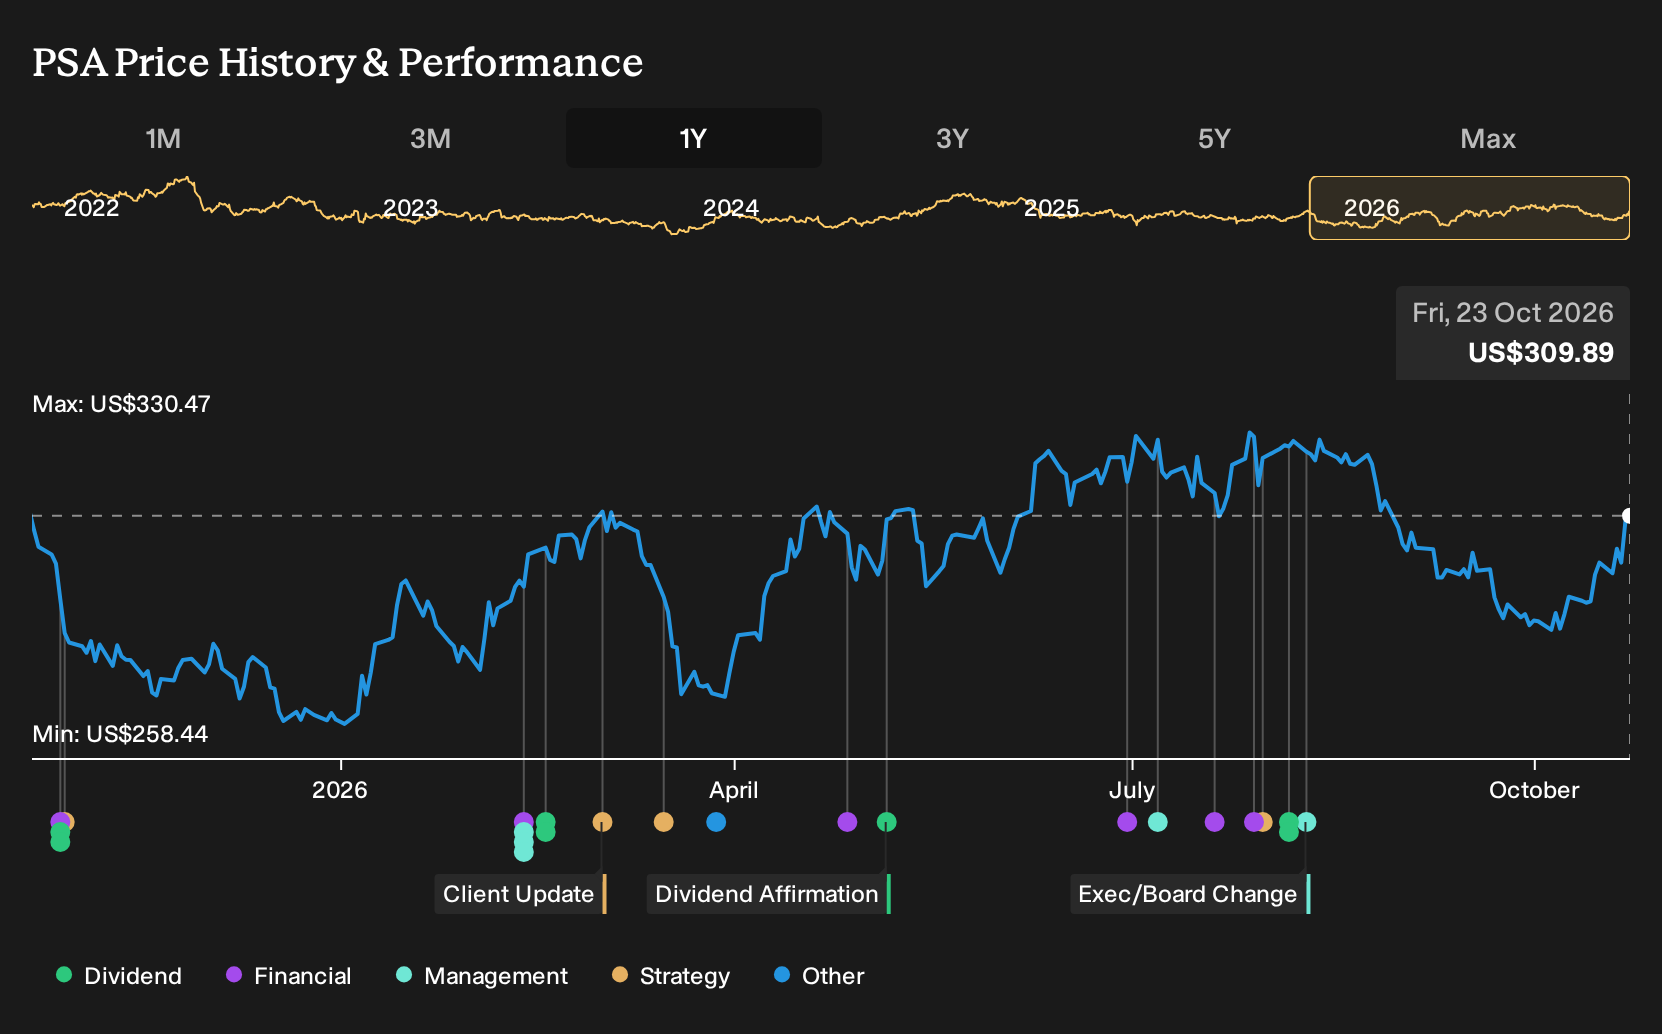
- Public Storage is set to report its third quarter 2026 results on October 26, with management signaling higher revenues alongside softer core funds from operations per share as operating costs and market supply pressures weigh on performance.
- The expiration of Los Angeles County's emergency rental restrictions is a key watchpoint, because it may influence how effectively Public Storage converts demand into rental revenue in one of its most important urban regions.
- We will look at how Public Storage's investment narrative is shaped by anticipated Q3 results and shifting rental restrictions in Los Angeles.
Compare how Public Storage is positioned against other potential income and resilience plays by scanning our hand picked 5 dividend fortresses with similar defensiveness baked into their cash flows.
Public Storage Investment Narrative Recap
To own Public Storage, you need to be comfortable with a large, tech enabled storage platform that leans on urban demand, scale, and efficiencies to keep cash flows relatively steady. The near term story hinges on whether higher Q3 2026 revenues and easing Los Angeles rental restrictions can offset softer core FFO per share and expense pressure.
The biggest swing factor over the next few quarters is same store performance, especially in markets dealing with new supply or tougher comparisons, and how quickly those units absorb demand. The key risk is that operating costs and weaker Sunbelt markets stay sticky, which would pressure margins while the balance sheet is already carrying meaningful debt.
With no fresh corporate announcements tied directly to the Q3 release date, the most relevant reference point remains Public Storage's recent US$3.00 per share total dividend that produced a payout ratio of 1.17. That figure highlights how much of the business case rests on consistent cash generation and disciplined funding decisions.
For income focused holders, this payout profile, combined with management's expectation of improved same store revenue despite cost headwinds, puts execution under a brighter spotlight. Any need to lean harder on external borrowing or equity to sustain distributions would add risk on top of integration work from the National Storage Affiliates and Public Storage Canada deals.
Public Storage's narrative projects US$6.0b revenue and US$2.1b earnings by 2029. This assumes 6.7% yearly revenue growth and an earnings increase of about US$300m from US$1.8b today.
Discover why Public Storage's fair value indicates a 6% potential upside to its current price, a gap that could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$260 to just over US$411, so retail opinions on Public Storage sit wide apart. Read that spread alongside risks such as prolonged Sunbelt softness and integration work on recent acquisitions, which could influence how comfortably the current dividend profile can be maintained. Then explore more Community viewpoints before deciding where you land.
Explore 2 other Public Storage fair value estimates, including one that suggests up to 16% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Public Storage research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Public Storage. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Public Storage's overall financial health at a glance.
Looking For More Investment Ideas Beyond Public Storage?
If you want to stress test your view on Public Storage, set it alongside other income, value, and resilience opportunities using the Simply Wall St Screener. Comparing different businesses on dividends, balance sheet strength, and risk can help you see where Public Storage fits in your wider portfolio.
- For investors focused on quality at a sensible entry point, scan a carefully filtered group of 27 high quality undervalued stocks that pair fundamentals with more modest pricing.
- If capital preservation sits high on your priority list, weigh Public Storage against a 30 resilient stocks with low risk scores to see which businesses line up best with your risk tolerance.
- For those hunting for income ideas with room to grow, line up Public Storage next to a 21 high quality undiscovered gems that combine solid under-the-radar fundamentals with future potential.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com