


Raised Guidance Might Change The Case For Investing In Lockheed Martin Stock (LMT)
- Lockheed Martin reported third quarter 2026 revenue of US$20.71b, higher net income year on year, raised full year 2026 EPS and sales guidance, and highlighted a record US$292b backlog supported by missile programs and a transformative 10 year F-35 production and sustainment framework with the U.S. Department of War.
- The multiyear F-35 framework and new munitions capacity investments give Lockheed Martin unusually long visibility on aircraft demand, sustainment work and missile output, which strengthens the connection between current capacity spending and future contract cash flows.
- We will now look at how Lockheed Martin's updated 2026 earnings guidance and record backlog may influence the longer term investment narrative.
Scan how Lockheed Martin's raised guidance and record backlog compare with other defense contractors by reviewing the hand picked 42 power grid technology and infrastructure stocks tied to critical infrastructure and mission readiness.
Lockheed Martin Investment Narrative Recap
To own Lockheed Martin, you need to believe the business can keep turning a very large, long duration defense backlog into steady sales, earnings and cash generation while managing complex programs and high debt. The raised 2026 EPS guidance to about US$30.35 to US$30.75 and sales outlook of US$80b to US$82b supports that execution story.
The near term swing factor is delivery and cost control on big frameworks in missiles, munitions and the F 35, where performance flows straight into margins. The main risk is still financial or contractual hits on legacy or fixed price programs that could eat into those margins even if demand and backlog stay healthy.
The 10 year F 35 production and sustainment framework is the announcement that ties most directly into this quarter. It outlines about 850 U.S. aircraft plus international orders, a steady 156 jets per year, and 10 years of modification kits and support, which gives Lockheed Martin unusually clear volume and workload planning.
For catalysts, that framework connects the record US$292b backlog to real factory decisions, supplier commitments and future cash conversion. It does not remove risk, since Congress still needs to approve funding and execution on such a large agreement is demanding, but it sharpens the link between today’s capacity investments and tomorrow’s contracted revenue streams.
What The Long Range Forecasts Assume For Lockheed Martin
Lockheed Martin's narrative projects US$91.4b revenue and US$8.4b earnings by 2029. This rests on analysts penciling in 5.9% yearly revenue growth and an earnings increase of about US$2.1b from US$6.3b today.
Uncover how Lockheed Martin's fair value indicates a 3% potential upside to its current price before that discount gap tightens.
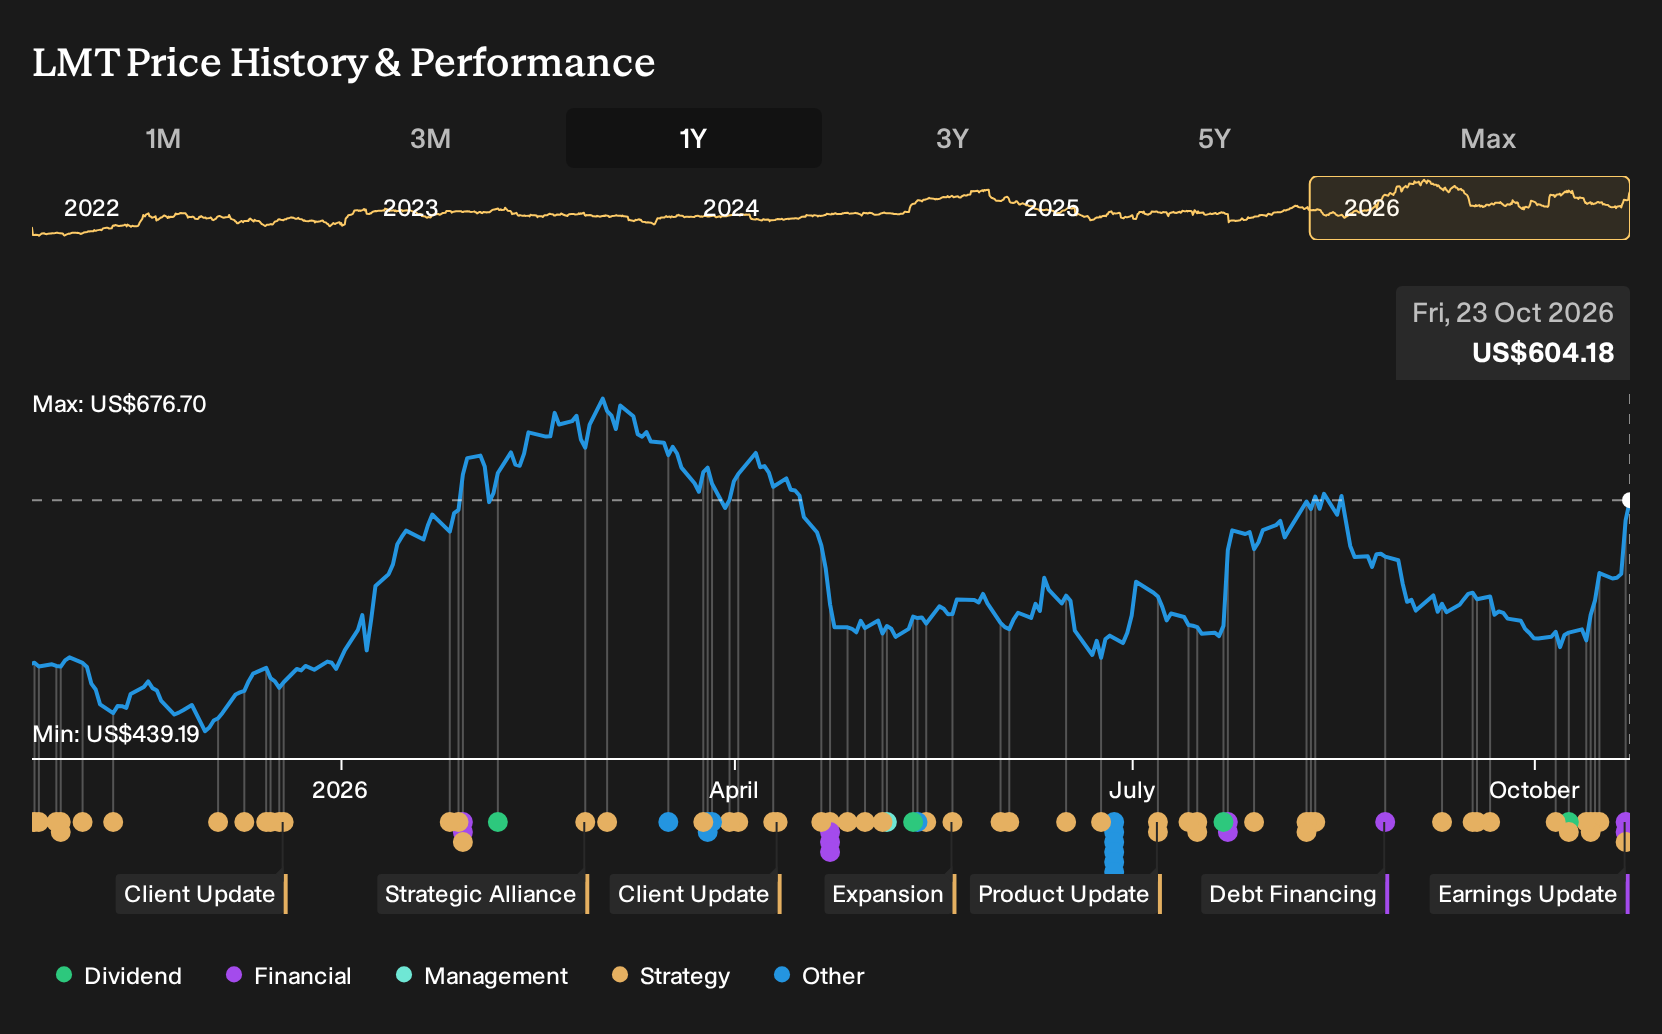
Exploring Other Perspectives
Another angle to watch is capacity risk. The most optimistic analysts were already modeling Lockheed Martin to reach about US$99.7b revenue and US$9.4b earnings by 2029, assuming its big munitions build out runs smoothly. The fresh F 35 framework and raised 2026 guidance may push those expectations even higher. As a result, it makes sense to compare several views before deciding how you feel about the story.
Explore 5 other Lockheed Martin fair value estimates, including one that suggests up to 43% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Lockheed Martin research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Lockheed Martin. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lockheed Martin's overall financial health at a glance.
Looking for more stock ideas beyond Lockheed Martin?
If you want to put Lockheed Martin in context and build a broader watchlist, it helps to scan other opportunities with clear filters for quality, value and risk. The Simply Wall St Screener can help you do that quickly so you can focus on the short list that really deserves your attention.
- If you want companies that combine income with resilience, start with a shortlist of 5 dividend fortresses that may appeal if you prioritise cash returns and durability.
- For readers focused on quality at a reasonable price, scan the 27 high quality undervalued stocks that match strong fundamentals with more modest market expectations.
- If capital preservation matters most to you, narrow your search using a 30 resilient stocks with low risk scores that screens for balance sheet strength and steadier risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com