


BP (LSE:BP.) Lifts Earnings Outlook, Is The Stock Still Only Slightly Undervalued?
BP (LSE:BP.) is back in focus after fresh guidance signalled third quarter 2026 upstream production between 2,190 and 2,240 mboe/d, tightening earlier expectations and sharpening attention on how volumes feed into earnings.
Recent trading has mirrored that story. BP’s share price is up 4.35% over the last day, with a 30-day share price return of 14.59% and a year to date share price gain of 45.81%. The 1-year total shareholder return of 54.38% signals strong momentum building behind the stock as investors react to upgraded earnings expectations, fresh upstream guidance and new project agreements.
Scan for other energy plays showing similar earnings momentum and balance sheet strength by running the 8 high quality undervalued stocks alongside BP on your watchlist.
Bulls argue BP’s production guidance, revised earnings outlook and dividend yield justify the recent surge. Bears see a cyclical spike and thin discount to price targets. Which side do the current valuation numbers support?
Most Popular Narrative: 1% Undervalued
BP is priced very close to its most followed fair value estimate, with the £6.39 last close only slightly below a £6.42 narrative fair value built on detailed cash flow and earnings work at a 7.77% discount rate.
Portfolio high-grading and capital allocation toward higher return oil and gas assets, with over $11b of announced divestments that include Castrol, the Gelsenkirchen refinery and Austria retail, together with impairments to underperforming biogas and renewables projects, is expected to leave BP with a leaner, more profitable asset base that supports future earnings quality and return on capital.
See why 223 investors see BP as 1% undervalued.
Result: Fair Value of £6.42 (UNDERVALUED)
Still, the narrative can unravel if further biogas and renewables impairments drag on returns, or if operating costs stay stubbornly high and dilute BP’s margin story.
Find out about the key risks to this BP narrative.
Another View: BP Through The P/E Lens
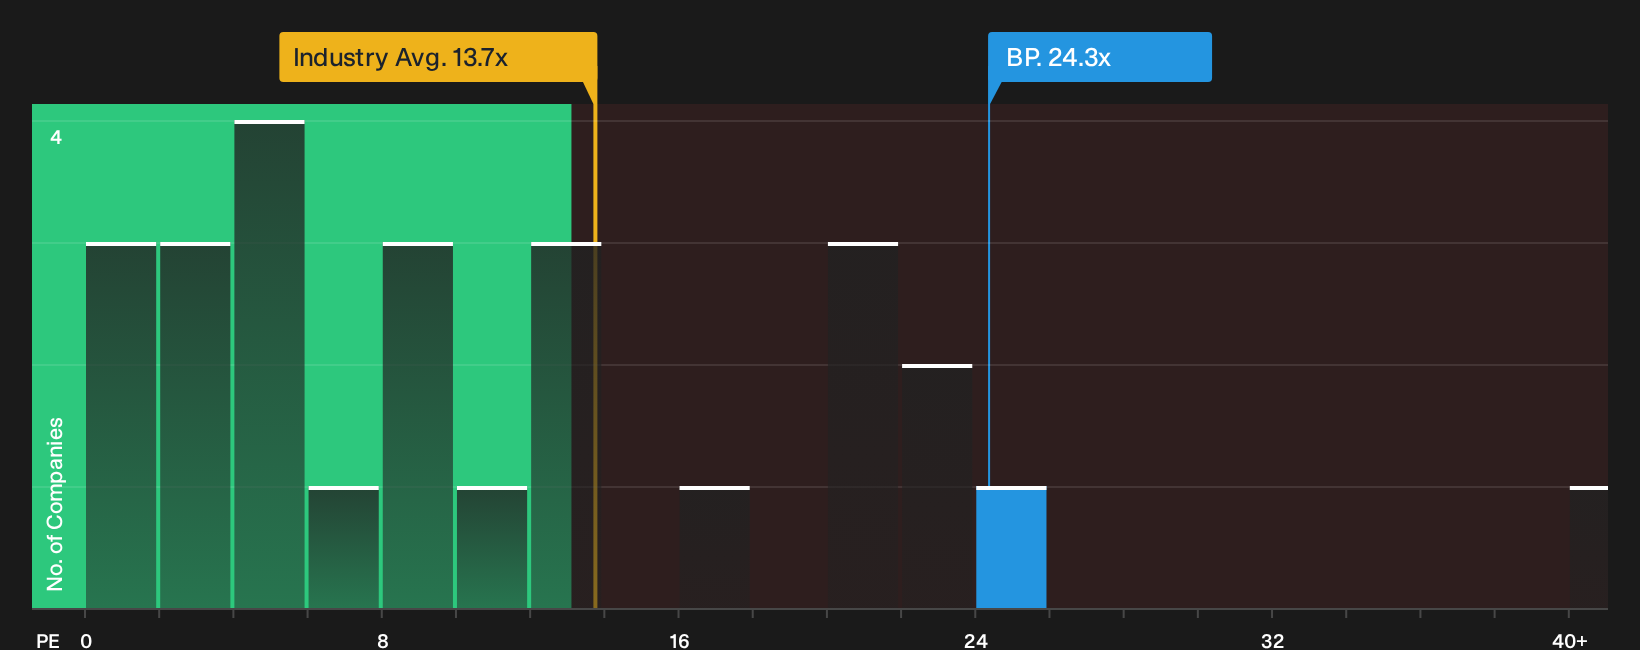
On the cash flow work, BP looks undervalued, yet the P/E story is far less generous. The shares trade on 24.3x earnings compared with 13.7x for the European Oil and Gas group and an 11x peer average, while the fair ratio is 23.7x, which points to thinner upside and more valuation risk if expectations disappoint.
That mix of rich earnings multiple and modest gap to the fair ratio raises a simple question for investors. Is the current price more about a strong recent run than untapped value, or does the market still underappreciate BP’s reset plan enough to keep paying up for it, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around BP is split, with clear risks and clear potential. Pressure test the numbers yourself and then weigh the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond BP?
Do not stop your research with BP. Broaden your watchlist now and give yourself more high quality options the next time markets move fast.
- Target reliable income by scanning for companies that aim to sustain generous payouts with the 5 dividend fortresses.
- Spot robust balance sheets and solid fundamentals before the crowd by checking the list of solid balance sheet and fundamentals (9 results).
- Hunt for under-the-radar opportunities with strong financial profiles using the 5 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com