


Did Dividend Strength Just Shift Kimco Realty (KIM) Investment Narrative?
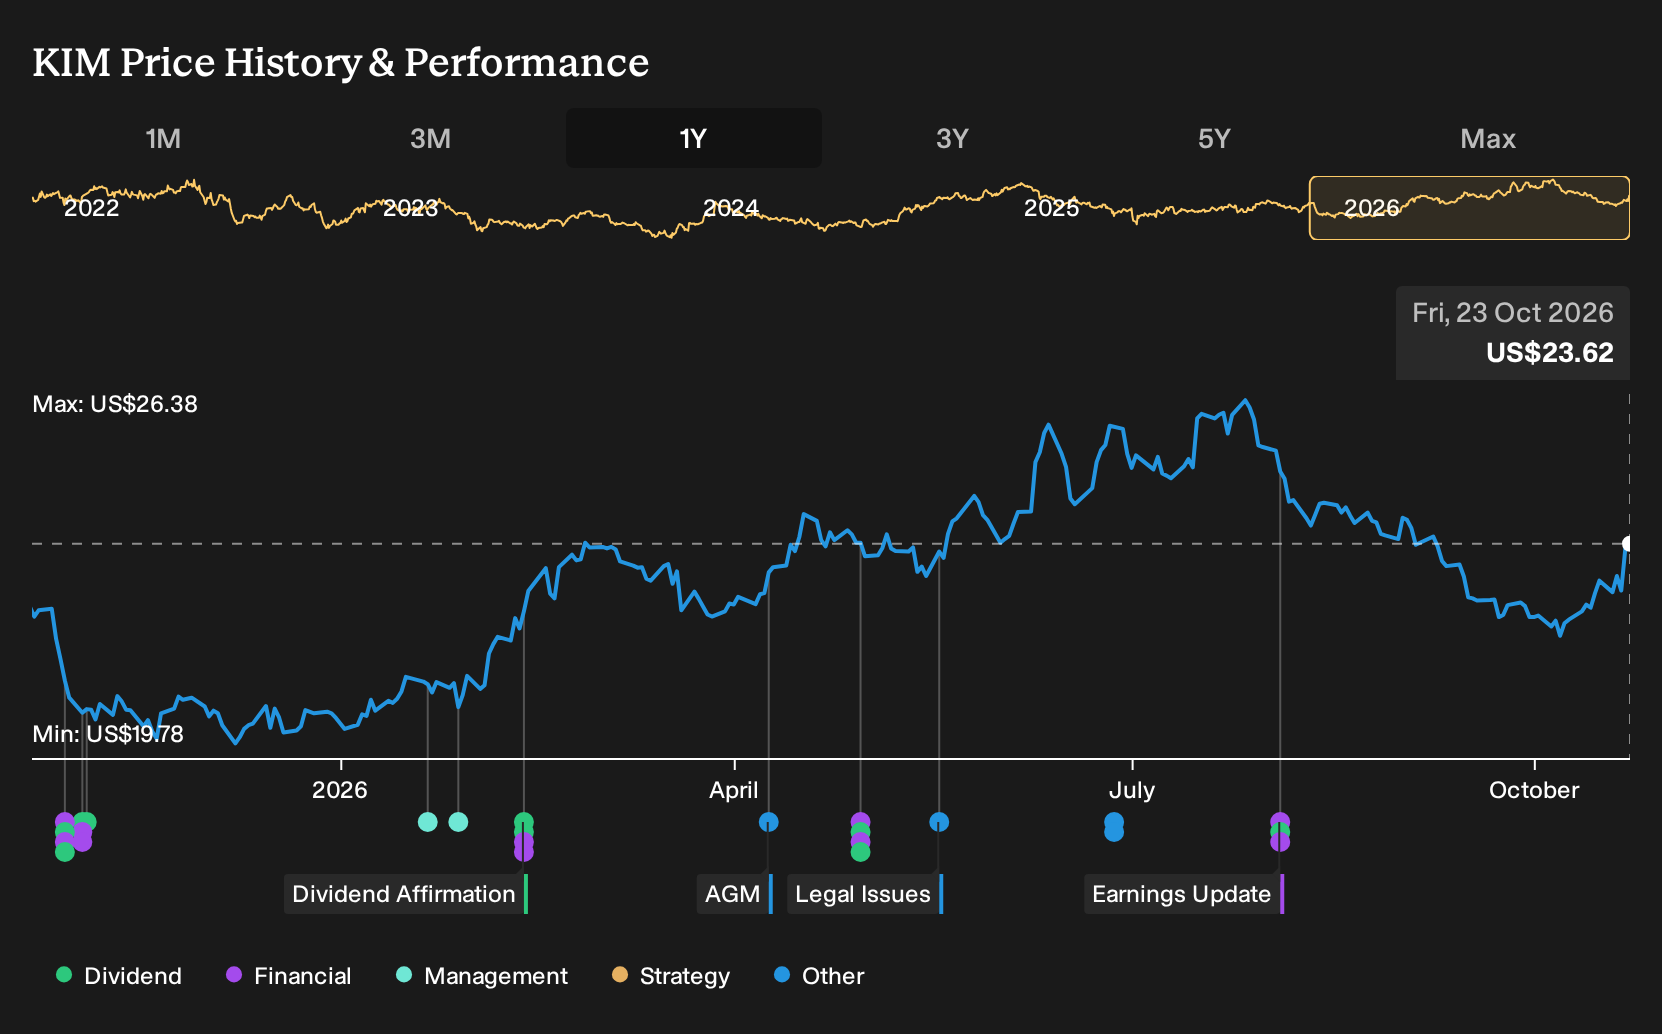
- Kimco Realty has recently been highlighted for offering a dividend yield above its industry average, with a track record of raising payouts and communicating expectations for earnings growth that support the current distribution.
- The focus on dividend consistency and earnings support matters because it ties Kimco Realty’s cash distributions directly to operating performance rather than short term market sentiment.
- We will now look at how Kimco Realty’s highlighted dividend strength could influence the broader investment narrative around its portfolio.
Kimco Realty Investment Narrative Recap
To own Kimco Realty, you need to be comfortable tying your thesis to grocery anchored, necessity based centers and the cash generation that supports its dividend. The recent reminder that its yield screens higher than peers and is backed by management’s earnings expectations reinforces that income angle, but does not radically alter the operating story.
The bigger near term swing factor still sits with execution on leasing and redevelopment versus rising interest expense on upcoming 2026 debt refinancings. Higher coupons could squeeze margins. The lawsuit around a Target anchored redevelopment also lingers as a risk that could affect costs and tenant relationships if it escalates.
In that backdrop, the renewed focus on Kimco Realty’s dividend strength is the announcement that stands out most. Management is explicitly tying the current payout to its earnings outlook, which puts attention on occupancy, leasing spreads and the US$95 million signed but not open rent pipeline that feeds into future cash flows.
For you as a holder, the question is whether that operating engine can offset higher funding costs and any legal overhang while still supporting the dividend profile being highlighted. Interest coverage is already flagged as a weak point, so monitoring refinancing terms, legal developments and how quickly new leases begin paying rent looks critical from here.
Kimco Realty Earnings Assumptions Behind the Dividend Story
Kimco Realty's income pitch ultimately links back to what analysts think the business can earn over the next few years. The current consensus builds in steady, though not explosive, progress rather than a step change. That matters for you because the dividend messaging is being layered on top of these specific revenue and profit expectations, not on vague hopes about retail real estate.
On the top line, the analyst group is penciling in revenue growth of 3.3% a year over the next 3 years. That is a modest clip for a large retail REIT. It effectively assumes that grocery anchored and necessity based centers stay leased, rents keep inching higher and the signed but not open pipeline converts into paying tenants on a reasonably predictable schedule. If those cash flows come through more slowly, the support for Kimco Realty's current payout could look thinner, even if the properties themselves remain busy.
Earnings forecasts add another layer to the story. The consensus points to profit of US$573.8 million today rising to US$643.9 million by 2029, which is roughly a US$70 million increase in absolute terms. Analysts are also baking in a small lift in profit margins from 26.2% to 26.7% over the next few years. Put together, that mix of slightly wider margins, modest revenue growth and a gradual earnings build is what underpins the dividend narrative that management has been highlighting.
Kimco Realty's narrative projects US$2.4 billion revenue and US$643.9 million earnings by 2029. This requires 3.3% yearly revenue growth and about US$70 million earnings increase from US$573.8 million today.
The forecast also assumes a slow decline in the share count, with analysts expecting outstanding shares to fall about 0.95% per year for the next 3 years. For you as a holder, that matters because even a modest reduction in shares can help support earnings per share and funds from operations per share, which are the figures many income focused investors watch most closely. A smaller share base can help keep per share dividend capacity intact even if operating earnings are only creeping higher.
Those same projections feed into how analysts frame valuation. To line up with the current consensus view, you would have to assume Kimco Realty reaches US$2.4 billion of revenue and US$643.9 million of earnings in 2029 and that the stock trades on a P/E multiple of 33.6x at that point. That compares with a P/E of 26.1x today and an industry level of 25.9x for US retail REITs. The gap between the current multiple and the implied future multiple is where expectations quietly sit. Any disappointment in execution on leasing, margins or refinancing could have a direct effect on how comfortable investors feel with the earnings and dividend story being marketed today.
Uncover why Kimco Realty's fair value indicates an 11% potential upside to its current price before that gap starts to close.
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community cluster between US$26.18 and US$33.05 per share, which shows how widely private investors can disagree on Kimco Realty. When you set that beside refinancing risk on 2026 debt and the lawsuit over a Target anchored project, you have real reasons to compare several viewpoints before leaning on the dividend story.
Explore another Kimco Realty fair value estimate, including one that suggests it could be worth just $26.18.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Kimco Realty research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Kimco Realty. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kimco Realty's overall financial health at a glance.
Looking For More Investment Ideas Beyond Kimco Realty?
If you like Kimco Realty’s income angle but want a wider bench of candidates, it can help to scan for stocks with different strengths and then compare how their fundamentals line up against your goals.
- For income that aims to lean on resilience rather than just headline yield, start with a curated list of 30 resilient stocks with low risk scores that is designed to hold up better when conditions get choppy.
- If you want yield backed by balance sheets that can shoulder payouts, check a focused list of solid balance sheet and fundamentals (25 results) and see which businesses pair income with financial resilience.
- When you are hunting for potential future leaders before they are widely followed, scan through a targeted 21 high quality undiscovered gems that screens for quality plus under-the-radar status.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com