


Amgen (AMGN) Draws Fresh Valuation Debate After Phase 3 TEZSPIRE Trial Results
Amgen (AMGN) is back in focus after new Phase 3 data for TEZSPIRE in eosinophilic esophagitis, with investors weighing what a broader use case could mean for the biotech’s long term product mix.
The TEZSPIRE readout comes after a strong run in Amgen’s stock. The share price is up 8.2% over the past month and 16.8% across 90 days, while the year-to-date share price return of 34.1% and 1-year total shareholder return of 54.7% point to powerful momentum that recent trial news and upcoming earnings expectations are helping to keep in focus.
Scan how Amgen’s momentum and TEZSPIRE catalyst compare with other potential breakout healthcare plays using our curated list of 34 healthcare AI stocks.
Amgen now trades around $439, above the average analyst target near $397, while some intrinsic value models still point to a sizeable discount. So where does fair value really land after this latest leg higher?
Most Popular Narrative: 22% Overvalued
Amgen’s last close at $439.26 sits well above the $359.98 fair value estimate in the most followed narrative, which frames today’s price as rich even after strong recent returns.
The "Amgen 2027 Bull Case" relies on a classic top-line fallacy: it assumes that macro obesity market growth and FDA's CNPV (Commissioner’s National Priority Voucher) tailwinds will automatically trigger a re-rating.
Here is the cold, data-driven reality:
1. CNPV addresses regulatory speed but not the manufacturing bottleneck. Amgen lacks the massive, domestic GLP-1 supply chain infrastructure that Lilly and Novo command. Fast-tracked approval without scale-up capacity only accelerates market-share caps.
2. The consensus overlooks the regulatory friction. The CNPV pilot program is facing severe legal durability and structural transparency questions in mid-2026. Basing a 2027 thesis on an unstable, non-statutory policy introduces substantial risk.
See why 7 investors see Amgen as 22% overvalued.
Result: Fair Value of $359.98 (OVERVALUED)
Still, faster than expected TEZSPIRE uptake or a smoother CNPV framework could quickly challenge the idea that Amgen is priced for perfection.
Find out about the key risks to this Amgen narrative.
Another View: Amgen Through a Market Lens
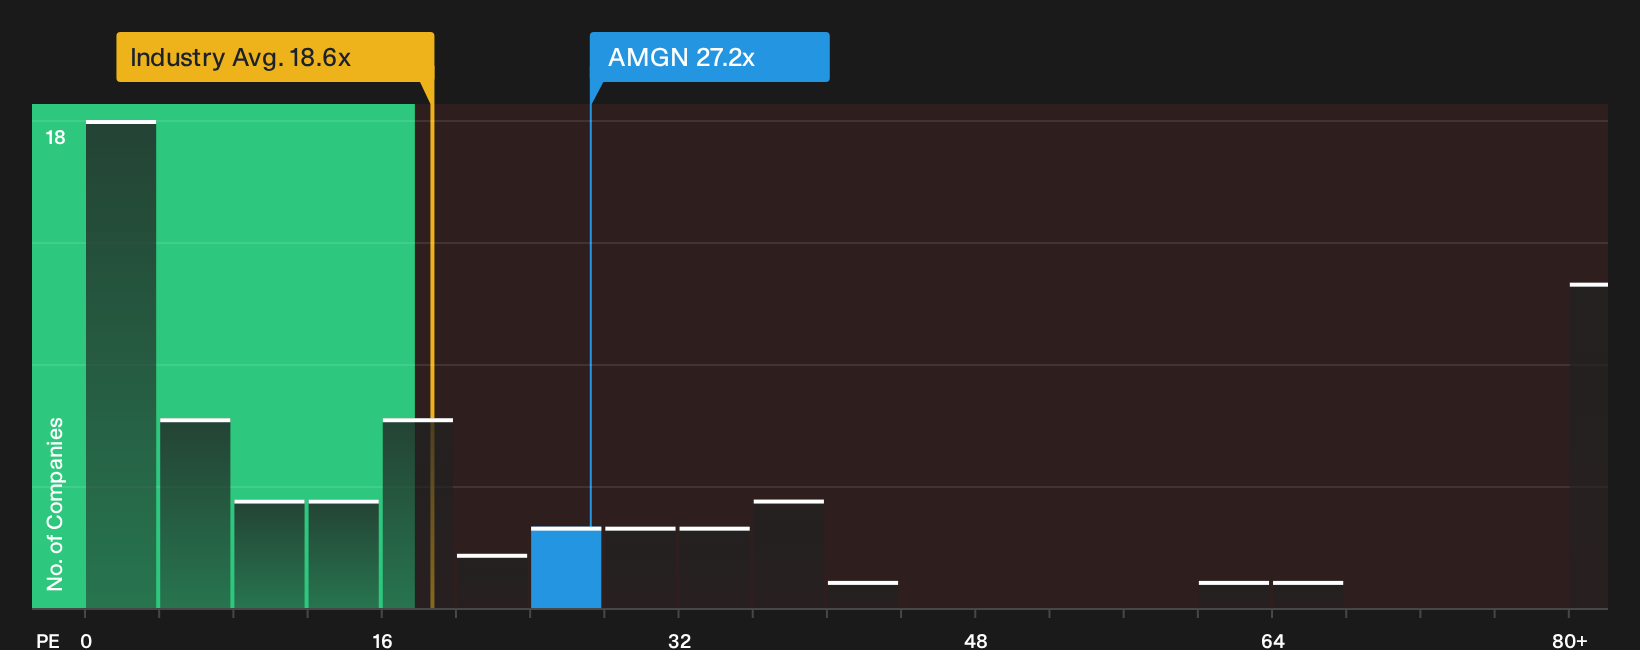
While the leading narrative pegs Amgen as 22% overvalued on a fair value of $359.98, the market’s own yardstick sends a different message. At a P/E of 27.2x versus a fair ratio of 31.8x and peer average of 43.4x, the stock looks cheaper than many large biotechs on earnings power alone. If the share price eventually drifts closer to that fair ratio, is the real risk missing a re-rating rather than overpaying today?
To see how that earnings multiple stacks up against peers in more depth, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Amgen’s price and fundamentals can tug you in both directions, so consider acting promptly, examine the numbers yourself, and weigh both the upside and the issues by reviewing the 4 key rewards and 1 important warning sign.
Looking for more Amgen investment ideas beyond this stock?
If Amgen has you thinking harder about healthcare risk and reward, do not stop with one ticker when there are targeted tools built to surface fresh ideas.
- Target potential bargains early and filter for quality using our 27 high quality undervalued stocks that focuses on stronger businesses trading below their implied worth.
- Prioritize stability and capital strength by scanning the list of solid balance sheet and fundamentals (25 results) so you are not caught off guard by fragile finances.
- Hunt for future leaders before the crowd catches on with the 21 high quality undiscovered gems, where under-followed companies with solid fundamentals are already on the radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com