


Transurban Group (ASX:TCL) Looks Fully Valued After Traffic Update And AGM Votes
Transurban Group (ASX:TCL) has given investors fresh data to work with after reporting September quarter traffic results and wrapping up its 2026 Annual General Meetings, with all resolutions passed by poll.
Recent moves suggest momentum is starting to rebuild in Transurban Group. The A$14.17 share price comes after a 7.35% 30 day share price return and a small decline in the 1 year total shareholder return, while the 3 year total shareholder return of 37.26% highlights the longer term appeal of the toll road model as the latest traffic and AGM updates refocus attention on operational stability and perceived risk.
Scan how Transurban Group compares with other infrastructure style plays by reviewing the curated 6 resilient stocks with low risk scores, which puts resilience and risk control at the center of the shortlist.
The recent lift in Transurban Group looks tied to hard traffic data and a quiet AGM season that signalled business as usual. Is the current A$14.17 price still reasonable for that mix of stability and sentiment shift?
Most Popular Narrative: 50% Undervalued
On Simply Wall St, the leading narrative on Transurban Group presents a fair value of A$14.245 compared with the A$14.17 last close. This keeps the current price almost perfectly aligned with that assessment while still framing the stock as materially below some other fair value models.
At A$14.245 per share, Transurban Group (ASX: TCL) appears reasonably valued based on its current cash flow and distribution guidance. Transurban generated free cash of 34.8 cents per share during the first half of FY26 and maintained full-year distribution guidance of 69 cents per share. This represents a forecast cash yield of approximately 4.8% at the assessed price, with the distribution expected to be fully covered by free cash.
See why 3 investors see Transurban Group as 1% undervalued.
Result: Fair Value of A$14.245 (UNDERVALUED)
Still, higher debt costs or weaker traffic on key Transurban Group corridors could pressure free cash coverage and challenge the current fair value narrative.
Find out about the key risks to this Transurban Group narrative.
Another View: Transurban Group On Earnings Multiples
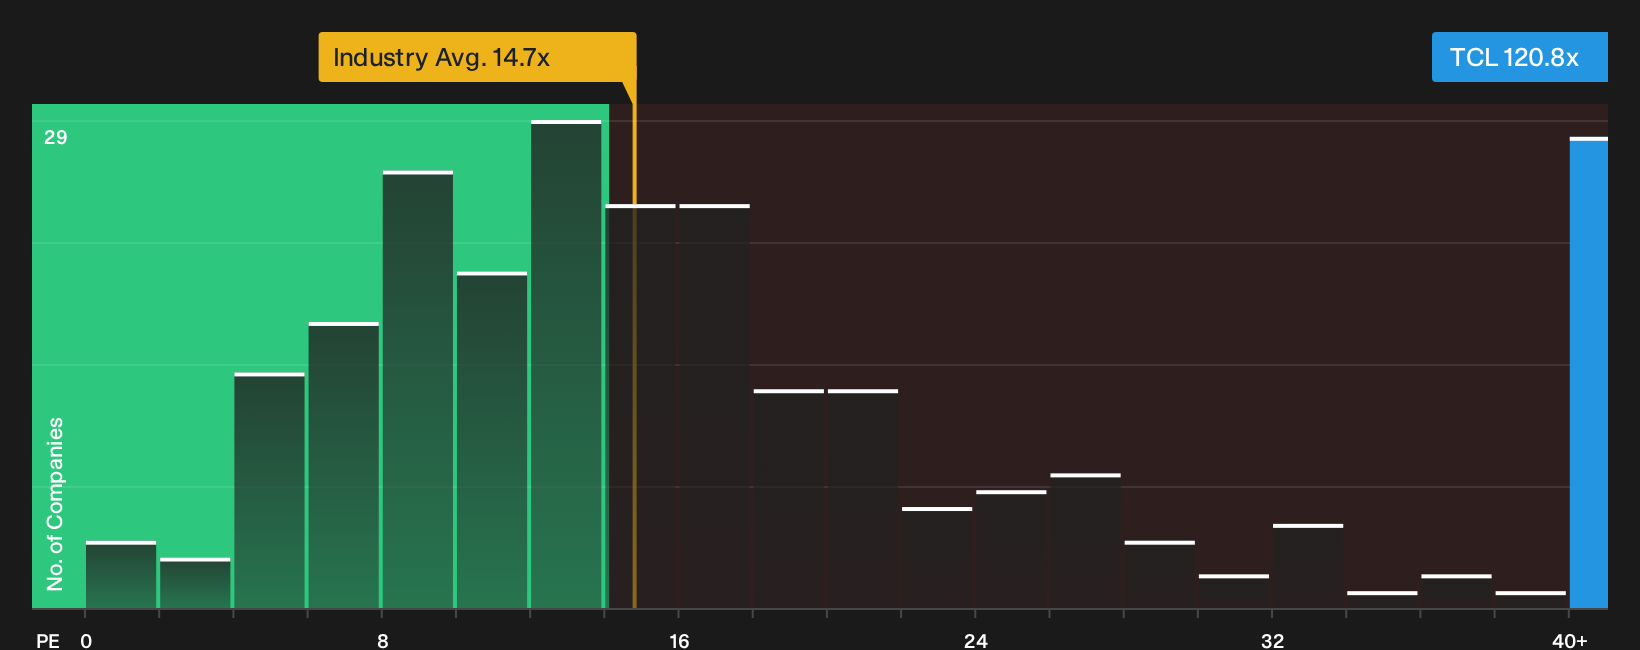
There is a very different message when you value Transurban Group using earnings multiples instead of fair value models. The stock trades on a P/E of 120.8x, while the peer average sits at 32.2x and the fair ratio is 23.7x. That kind of gap can signal rich expectations and less room for error, so how comfortable are you paying up for this level of perceived quality?
To see how this pricing stacks up in more detail, including how it compares with peers and the fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this combination of fair value signals and a high P/E ratio feels conflicting to you, consider acting while the data is fresh and weigh both sides yourself with 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Transurban Group?
Consider expanding your search beyond a single toll road stock, as the wider market offers a range of risk and income profiles that can be compared side by side.
- Target resilient cash generation by scanning companies with strong balance sheets and fundamentals through the list of solid balance sheet and fundamentals (12 results).
- Hunt for potential mispricing by reviewing a curated set of quality businesses trading below assessed value with the 4 high quality undervalued stocks.
- Build a payout-focused watchlist by zeroing in on income opportunities screened as 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com