


Is Winmark (WINA) Undervalued After Its Special Dividend And Third Quarter Revenue Growth?
Dividend announcements and fresh earnings put Winmark in focus
Winmark (WINA) highlighted both income and fundamentals by pairing a new special dividend with its regular payout and releasing third quarter results that showed higher revenue year over year.
Despite the fresh dividend news and higher third quarter revenue, Winmark’s share price has come under pressure. The stock is down 11.16% on a 7 day share price return and 30.35% lower on a year to date share price return, while the 5 year total shareholder return of 39.94% shows a much stronger longer run outcome.
Spot opportunities beyond Winmark by scanning a curated set of income and quality focused retailers and franchisors in the 5 dividend fortresses.Winmark now trades at a modest discount to one intrinsic value estimate, and at a far steeper gap to analyst targets after a sharp pullback. Is that a mispriced cash generator, or a market warning that still has teeth?
Price-to-earnings of 24x for Winmark: Is it justified?
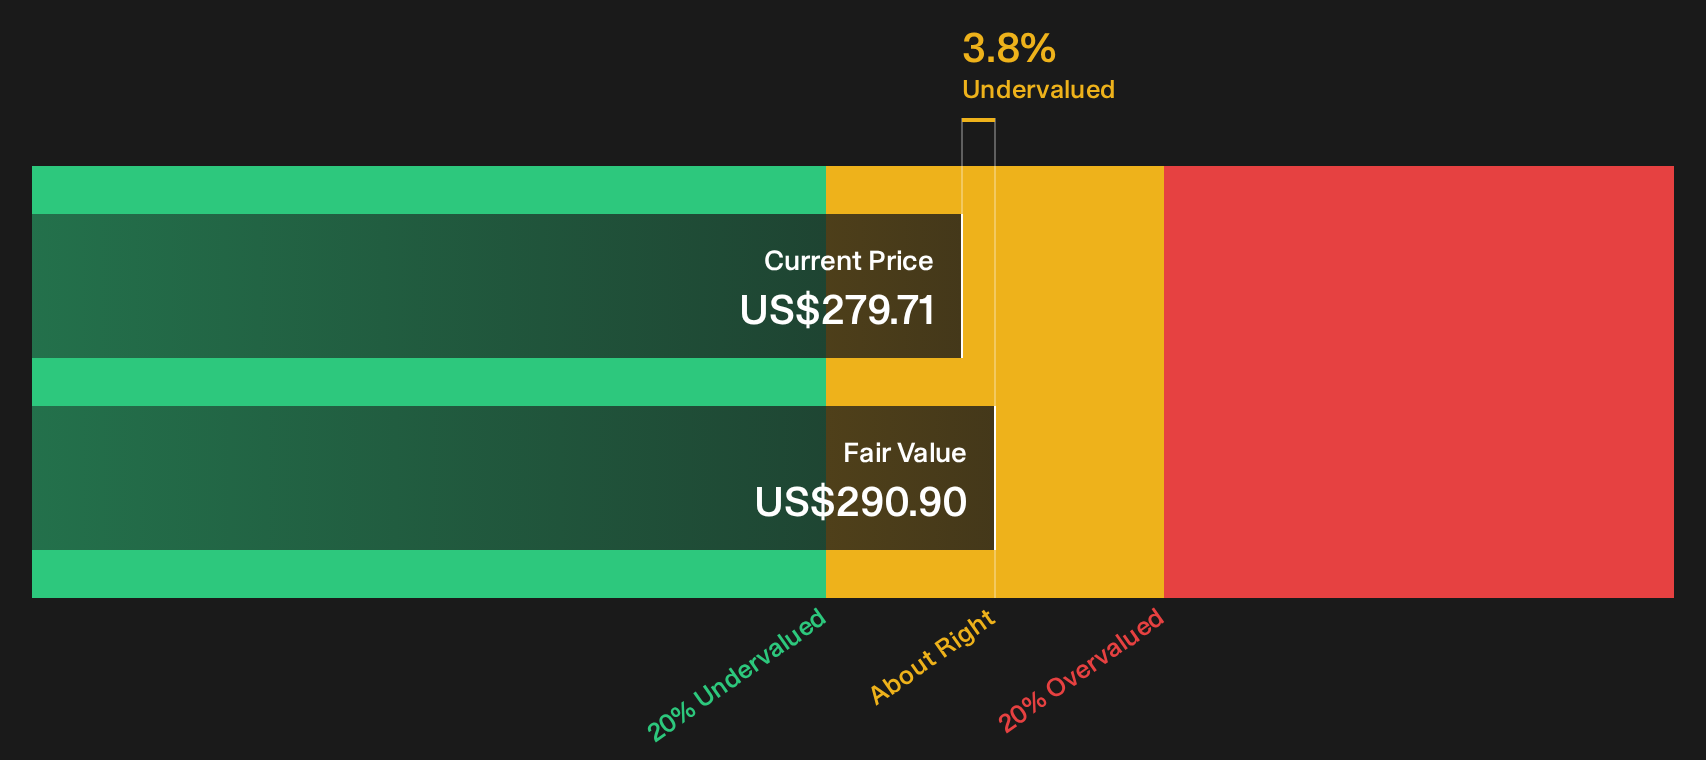
On simple valuation checks, Winmark screens as slightly below one intrinsic value estimate yet still carries a rich P/E tag compared with peers. The shares last closed at $279.71, which is about 3.8% below one fair value estimate of $290.90, while sitting on a 24x P/E.
The P/E metric compares what you pay today with the earnings that Winmark currently generates per share. For a franchisor that leans heavily on fees and royalties from resale concepts, that ratio reflects how much investors are willing to pay for what has been described as high quality earnings.
That willingness has a limit. The stock is labelled expensive versus the US Specialty Retail industry on several checks, with the 24x P/E above a 17.3x sector average, a 18x peer group average, and also above an estimated fair P/E of 9.5x that the market could move toward if sentiment cools on the story.
Explore the SWS fair ratio for Winmark.
Result: Price-to-earnings of 24x (OVERVALUED).
Still, the story around Winmark can change quickly if franchise demand softens or if royalty driven earnings fail to keep pace with the current P/E multiple.
Find out about the key risks to this Winmark narrative.
Another view on Winmark’s value
The P/E points one way, yet our DCF model nudges in the opposite direction. On that framework, Winmark at $279.71 sits about 3.8% below an estimated future cash flow value of $290.90, which frames the stock as mildly undervalued rather than stretched.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Winmark for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Winmark can feel confusing, so consider reviewing both sides of the story and weighing the 3 key rewards and 4 important warning signs
Ready for more investment ideas beyond Winmark?
If Winmark has your attention, do not stop here. Fresh ideas often come from scanning wider, and the right watchlist starts with a strong short list.
- Target steadier compounding by reviewing companies with strong cash positions and robust fundamentals using the list of solid balance sheet and fundamentals (25 results).
- Hunt for potential bargains by filtering for financially sound businesses trading below intrinsic value through the 27 high quality undervalued stocks.
- Build a reliable income watchlist by focusing on companies that combine yield with resilience via the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com