


Landis+Gyr Group (SWX:LAND) Could Be 13% Undervalued After Metercor Canada Deal
Landis+Gyr Group (SWX:LAND) drew fresh attention after announcing a new distribution and service partnership with Metercor in Canada, expanding access to its smart metering and grid-edge hardware across the country.
Recent trading has picked up, with a 19.03% 90-day share price return and a 5.95% 30-day move suggesting improving momentum around Landis+Gyr Group as investors react to developments like the Metercor partnership, even though the 1-year total shareholder return is still down 14.20%.
Scan beyond Landis+Gyr Group and this Metercor deal by reviewing utility and grid-technology peers in our hand-picked 42 power grid technology and infrastructure stocks for potential momentum or overlooked opportunities in the same theme.
Landis+Gyr Group now trades at a discount to both analyst targets and an estimated intrinsic value, even after the recent bounce. Is that caution a warning sign or an opening for patient investors?
Most Popular Narrative: 13% Undervalued
Against a last close of CHF51.60, the most followed narrative pegs Landis+Gyr Group at a fair value of CHF59.33. That gap is tied directly to how reliably today’s backlog and software mix convert into future cash flows under a 6.1% discount rate.
The sharper focus on the Americas and other higher margin geographies after the EMEA divestment, combined with a record backlog of about US$3.9b and a strong pipeline in Connected Platforms, positions Landis+Gyr Group to support future revenue and adjusted EBITDA growth as contracted deployments convert into sales and margin accretive projects ramp.
The expansion of Grid Intelligence and edge applications, including the commercial launch of the Revelo E370 meter, new edge app partners in Australia and growing gas IoT projects, increases the addressable software and services revenue tied to the installed device base, which can support both top line growth and higher overall gross margins.
See why 10 investors see Landis+Gyr Group as 13% undervalued.
Result: Fair Value of CHF59.33 (UNDERVALUED)
Still, the narrative can crack if large deployments leave a wider revenue gap than planned, or if utilities delay converting that record US$3.9b backlog.
Find out about the key risks to this Landis+Gyr Group narrative.
Another View: How Landis+Gyr Group Screens On Earnings
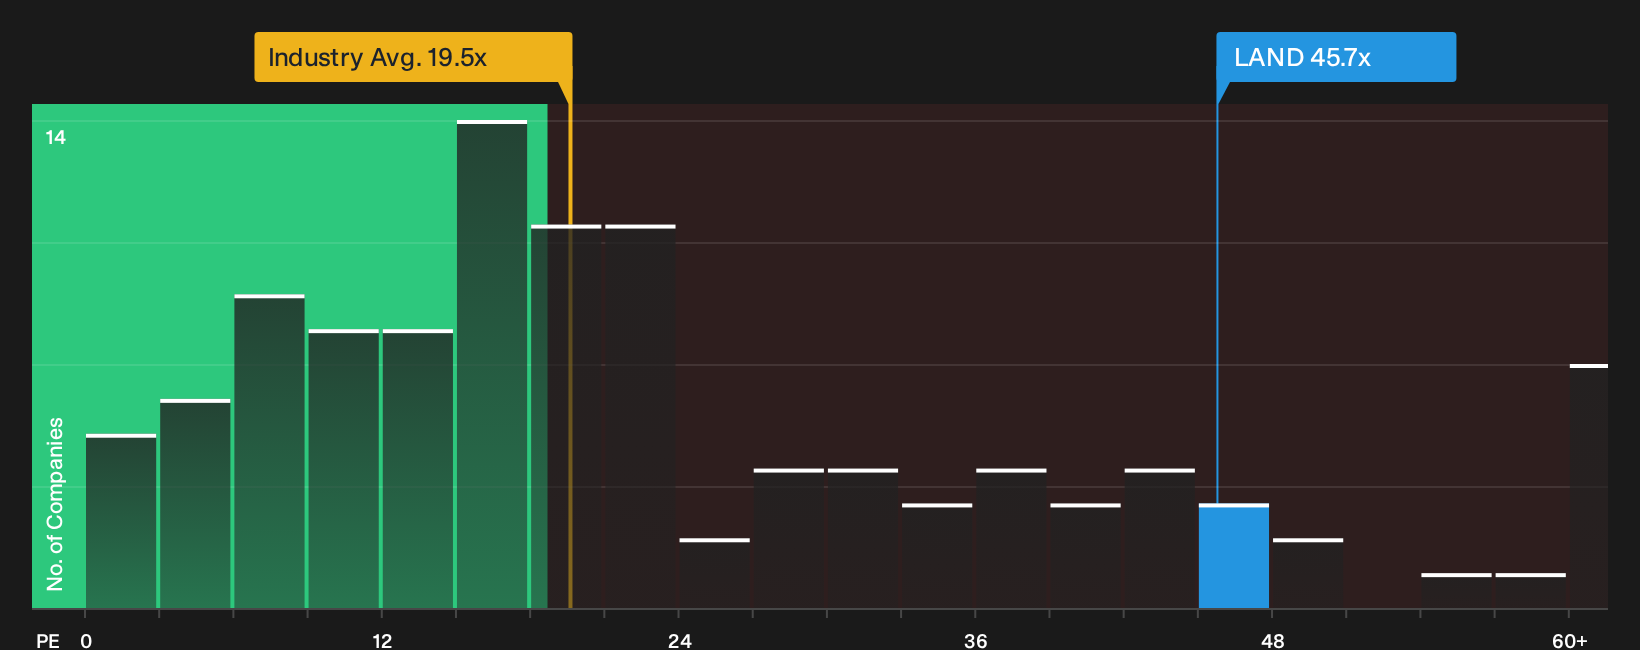
The fair value narrative leans on future cash flows, yet today the P/E ratio sits at 45.7x. That is above the estimated fair ratio of 38x and well ahead of the European Electronic industry average of 19.8x, even though it is below the peer group at 75.3x. Is the current multiple a cushion or a valuation trap if expectations reset?
To see how that P/E gap could close in either direction, and what the numbers imply for valuation risk versus upside, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Landis+Gyr Group can feel confusing. Move quickly from headlines to hard numbers and shape your own stance using the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Landis+Gyr Group?
You have seen how one story plays out with Landis+Gyr Group. Now widen your watchlist so you are not relying on a single opportunity.
- Target potential mispricings by reviewing companies that screen as high quality yet unloved in our 192 high quality undervalued stocks.
- Lock in more predictable cash returns by focusing on income ideas drawn from our 226 dividend fortresses.
- Dial back risk without giving up quality by searching for sturdier balance sheets through the 221 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com