


Taiheiyo Cement (TSE:5233), Why Is This Fresh Development Drawing Attention?
Taiheiyo Cement (TSE:5233) has filed a shelf registration for up to ¥130b in bonds, putting its funding toolkit in focus and raising fresh questions about future financing choices and balance sheet mix.
The bond shelf lands at a time when Taiheiyo Cement’s short term share price performance has been mixed. The 7 day return is down 2.04% and the 30 day share price return is down 1.15%. However, the year to date share price return sits at 4.35% and the 3 year total shareholder return is 73.97%, suggesting that recent moves appear more like a pause in a longer rebuilding of investor confidence around funding choices and business fundamentals.
Compare Taiheiyo Cement’s funding shift with other balance sheet focused opportunities by scanning our hand picked list of solid balance sheet and fundamentals (23 results) across the market.
Taiheiyo Cement looks like a solid, diversified business, and the new bond shelf highlights a management team still tuning its capital mix. The real tension now is simple: Are you paying a fair price for that strength?
Price-to-Earnings of 16.7x: Is it justified?
Taiheiyo Cement trades on a P/E of 16.7x, which leaves the stock priced above both its industry and peer averages at the current ¥4,124 share price.
The P/E multiple compares what you pay for each unit of earnings. For a mature materials group like Taiheiyo Cement it often reflects how confident the market feels about future profit trends and balance sheet risk.
For this cement and materials business, the higher P/E suggests investors are accepting a richer tag on current earnings, even though Return on Equity sits at 4.1% and net profit margins of 3% are below last year. The estimated fair P/E of 18.5x points to a level the market could move towards if forecasts and cash flows track expectations. The current 16.7x therefore sits at a discount to that fair ratio, even while it looks expensive next to the JP Basic Materials industry at 10x and a peer average of 10.3x.
Explore the SWS fair ratio for Taiheiyo Cement.
Result: Price-to-Earnings of 16.7x (ABOUT RIGHT)
Still, the story around Taiheiyo Cement could shift quickly if funding costs change materially, or if environmental recycling volumes soften and squeeze already modest margins.
Find out about the key risks to this Taiheiyo Cement narrative.
Another View: What Does The DCF Say About Taiheiyo Cement?
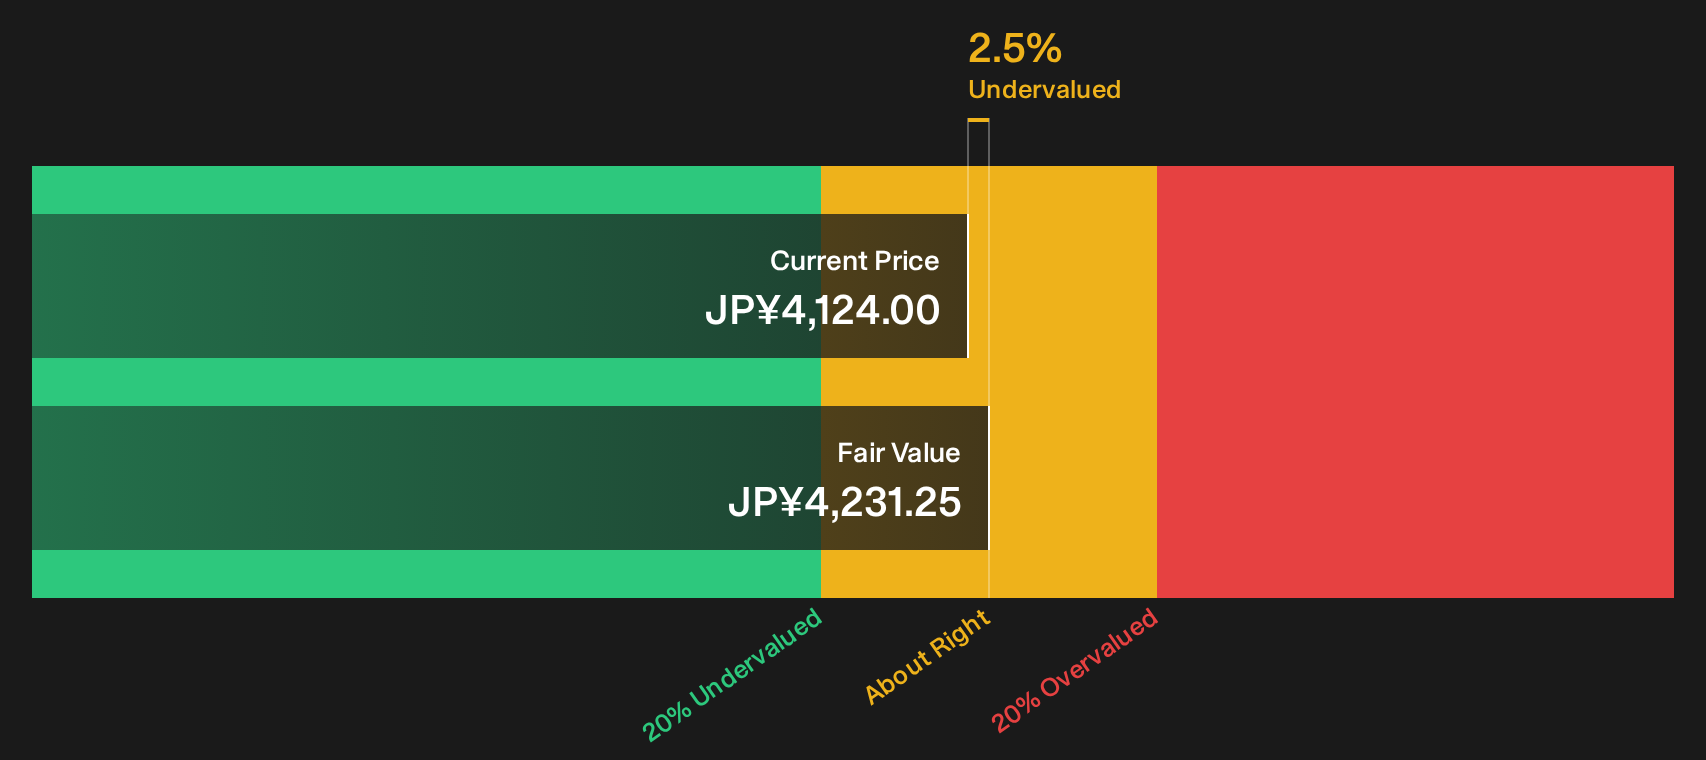
The P/E signals one story for Taiheiyo Cement. The SWS DCF model offers another. At ¥4,124 the stock trades about 2.5% below an estimated future cash flow value of roughly ¥4,231, which frames it as modestly undervalued rather than outright cheap.
This kind of small gap can close quickly if sentiment or bond funding costs move around. It leaves a simple question for you as an investor: is a narrow discount to the SWS DCF value enough of a margin of safety for a business with low current returns and mixed profit quality?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Taiheiyo Cement for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of modest valuation support and funding questions around Taiheiyo Cement leaves you on the fence, move quickly to test your own view by reviewing our breakdown of 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Taiheiyo Cement?
If Taiheiyo Cement has you thinking harder about value, risk and balance sheet strength, do not stop here. Your next opportunity shortlist could be only a few minutes away.
- Target potential mispricing by scanning companies that combine quality fundamentals with appealing valuations through our 14 high quality undervalued stocks.
- Build a portfolio with steadier return profiles by focusing on businesses that feature resilient financials via the 22 resilient stocks with low risk scores.
- Hunt for lesser known opportunities by checking companies with strong metrics that the market may be overlooking using the 72 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com