


Why Did FirstCash Holdings (FCFS) Stock Drop After Its Latest Update?
FirstCash Holdings (FCFS) is back in focus after a packed October 22 update, with Q3 2026 results, fresh guidance, a higher dividend, and a completed buyback all hitting at once.
Despite the strong Q3 update and richer dividend, FirstCash Holdings has seen the share price fall 6.5% on the day of the announcement and roughly 20% over the past month. However, the year-to-date share price return of 10.2% and 1-year total shareholder return of 13.1% still point to positive longer term momentum.
Spot opportunities beyond FirstCash Holdings by scanning our curated 21 high quality undiscovered gems with strong fundamentals that the wider market may be overlooking.FirstCash Holdings now trades about 30% below the average analyst price target after a sharp pullback. Is that a valuation gap, or a fair warning sign about the risks the market sees?
Preferred P/E of 18.4x: Is it justified?
Valuation pressure is now front and center for FirstCash Holdings, because the stock trades on a P/E of 18.4x after the recent pullback.
The P/E ratio compares the current share price to earnings per share and gives you a shorthand view of how much investors pay for each dollar of profit. For a lender and retail-focused financial business like FirstCash Holdings, that matters because earnings quality, return on equity and growth expectations all feed directly into what the market is willing to pay.
On one hand, the firm has some supportive data points. Earnings grew 31.2% over the past year and have compounded at 18.7% per year over five years. Net profit margin sits at 9.5%, slightly higher than last year, and earnings growth over the past year exceeded the Consumer Finance industry, which saw 17.6% growth. Analysts are in solid agreement on forecasts and see earnings continuing to grow, although at 17% per year this is not classified as significant growth by the framework used here. These factors help explain why investors may have been comfortable with a premium tag.
On the other side of the ledger, that 18.4x P/E carries clear trade offs. It is described as expensive versus the US Consumer Finance industry average P/E of 8.6x, and it also screens as expensive relative to an estimated fair P/E of 14.5x for FirstCash Holdings. The value score is only 1 out of 6, the SWS DCF model estimates a future cash flow value of $96.03 compared to the current $172.75 share price, and the business carries a high level of debt funded entirely through higher risk external borrowing rather than customer deposits. Those signals point to a valuation that leaves less room for error if growth or credit conditions disappoint.
Relative to the wider US market, the picture is more balanced but still not obviously cheap. The 18.4x P/E is slightly below the US market at 18.6x, which suggests investors are pricing FirstCash Holdings broadly in line with the average listed company. Yet when compared with the 14.5x fair P/E estimate that regression analysis points to, the stock trades at a clearly richer multiple that the market could move towards if sentiment cools or growth re-rates.
Explore the SWS fair ratio for FirstCash Holdings.
Result: Price-to-earnings of 18.4x (OVERVALUED)
Still, the FirstCash Holdings story could shift quickly if credit quality weakens in its pawn and payment portfolios, or if funding costs stay higher for longer.
Find out about the key risks to this FirstCash Holdings narrative.
Another View: Cash Flows Paint A Harsher Picture
Price multiples tell one story for FirstCash Holdings, but the SWS DCF model tells a tougher one. On that framework, estimated future cash flows point to a value of $96.03 a share, which is well below the current $172.75 price and frames the stock as expensive rather than just slightly rich. Which lens do you trust more when those two signals conflict so sharply?
Look into how the SWS DCF model arrives at its fair value.
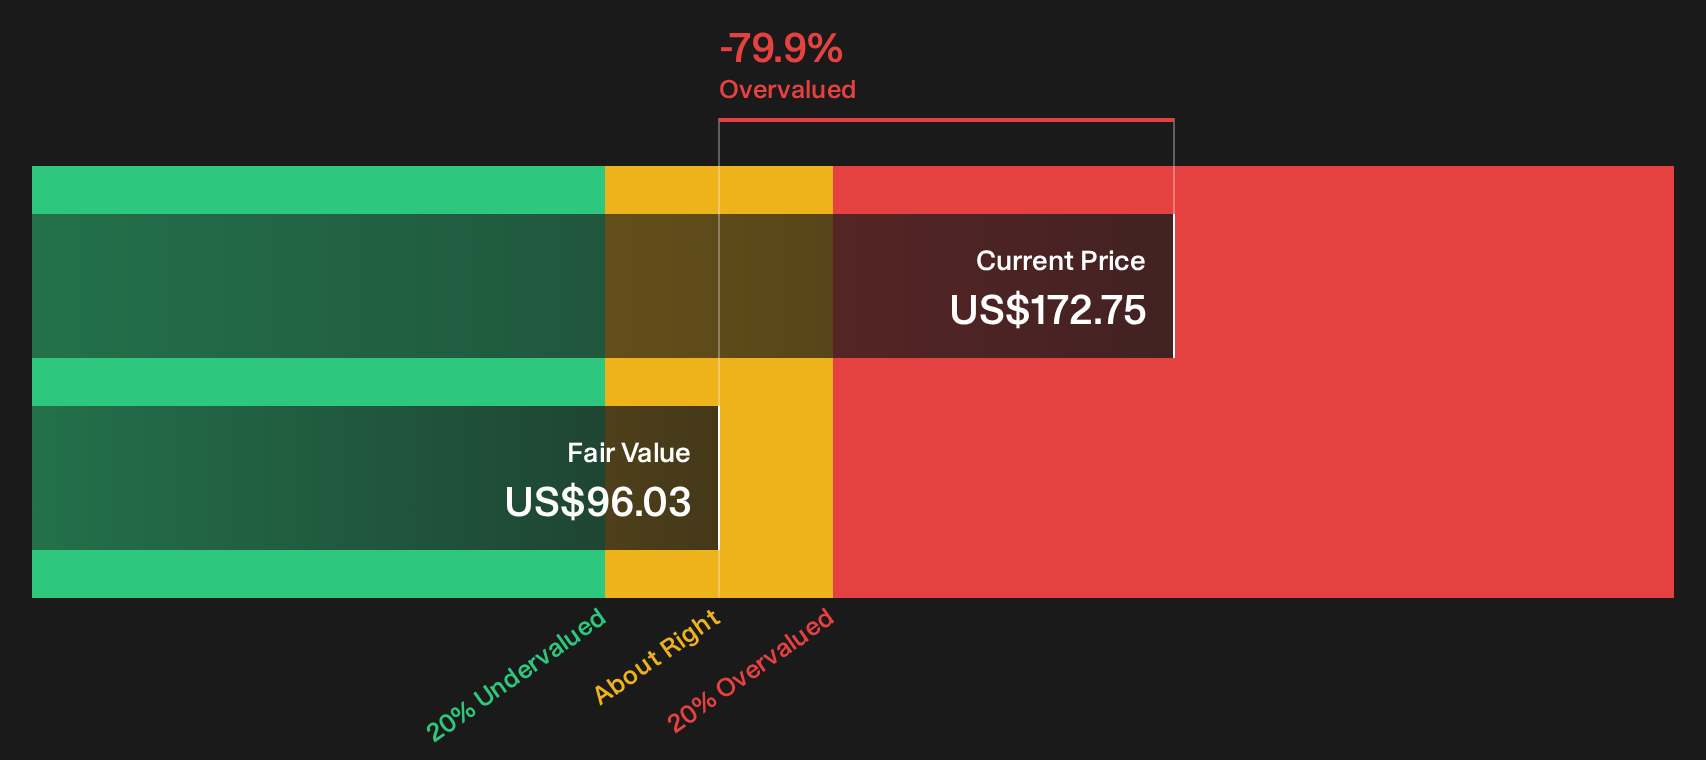
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out FirstCash Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around FirstCash Holdings is clearly mixed, with both pressure points and bright spots in the latest data. Move fast, review the full set of numbers, and decide where you stand on the balance of 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond FirstCash Holdings?
Do not stop your research with FirstCash Holdings. Broaden your watchlist now using structured stock ideas that line up with the type of opportunities you actually want to track.
- Target stronger balance sheets by reviewing a curated list of solid balance sheet and fundamentals (25 results) that highlights businesses pairing financial resilience with meaningful underlying fundamentals.
- Hunt for potential value opportunities through the 27 high quality undervalued stocks that focuses on companies combining quality, cash generation, and more modest valuation multiples.
- Prioritize stability by scanning a 30 resilient stocks with low risk scores that filters for businesses with lower risk scores so you can stay focused on capital preservation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com