


Why LeMaitre Vascular (LMAT) Is Back In The Spotlight
Recall event puts LeMaitre Vascular under closer investor scrutiny
LeMaitre Vascular (LMAT) has initiated a voluntary Class II recall of its TufTex Over-the-Wire Embolectomy Catheter after process testing found the device could not reliably sustain the required pull force before balloon failure.
At a share price of US$84.45, LeMaitre Vascular has posted a 4.8% 30 day share price return and a 5.3% year to date share price gain. However, the 1 year total shareholder return is slightly negative while the 3 and 5 year total shareholder returns remain firmly positive. This suggests long term momentum has cooled recently as investors weigh the catheter recall and upcoming leadership change against the company’s broader track record.
Scan how other vascular and medtech players are handling product risk and quality control by reviewing the hand picked 30 resilient stocks with low risk scores alongside LeMaitre Vascular.
Recent trading now leaves investors asking whether LeMaitre Vascular’s pullback over the past quarter reflects a change in the underlying earnings power or a reset in sentiment after the recall and leadership news, and what the current valuation implies.
Most Popular Narrative: 21% Undervalued
Against LeMaitre Vascular’s last close at $84.45, the most followed narrative points to a fair value of $107, putting the stock on a clear discount while the recall and guidance reset keep sentiment in check.
The main factor that has to go right is that Artegraft and the broader portfolio continue to support price driven organic growth and margin expansion, while international relocalization and tissue supply projects are executed effectively.
The relocalization and direct to hospital logistics buildout, including new or enlarged warehouses in locations such as Billerica, Madrid, Paris, Toronto, Dublin and Warsaw, has already cut shipping costs in examples like Spain and is linked to multi point European gross margin expansion. This suggests further margin and earnings benefit as these facilities mature and more countries move to direct distribution.
See why 6 investors see LeMaitre Vascular as 21% undervalued.
Result: Fair Value of $107 (UNDERVALUED)
Still, the trimmed 2026 guidance and ongoing regulatory scrutiny at sites such as New Jersey could quickly challenge the current optimism surrounding LeMaitre Vascular.
Find out about the key risks to this LeMaitre Vascular narrative.
Another View: LeMaitre Vascular Looks Expensive On Earnings
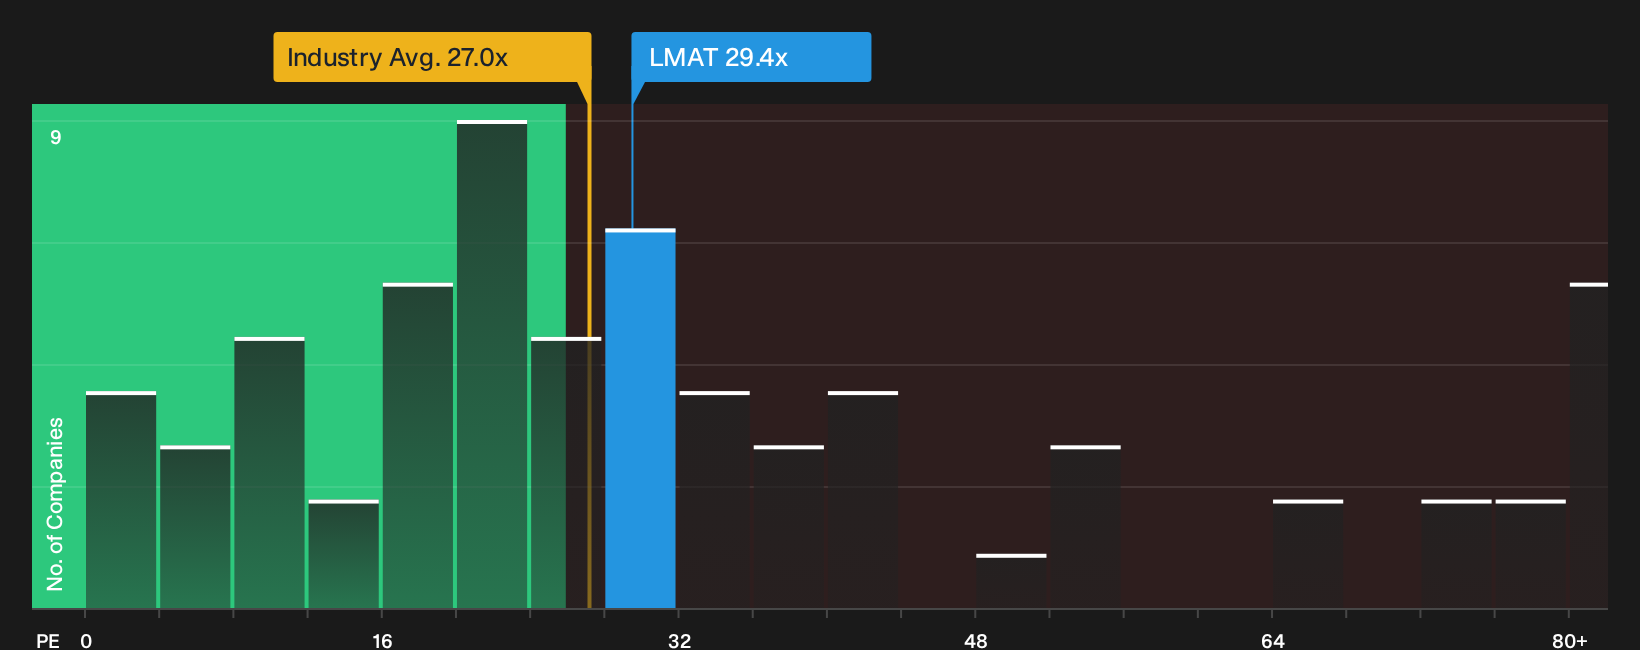
While the analyst narrative pegs fair value for LeMaitre Vascular at $107, the current P/E of 29.4x tells a tougher story. It is higher than both the US Medical Equipment industry at 27x and the estimated fair ratio of 22.8x, which points to valuation risk if sentiment cools further.
To see how the current pricing stacks up against the underlying earnings profile and peers in more detail, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment around LeMaitre Vascular is split, and that is exactly when doing your own work matters most. Act while the recall and valuation debate are fresh and pressure test the upside case by weighing the 2 key rewards.
Looking for more investment ideas beyond LeMaitre Vascular?
If LeMaitre Vascular has caught your attention, broaden your watchlist now by comparing it with other focused ideas filtered for quality, value and resilience.
- Target potential value opportunities and see which stocks screen well on quality and pricing through the 27 high quality undervalued stocks.
- Identify income-focused ideas by reviewing the 5 dividend fortresses that may suit a yield-driven approach.
- Raise the bar on financial strength by scanning the list of solid balance sheet and fundamentals (25 results) before choosing your next addition.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com