


Strong Q3 Earnings Could Be A Game Changer For WesBanco (WSBC)
- WesBanco reported third quarter 2026 results showing net interest income of US$226.88 million, net income of US$89.51 million, and diluted earnings per share from continuing operations of US$0.88, with higher year to date earnings compared with the same period in 2025.
- The bank paired these figures with commentary on strong commercial loan production, expanding Florida and Tennessee operations, and ongoing work on deposits, branch efficiency, and fee income from treasury and wealth services.
- We will now look at how WesBanco's investment narrative could be influenced by its strong third quarter earnings and loan growth.
WesBanco Investment Narrative Recap
To own WesBanco, you need to be comfortable with a regional bank that is leaning into commercial lending growth while keeping an eye on funding and costs. The latest quarter showed higher net interest income of US$226.88 million and net income of US$89.51 million, which supports that growth story but does not resolve funding and expense questions.
The key short term catalyst is whether WesBanco can turn its strong commercial loan production in markets like Florida and Tennessee into sustained, profitable balance sheet growth. The largest current risk is that loan growth outpaces largely flat deposits, which can force greater use of higher cost wholesale funding and strain net interest margin.
The third quarter earnings announcement is the clearest reference point here. WesBanco reported nine month net interest income of US$664.44 million and net income of US$270.82 million, with diluted EPS from continuing operations of US$2.67. That scale of profitability creates room to keep investing in South Florida, Tennessee and treasury and wealth capabilities.
For you as a shareholder, the link back to catalysts is direct. Strong earnings and a reported 17% return on average tangible common equity give management more flexibility to absorb higher operating expenses, fund new financial centers and support loan pipelines. The flip side is that if wholesale funding use increases and cost growth persists, those same metrics could come under pressure.
WesBanco's analyst narrative points to forecast revenue of US$1.3b and earnings of US$399.0 million by 2029, based on an assumed 6.4% yearly revenue growth rate. This path implies an earnings increase of about US$67.0 million, from current earnings of US$332.0 million to the 2029 consensus figure.
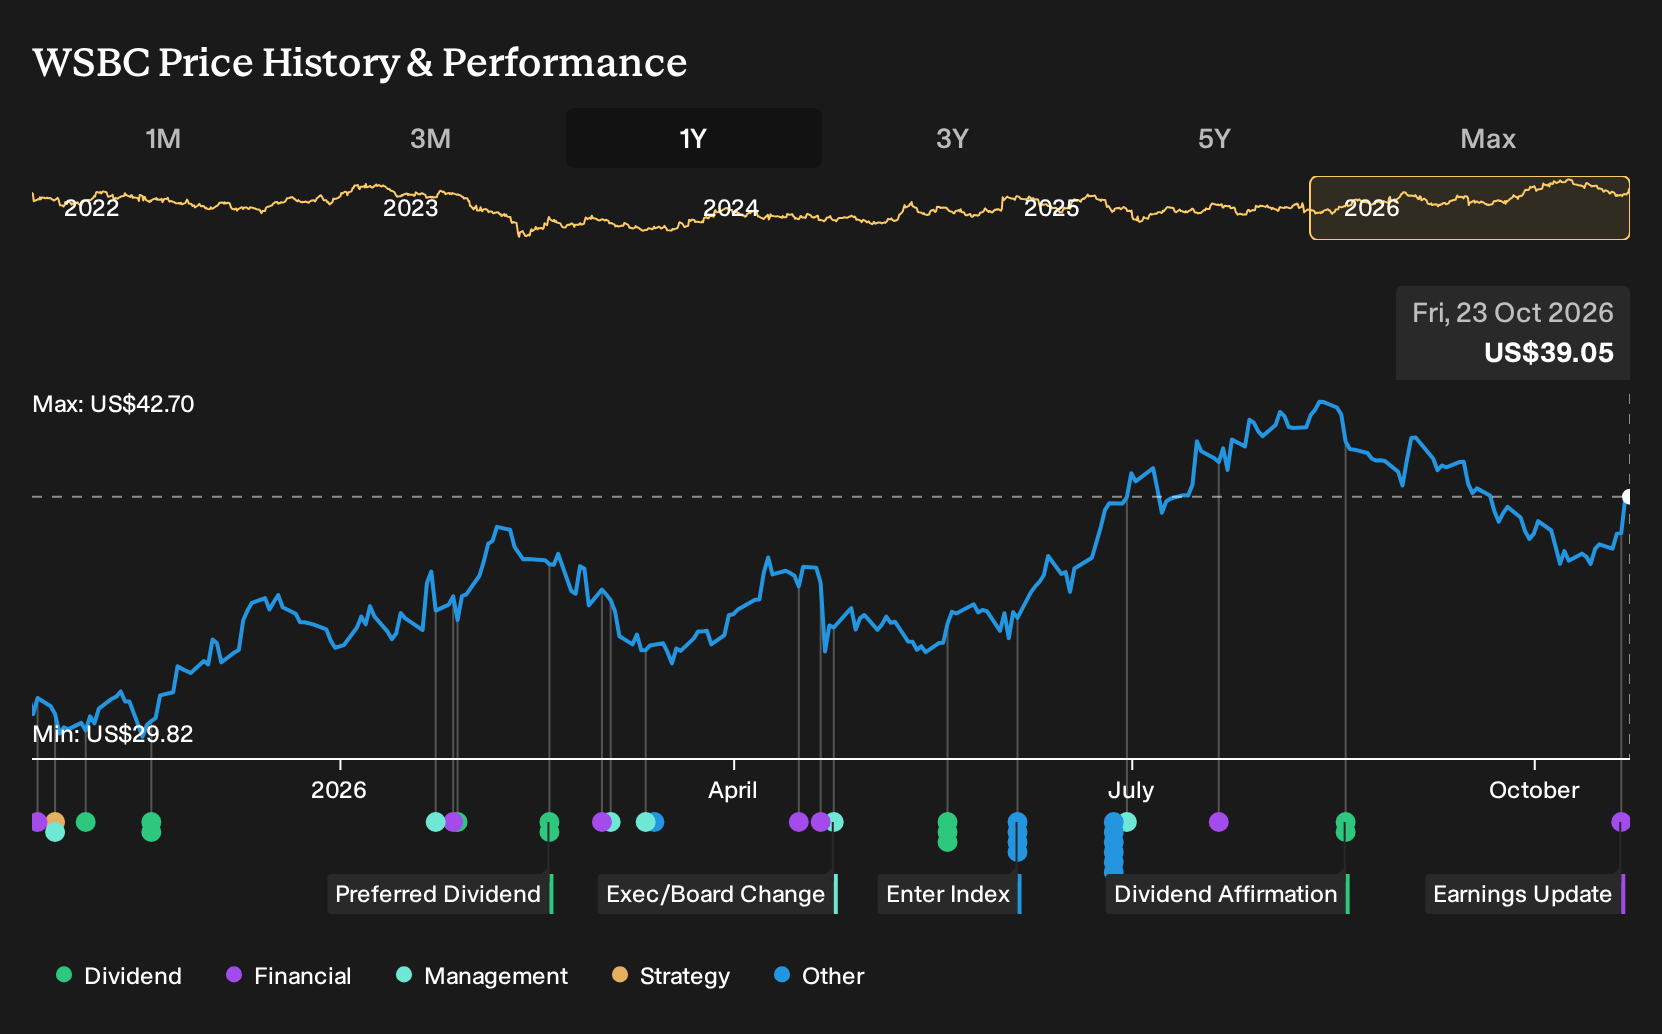
Uncover why WesBanco's fair value indicates a 14% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between about US$44.50 and US$63.30, which already shows how far apart private investors can be on WesBanco. Treat that spread alongside the risks around wholesale funding, commercial real estate payoffs and rising expenses, and you get very different trajectories for future performance.
Explore another WesBanco fair value estimate, including one that suggests as much as 62% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your WesBanco research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for WesBanco. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate WesBanco's overall financial health at a glance.
Looking for more WesBanco sized investment ideas?
If WesBanco has sharpened your view on what you want from a financial stock, use that clarity to screen for other businesses that fit your criteria on the Simply Wall St Screener.
- If capital preservation is near the top of your list, consider starting with a basket of companies that score well on resilience and risk using our 30 resilient stocks with low risk scores.
- Income focused investors can zero in on steady cash returns by scanning a curated set of higher yielding payers through the 5 dividend fortresses.
- For those hunting for quality that is not yet crowded, cast a wider net across under-followed opportunities with solid fundamentals using the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com