


What Investors Got Wrong Before Bodycote's Rally
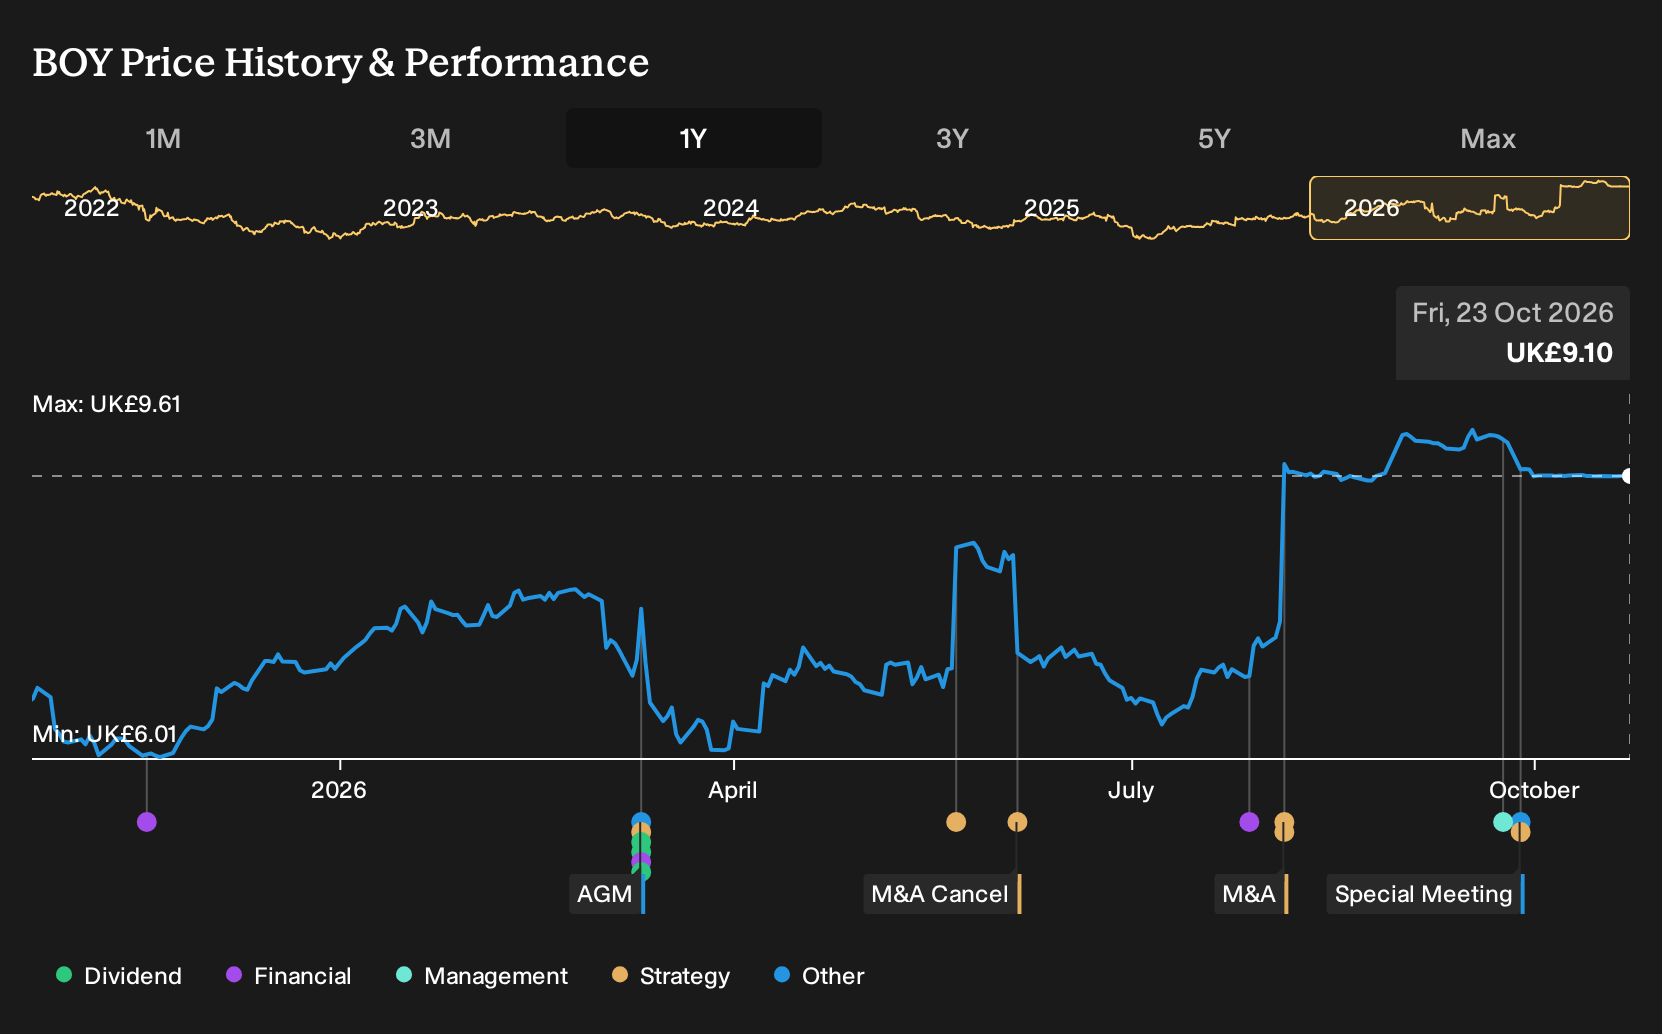
Bodycote’s story over the past year pivoted on one concrete event: the shareholder vote to approve a cash takeover by Vulcan Alpha Bidco, backed by Veritas Capital, with completion still dependent on regulatory sign off and targeted for early 2027. For Bodycote shareholders, the return over the past year was 38.7%, including dividends. If you were deciding whether to buy on 23 October 2025, what exactly had to be believed before that deal news arrived?
Bodycote has already moved. See which of 8 high quality undervalued stocks still trade below our estimates.
The Two Stories Around Bodycote Investors Had To Weigh
The shares cost £6.66 at the start of the period, and anyone looking at Bodycote then was really choosing which of two stories felt more convincing.
On the optimistic side, the bullish Narrative pointed to a Fair Value of £7.41. This is a notional price implied by its assumptions, built on US aerospace and defence work plus Industry 4.0 treatments like HIP. That view leaned heavily on Bodycote using capacity expansions and the Optimise and Carbon Smart programs to support margins in higher value sectors.
The pessimistic Narrative put Fair Value at £6.10. Again, this is just the price those expectations produced, and it focused on localisation, reshoring and regulation. That camp worried that stricter environmental rules, higher carbon costs and manufacturing moving closer to end customers would pressure Bodycote’s cross border work and weigh on revenue despite efficiency gains.
What The Results Put To The Test For Bodycote
The key Bodycote data point after October 2025 was the H1 2026 report, where revenue reached £381.2m and net income was £31m, with net margin at 8.1% versus 7.5% in H1 2025. That shift supported the optimistic margin story. The agreed cash acquisition and rising stakes from large holders cut both ways, backing the business quality but not settling the original valuation debate.
The lesson is clear. When a thesis leans on margin expansion, treat net margin as the hinge assumption and track whether it moves in the direction, and on the scale, the story requires.
What Bodycote’s Price Already Bakes In
Bodycote now trades at £9.1. The selected Narrative’s Fair Value sits below that level and frames the current quote as already paying up for mix improvement, efficiency gains and bid driven growth that still need to show through cleanly in reported profitability.
The question is what must keep going right for today’s price to hold. A buyer now would need confidence that higher margin work, footprint optimisation and bid activity lift net margins despite drag from restructuring, variable pay and ramp up costs.
"Although Bodycote is shifting more capacity into higher margin aerospace, IGT and medical work, the return of more normal variable pay together with ongoing ramp-up costs at new facilities such as the Mexico site and S3P South Korea is flagged as roughly a 100bp drag on margins through both halves of 2026 that only eases gradually. This risks keeping net margins below what mix improvement alone might suggest for several more years."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Find Your Own Contrarian Opportunity
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 28% below our estimate - targets a larger share of platform assets as inflows consolidate on a single tech stack.
- Company 2 - 21% below our estimate - attracts senior lawyers seeking higher fee share through a dispersed, tech enabled practice model.
- Company 3 - 18% below our estimate - scales in-house supplement manufacturing capacity as everyday fitness habits lift demand across new regions.
That is three of the list. See the full list of 9 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com