


China Construction Bank (SEHK:939) Raises CNY 70b In Bonds, Is The Stock Still Undervalued?
China Construction Bank (SEHK:939) has raised a combined CNY 70b through two callable fixed-rate bond issues: a CNY 55b 1.74% note due 2036 and a CNY 15b 1.93% note due 2041.
At a latest share price of HK$9.765, China Construction Bank has delivered a 25.19% year to date share price return and a 30.74% total shareholder return over one year, while the 161.58% three year and 166.20% five year total shareholder returns point to sustained momentum rather than a short term bounce.
Scan opportunities with balance sheets and funding profiles similar to China Construction Bank by checking our hand picked list of solid balance sheet and fundamentals (204 results).
Bulls see China Construction Bank’s strong recent returns and successful CNY 70b bond raise as confirmation of value. Bears point to risks around large state lenders. Which side does the valuation appear to support?
Most Popular Narrative: 25% Undervalued
Against a last close of HK$9.77, the most followed narrative pegs China Construction Bank’s fair value at HK$12.96, implying a clear valuation gap that hinges on how its lending mix and fee income story play out.
CCB is pushing a broad shift toward green, technology, manufacturing and inclusive lending, with green loans of CNY 6.53 trillion, technology related loans above CNY 5 trillion and manufacturing loans around CNY 4 trillion. This could gradually change the asset mix and support interest income resilience as these priority sectors deepen their use of bank credit.
See why 4 investors see China Construction Bank as 25% undervalued.
Result: Fair Value of HK$12.96 (UNDERVALUED)
Still, tighter rules on pricing, risk taking, and sanctions-related lending could cap China Construction Bank’s loan growth and keep pressure on fee income.
Find out about the key risks to this China Construction Bank narrative.
Another View On China Construction Bank’s Valuation
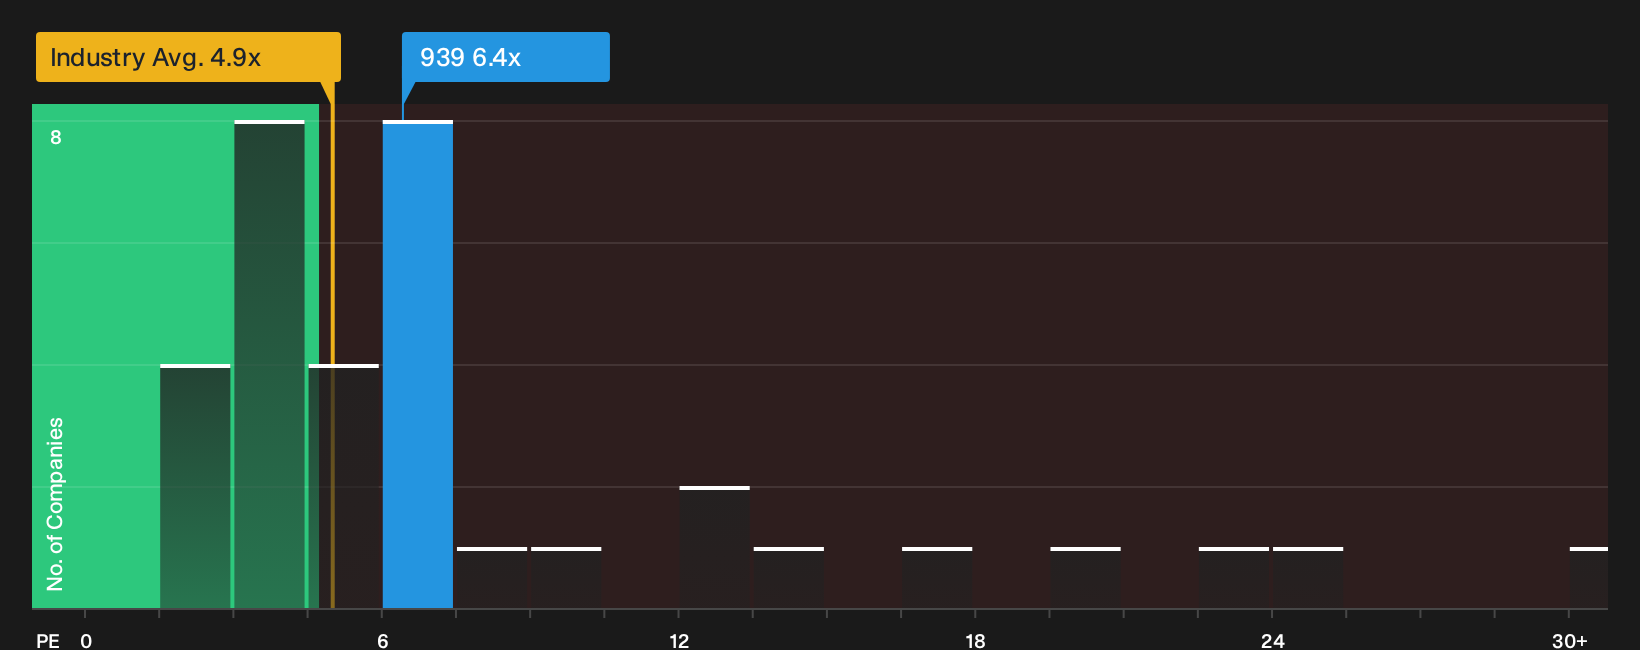
That HK$12.96 fair value comes from bullish analyst assumptions. A different lens looks at the plain P/E. China Construction Bank trades on 6.4x earnings versus 5x for the Hong Kong Banks industry, while the estimated fair ratio is 7.6x. That mix of discount to fair ratio but premium to peers raises a simple question: is the risk skewed toward re rating closer to the fair ratio or slipping back toward the sector average?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If sentiment in this China Construction Bank story feels divided, consider reviewing the data quickly and comparing it with your own view. To weigh the optimism against the risks in one place, start with the 4 key rewards.
Looking for more investment ideas beyond China Construction Bank?
Do not stop with China Construction Bank. Put fresh ideas on your radar by scanning other companies that match the kind of risk and reward profile you actually want.
- Target potential mispricings by reviewing companies that screen as high quality yet underappreciated through the 192 high quality undervalued stocks.
- Prioritize resilience and sleep better at night by focusing on businesses highlighted in the 221 resilient stocks with low risk scores.
- Get ahead of the crowd by tracking financially strong smaller players surfaced in the 615 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com