


nLIGHT (LASR) Could Be 56% Undervalued If Its Defense Growth Story Holds
nLIGHT (LASR) has been drawing fresh attention after recent trading swings, with shares near $36.34 following mixed short term performance. The stock shows gains over the past year, yet declines over the past month and the past 3 months.
For nLIGHT, recent trading has swung between enthusiasm and caution, with a 7.93% 7 day share price gain following a 30 day share price decline of 11.32%, while the 3 year total shareholder return of 339.42% indicates strong longer term momentum.
Track nLIGHT's swings alongside a curated group of similar opportunities by scanning the 55 AI infrastructure stocks that could be primed for their next big move.
The swing from a 48.1% 3 month slide to a 7.9% weekly bounce puts nLIGHT at a tricky crossroads. Does that setup still reward new risk, or mainly those already on board as valuation tightens from here?
Most Popular Narrative: 56% Undervalued
Compared with nLIGHT's last close at $36.34, the most followed valuation storyline pegs fair value near $82, which implies a steep gap that only makes sense if the long term defense and manufacturing thesis holds together.
The rapid growth and expanding pipeline in aerospace and defense, particularly around high-power laser solutions (e.g., HELSI-2 program, DE M-SHORAD, Golden Dome initiative, and increased directed energy orders internationally), positions nLIGHT to benefit from rising global defense spending and modernization, supporting strong multi-year revenue growth.
See why 16 investors see nLIGHT as 56% undervalued.
Result: Fair Value of $82.13 (UNDERVALUED)
Still, nLIGHT’s heavy tilt toward defense budgets and the weaker commercial segment could both undercut that undervaluation story if contracts or demand disappoint.
Find out about the key risks to this nLIGHT narrative.
Another View: What Multiples Say About nLIGHT
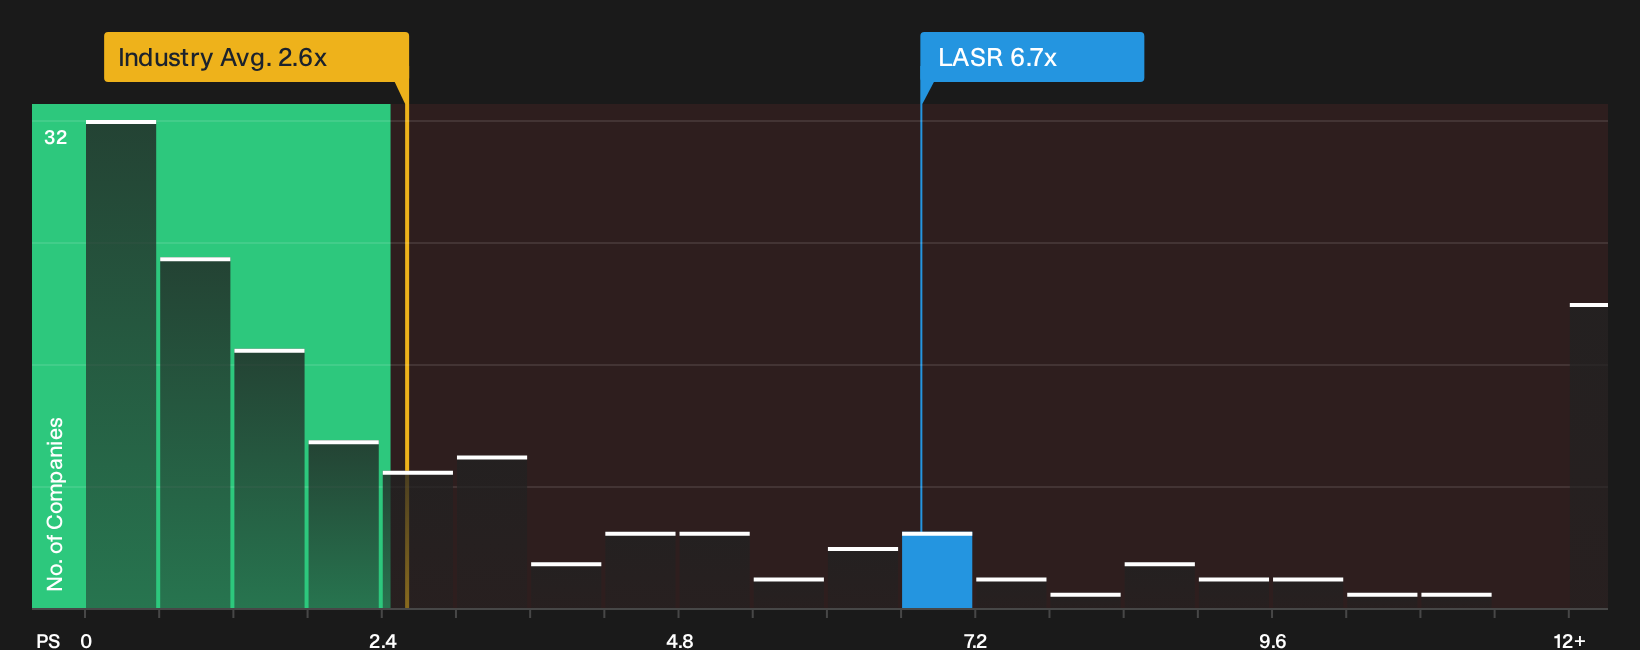
While the popular nLIGHT narrative leans on a fair value near $82, the current P/S of 6.7x paints a tougher picture. That level is well above the US Electronic industry at 2.6x, the peer average at 4.8x, and even a fair ratio of 1.8x that the market could move toward.
Such a wide gap signals meaningful valuation risk if sentiment cools or growth expectations soften, since even a partial move toward that fair ratio would imply a very different pricing backdrop for anyone considering new capital going into LASR.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around nLIGHT can be confusing, so treat this as a prompt to move quickly, review the numbers yourself, and weigh both sides of the story using the 2 key rewards and 3 important warning signs.
Looking for more ideas beyond nLIGHT?
If nLIGHT has your attention, do not stop here. Use the Simply Wall Street Screener to line up fresh ideas and keep your watchlist working harder.
- Target potential bargains by scanning a curated 27 high quality undervalued stocks that combine quality financials with prices that may not fully reflect their fundamentals.
- Strengthen your income stream by reviewing a focused 5 dividend fortresses that aim to pair higher yields with disciplined payout histories.
- Protect your capital by filtering for a 30 resilient stocks with low risk scores that score well on balance sheet strength and business resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com