


Is BELIMO Holding (SWX:BEAN) Undervalued On UBS Upgrade And Data Center Growth?
UBS just shifted its stance on BELIMO Holding (SWX:BEAN), upgrading the stock after reassessing how much future data center construction could feed into the company’s building automation hardware business.
That upgrade comes after a choppy spell for BELIMO Holding, with the share price falling about 9.5% over the past three months and around 7% year to date, even though the 3-year total shareholder return of roughly 114% indicates much stronger longer term momentum.
Scan how BELIMO Holding compares with other industrials tied to critical infrastructure by reviewing our curated list of 42 power grid technology and infrastructure stocks poised to benefit as data and energy demand keep climbing.
Bulls view BELIMO Holding as a data center beneficiary that has just reset lower, while bears see a premium industrial with too much optimism already baked in. Which story does the current valuation actually support?
Most Popular Narrative: 25% Undervalued
The most followed narrative on BELIMO Holding pegs fair value at CHF1,014.30, above the last close of CHF762. That gap frames the whole data center and retrofit story as the key swing factor for where the stock goes next.
The rapid expansion of the global data center industry, fueled by higher energy density and the shift to advanced liquid cooling systems, is significantly increasing demand for BELIMO's control valves and actuators. This surging vertical (now ~16% of group turnover, up from 10-11% last year, and growing 60% year-on-year) is likely to drive top-line revenue above consensus expectations as new capacity buildouts and retrofits accelerate over the coming years.
See why 11 investors see BELIMO Holding as 25% undervalued.
Result: Fair Value of CHF1,014.30 (UNDERVALUED)
Still, BELIMO Holding leans heavily on data center demand and a global supplier base, so any cooling in that pipeline or fresh supply chain friction could quickly challenge this upbeat undervaluation story.
Find out about the key risks to this BELIMO Holding narrative.
Another View: What BELIMO Holding’s P/E Is Telling You
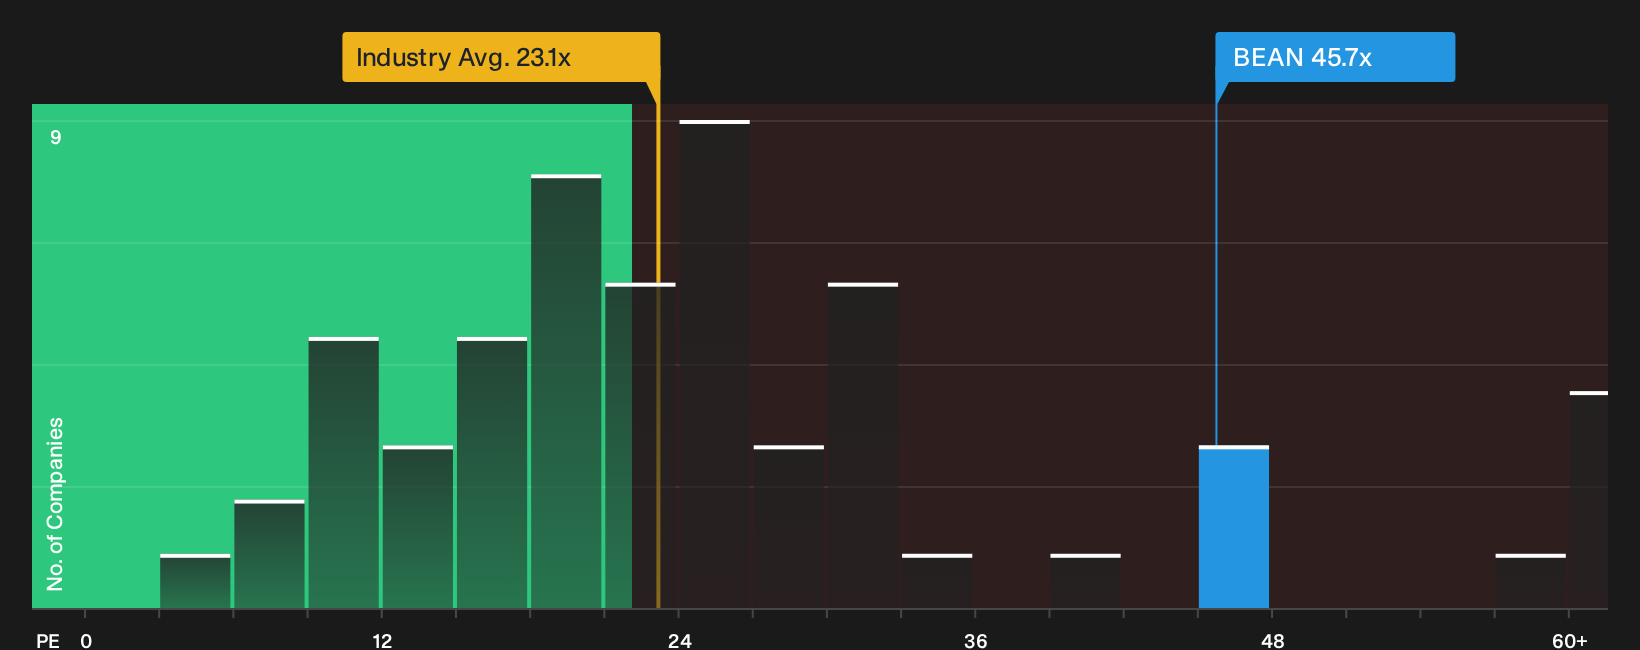
The fair value narrative presents BELIMO Holding as 25% undervalued at CHF1,014.30, yet the current P/E of 45.7x tells a tougher story. That multiple is far above the European Building industry on 23.5x and above the 31.1x fair ratio the market could move toward. If sentiment cools, how much premium are you really comfortable paying?
See what the numbers say about this price in our valuation breakdown, starting with the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Unsure whether BELIMO Holding is priced for too much optimism or not enough? Act quickly and review the full picture for yourself with 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond BELIMO Holding?
If BELIMO Holding has you thinking more broadly about where to put fresh capital, do not stop with a single stock. Widen your opportunity set with a few curated shortlists built to surface different types of potential ideas.
- Target proven cash generators by scanning companies with resilient income profiles and healthy finances through the list of solid balance sheet and fundamentals (204 results).
- Hunt for potential mispricings by using the 192 high quality undervalued stocks to spot opportunities where quality and price appear out of sync.
- Seek lesser-known opportunities by checking the 615 high quality undiscovered gems that pair strong fundamentals with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com