


Do Earnings Cuts Change The Bull Case For Olin Stock (OLN)?
- Olin is expected to report earnings for the September 2026 quarter that are lower than the same period last year, even though revenue forecasts are higher.
- The combination of rising sales and weaker profitability points to pressure on Olin's cost base and mix, which could limit the benefit of any top line growth.
- We will examine how Olin's investment narrative compares with this expected earnings decline, even as revenue shows positive momentum.
Compare Olin’s setup against a hand picked 27 high quality undervalued stocks that pair stronger earnings profiles with balance sheets built to handle cost pressure.
Olin Investment Narrative Recap
To own Olin, you need to believe the chemicals and ammunition portfolio can convert its cost programs and portfolio reshaping into cleaner, more durable earnings. The near term story hinges on whether Beyond250 savings, epoxy repositioning and Winchester optimization can offset pressure on chlor alkali and vinyls pricing and feedstock costs.
The latest expectation of lower earnings on higher sales mainly challenges that cost control narrative, not the existence of end demand. It places more emphasis on execution of synergy and efficiency plans as the key short term catalyst, while magnifying the current risk around leverage, interest coverage and any prolonged weakness in EDC and construction linked volumes.
The most relevant recent development tied to this setup is the planned merger with Huntsman and the creation of OlinHuntsman, with more than US$400 million of identified cost and integration synergies and pro forma 2025 revenue of about US$12.5b. This combination, if executed cleanly, could give Olin a broader, more vertically integrated chemicals platform to help absorb cost swings.
In the context of an earnings decline despite higher revenue, that proposed merger becomes a real testing ground for Olin’s ability to take fixed costs out and improve mix. The same news that highlights margin strain also underlines why synergy capture, Beyond250 savings and disciplined capital allocation matter so much when leverage is elevated and interest costs already limit flexibility.
Olin Earnings Framework Versus Analyst Assumptions
The analyst playbook around Olin points to a very different earnings picture than the near term setup around lower quarterly profit on higher sales. Consensus pencils in 4.9% yearly revenue growth over the next few years, profit margins moving from a current loss position of 2.9% to a positive 2.9% in three years, and a swing from a loss of US$196.9 million in earnings today to US$226.3 million by 2029. That is a US$423.2 million earnings improvement that needs to be bridged through cost savings, mix upgrades and the Huntsman merger plan rather than simple volume recovery.
On the top line, those same forecasts imply Olin reaches about US$7.7b of revenue and US$226.3 million of earnings by 2029. Analysts are effectively building a case where 4.9% annual revenue growth, a margin rebuild from loss making economics today and that US$423.2 million swing in profit all come together to support a 13.5x P/E on those 2029 earnings, which they then discount back into today’s price targets.
Uncover why Olin's fair value indicates a 27% potential upside to its current price that could narrow quickly.
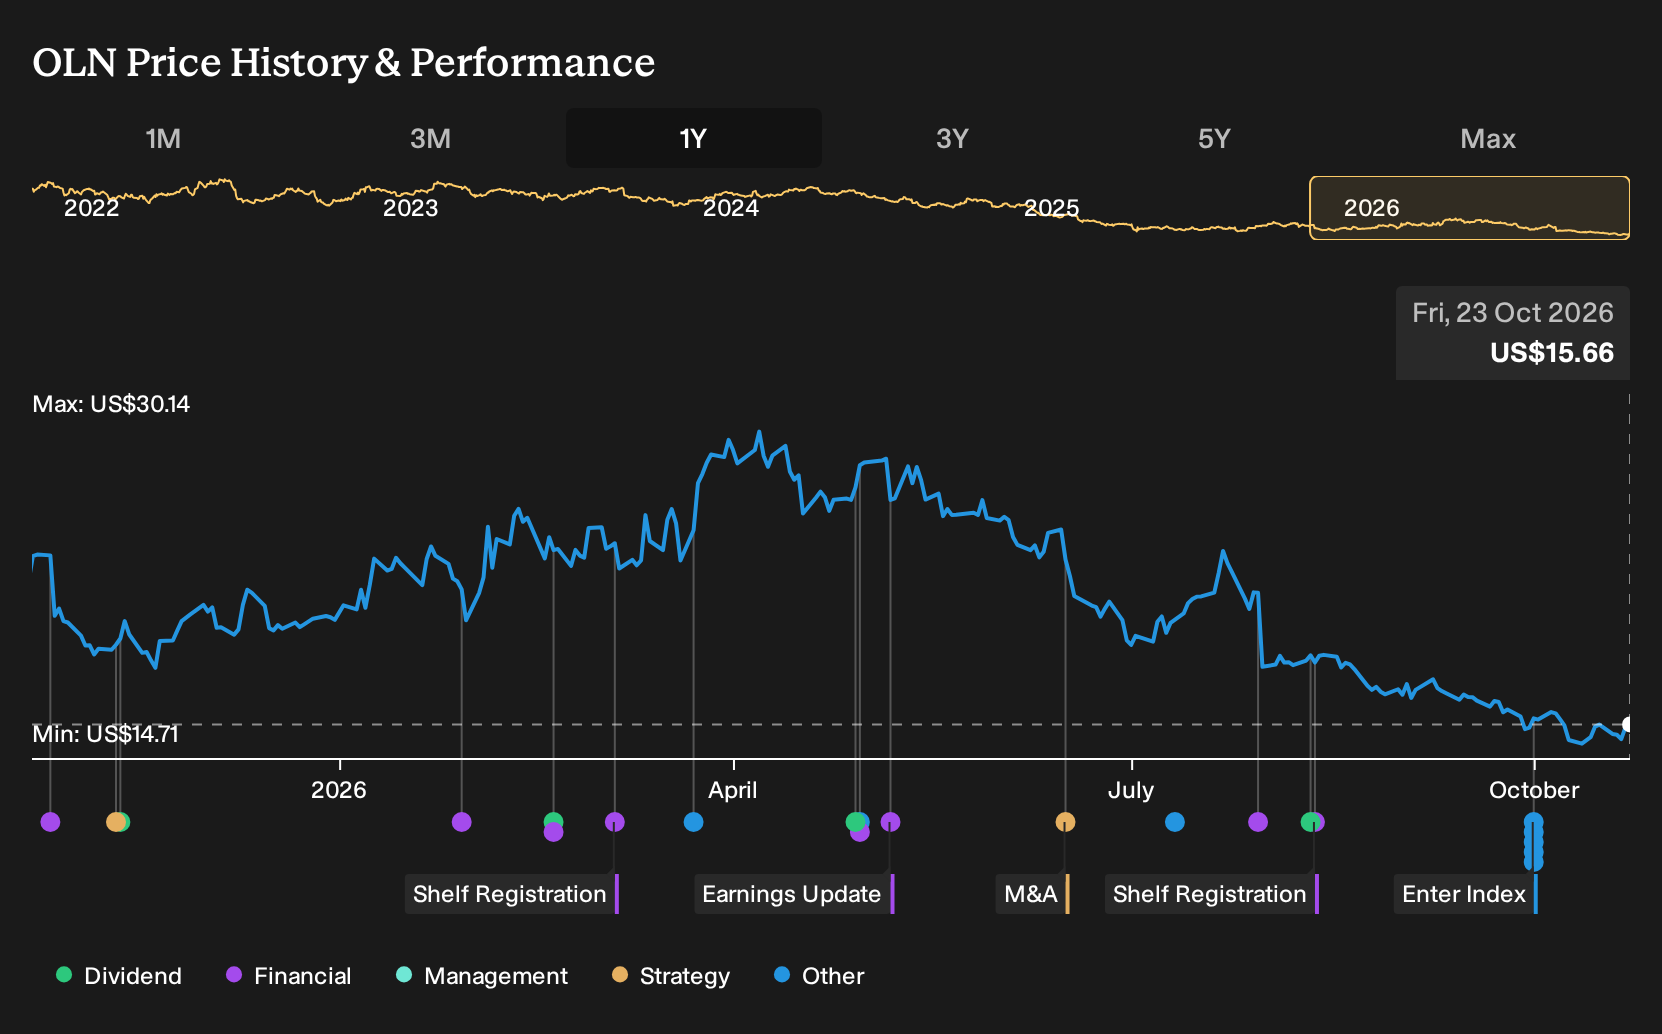
Exploring Other Perspectives
For Olin, the bearish twist is leverage risk. The lowest analysts were already penciling in slower annual revenue growth of about 3.8% and earnings of roughly US$182.2 million by 2029 before this earnings warning. That more cautious story shows how wide opinions run and invites you to compare several viewpoints as estimates get refreshed.
Explore 2 other Olin fair value estimates, including one that suggests it could be worth just $19.81!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Olin research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Olin. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Olin's overall financial health at a glance.
Looking For More Ideas Beyond Olin?
If Olin’s setup has you thinking harder about earnings quality, balance sheet strength and where to deploy fresh capital next, it can help to scan a wider field of opportunities side by side.
- For investors who care most about resilient balance sheets and steady fundamentals, compare Olin with a list of solid balance sheet and fundamentals (25 results) that can absorb shocks when costs or demand move against expectations.
- If you prefer steadier income streams, weigh Olin against a group of 5 dividend fortresses that may offer yield alongside more predictable cash generation.
- Those hunting for lesser known opportunities can contrast Olin’s story with 21 high quality undiscovered gems that pair underfollowed profiles with robust financial footing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com