


How Investors Are Reacting To Elevance Health (ELV) Raised Earnings Guidance
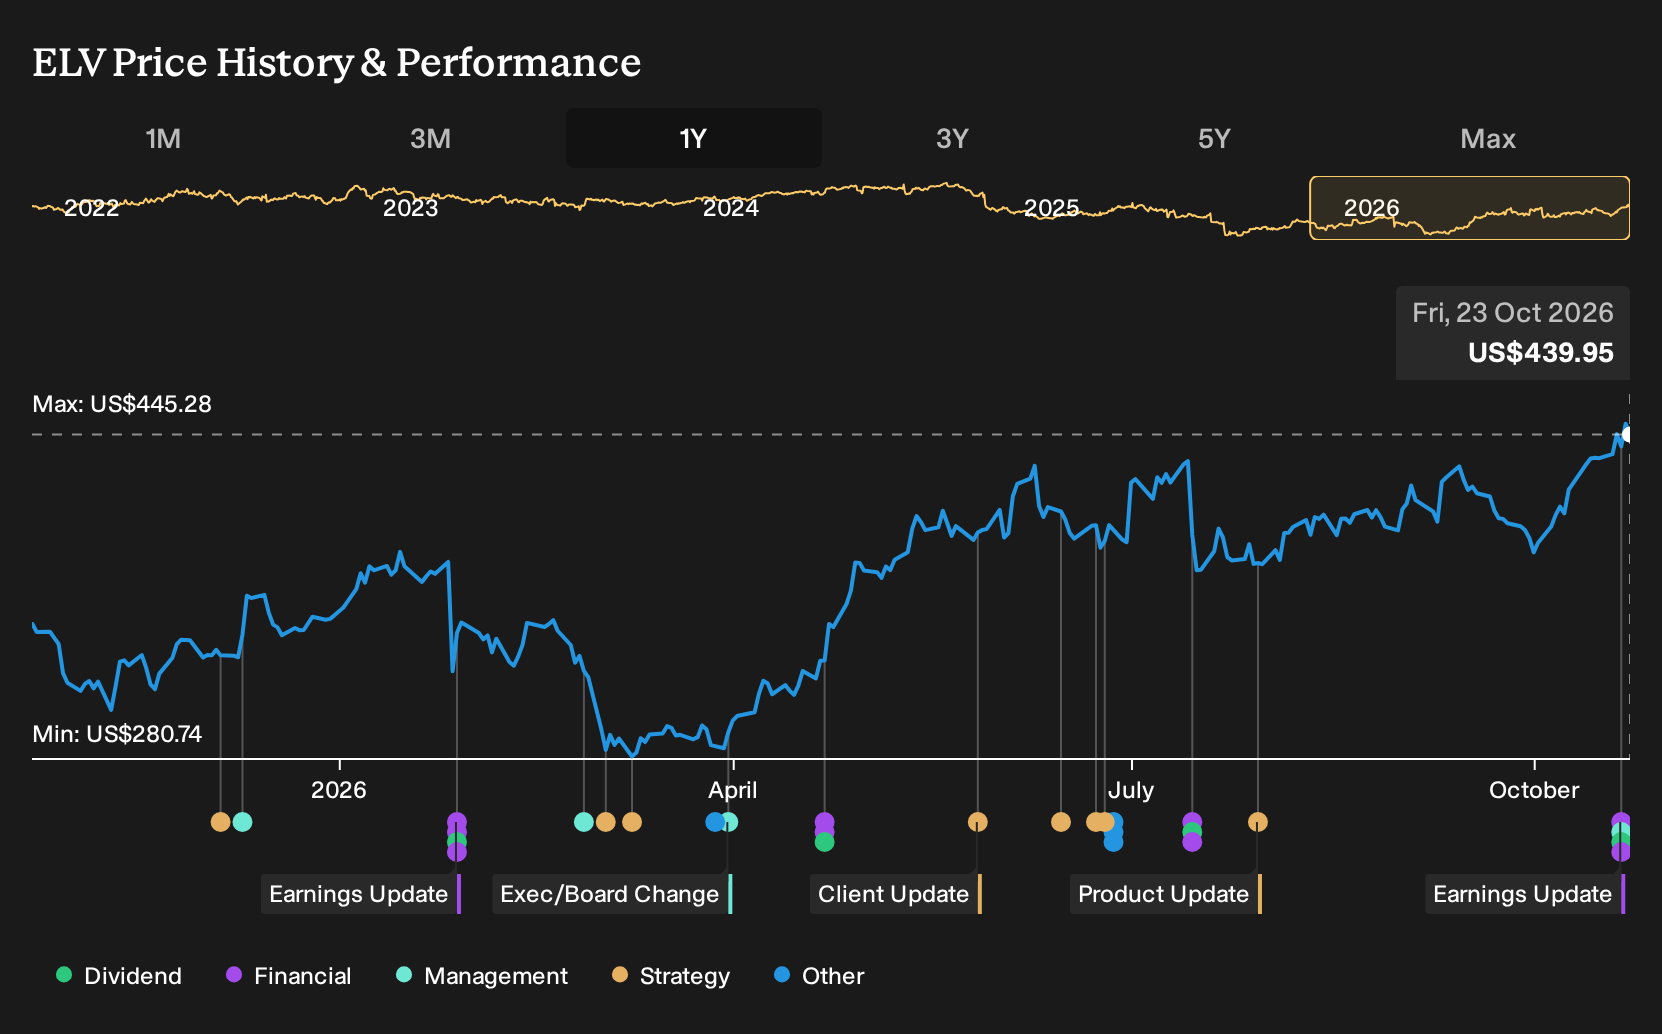
- Elevance Health reported Q3 2026 revenue of US$51.4b and net income of US$1.4b, raised full year diluted EPS guidance to at least US$22.00, and affirmed a US$1.72 fourth quarter dividend.
- The appointment of Jeff Park to lead Carelon signals a stronger operational focus on scaling services and tightening cost of care across Elevance Health.
- The market’s attention now shifts to how Elevance Health's higher earnings guidance may influence the existing investment narrative around margins and services.
Compare Elevance Health's earnings-driven story with other large insurers by scanning a curated set of list of solid balance sheet and fundamentals (25 results) that may offer similar resilience and income potential.
Elevance Health Investment Narrative Recap
To own Elevance Health, you need to be comfortable with a managed care story that leans heavily on tight cost control, disciplined government programs and growing fee-based services. The latest quarter shows higher revenue and net income versus a year ago, and a higher full year EPS outlook, which supports that operational thesis in the near term.
The short term hinge is whether medical cost pressures in ACA and Medicaid stay contained enough for margins to stabilize while Carelon gains traction. Margin compression in the trailing data keeps that risk very real. If care management, pricing and contract pruning do not bite quickly, the earnings bridge investors are watching could look stretched.
The most relevant fresh datapoint is Elevance Health’s move to raise 2026 diluted EPS guidance to at least US$22.00. That higher bar puts a spotlight on execution in Medicaid, Medicare Advantage and Carelon, because the business now has less room for error if cost trends or membership mix lean the wrong way.
For you as an investor, that guidance increase effectively turns operational levers into active catalysts. Progress on AI driven cost management, Carelon’s complex care programs and exits from weaker Medicaid contracts now needs to show up cleanly in reported EPS. Any stumble on those fronts would not just be a headline issue; it would directly test the credibility of that upgraded outlook.
Elevance Health's analyst narrative points to revenues of US$211.4b and earnings of US$7.6b by 2029, built on an assumed 1.5% yearly top line growth rate and an earnings increase of about US$2.5b from earnings of US$5.1b today.
Uncover why Elevance Health's fair value indicates an 8% potential upside to its current price before shifting sentiment closes that discount.
Exploring Other Perspectives
The lowest analysts focus on Medicaid pressure as the key risk for Elevance Health. Their pre news forecasts penciled in roughly flat revenue near US$206.6b by 2029 and earnings of about US$7.1b. That is a more cautious story than consensus. This fresh EPS guidance and the Carelon leadership change may eventually reshape those expectations.
Explore 3 other Elevance Health fair value estimates, including one that suggests it could be worth just $474.57.
Form Your Own Verdict
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your Elevance Health research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Elevance Health. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Elevance Health's overall financial health at a glance.
Looking for more Elevance Health style investment ideas?
Once you have a view on Elevance Health, it can help to widen the lens and compare it with other businesses that match your preferred mix of quality, valuation and risk using the Simply Wall St Screener.
- If you want a margin of safety as you build positions, scan a curated set of 27 high quality undervalued stocks that combine solid fundamentals with prices that may sit below their estimated worth.
- For investors who care about stability first, focus on a 30 resilient stocks with low risk scores that scores well on earnings consistency, balance sheet strength and business predictability.
- If you are hunting for future leaders before they hit the headlines, target a 21 high quality undiscovered gems that pair strong financial profiles with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com