


Earnings Beat Might Change The Case For Investing In Lindsay Stock (LNN)
- Lindsay Corporation reported fiscal Q4 2026 sales of US$161.57 million and net income of US$11.26 million, alongside a US$0.38 quarterly dividend and confirmation that US$50 million of share repurchases have been completed under its existing authorization.
- The announced global restructuring program targeting US$8 million in annualized savings and the planned Setorial Irrigação acquisition in Brazil indicate a tighter cost base and a broader irrigation footprint across key international markets.
- We will now look at how Lindsay's investment narrative could be influenced by the restructuring plan that targets ongoing cost savings.
Scan investor controlled capital return stories like Lindsay alongside a curated 5 dividend fortresses that pairs regular payouts with balance sheets built to handle tougher farm and infrastructure cycles.
Lindsay Investment Narrative Recap
Lindsay still asks you to believe in a cyclical irrigation and infrastructure story where weaker North American farm spending is offset by international projects, technology offerings and road safety products. The recent quarter showed higher Q4 sales and earnings per share, but full year revenue and net income were lower. As a result, the key short term catalyst remains execution on current projects and the global restructuring plan.
The biggest near term risk is that soft grower economics and lumpy infrastructure work keep volumes too low for Project Fortify and the new cost base to pay off meaningfully. The latest updates do not remove that risk, although announced savings and disciplined capital returns could help cushion a prolonged slow patch.
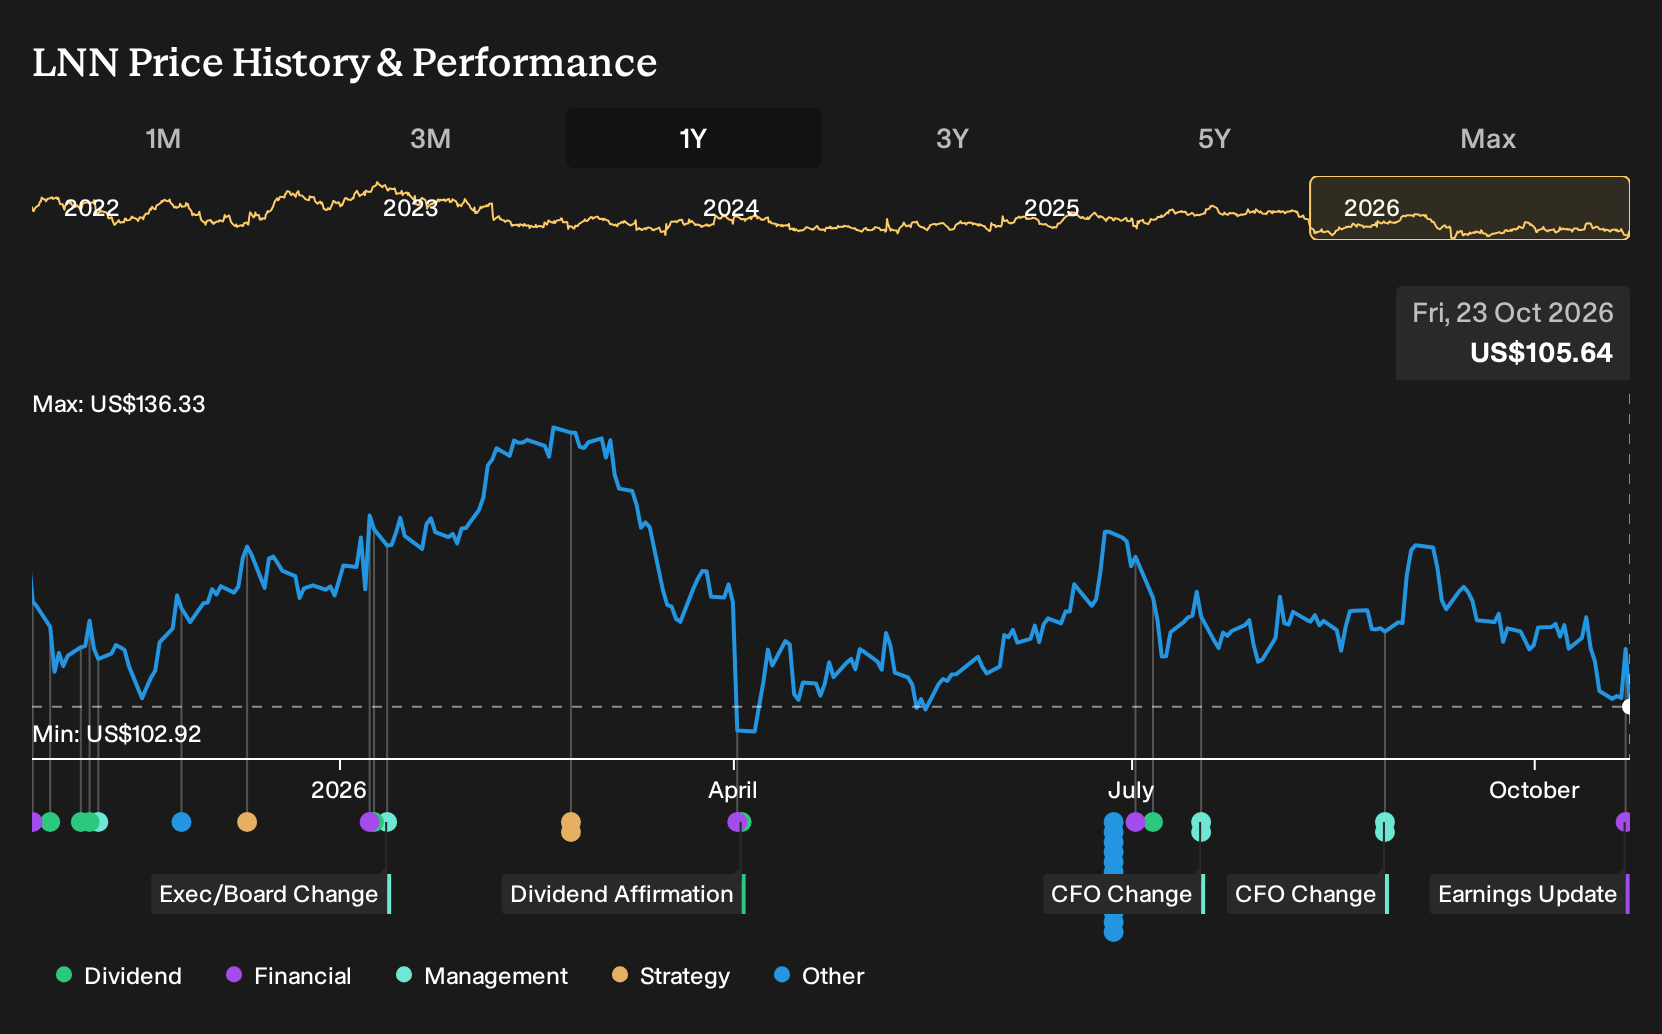
The fresh US$0.38 quarterly dividend affirmation is the announcement that ties closest to this story. Management paired ongoing cash returns with a year in which sales and earnings from continuing operations fell on a full year basis. That combination makes the balance between reinvestment needs and shareholder payouts an important watchpoint.
For you as a holder or potential holder, the maintained dividend sits alongside completed US$50 million of buybacks, Project Fortify spending and restructuring charges. The key question is whether Lindsay can keep funding these commitments from future cash generation if North American irrigation remains weak and large infrastructure projects do not repeat at the same scale.
How The Lindsay Earnings Story Is Framed By Consensus
Lindsay's narrative projects US$702.0 million in revenue and US$74.9 million in earnings by 2029, based on analyst models that build in 3.8% yearly top line growth and higher profit margins. That path assumes an earnings increase of about US$19.7 million from the US$55.2 million the business earns today.
Uncover how Lindsay's fair value indicates a 16% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between US$123 and about US$138, which gives you a tight band but still a meaningful gap between the lowest and highest views. Consider that alongside Lindsay's restructuring plans, its MENA irrigation project and the upcoming Brazil acquisition, and you can see why opinions diverge. Use these differing perspectives as a prompt to explore several alternative viewpoints before deciding how the dividend and buyback record fits your own expectations.
Explore another Lindsay fair value estimate, including one that suggests up to 30% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Lindsay research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Lindsay. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lindsay's overall financial health at a glance.
Looking for more Lindsay sized investment ideas?
If the Lindsay story has you thinking about portfolio balance, cast the net wider and line up a few other candidates that match the kind of risk and income profile you want.
- For investors who want dependable balance sheets backing their equity exposure, check out a list of solid balance sheet and fundamentals (25 results) that can handle rougher patches without stretching finances.
- If resilience matters more than excitement, filter for companies with steadier risk profiles using a 30 resilient stocks with low risk scores that aims to limit unwanted surprises.
- When future upside is your priority, scan for high quality businesses that are not widely followed yet through a 21 high quality undiscovered gems that highlights under-the-radar fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com