


Why Coeur Mining Fell Even As Profit Rose
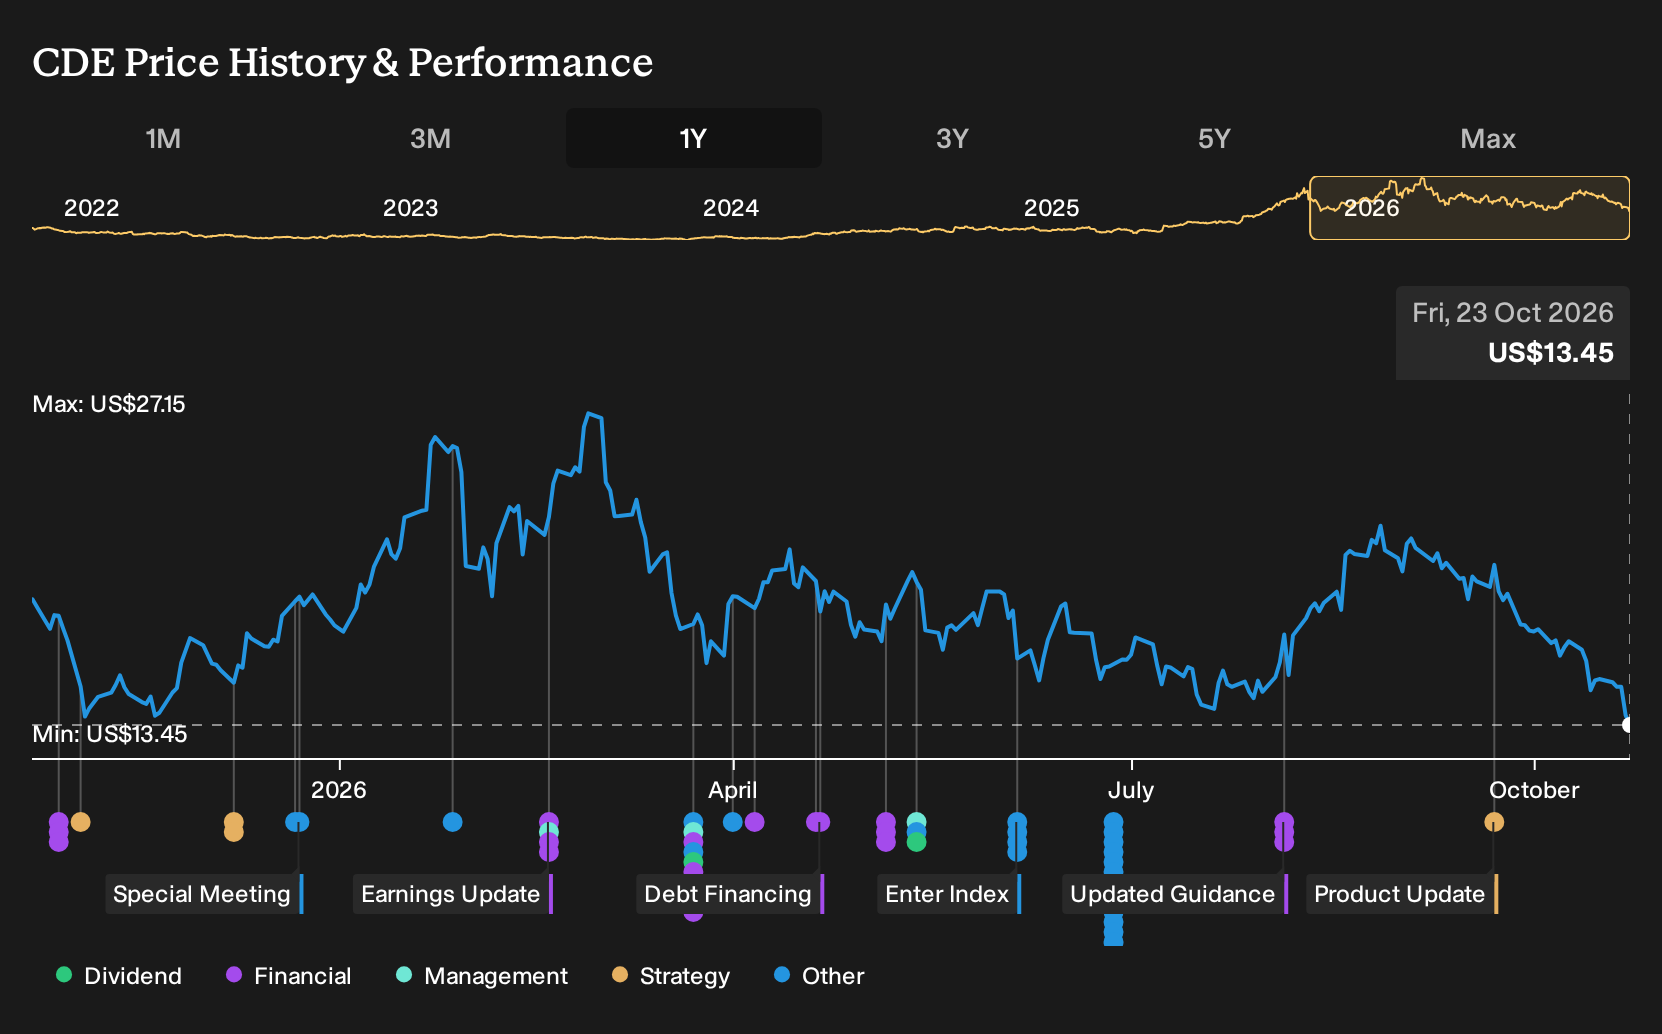
If you had decided on 23 October 2025 to skip Coeur Mining because the story felt too dependent on bold commodity assumptions, the numbers that followed might look like a narrow escape. For Coeur Mining shareholders, the loss over the past year was 27.8%, including dividends. With that outcome now on the table, which of the published expectations or embedded assumptions available at the time most deserved a harder second look?
The move put Coeur Mining in the middle of this trade. Scan 35 elite gold producer stocks for other companies exposed to it.
The Two Coeur Mining Stories Investors Had To Weigh
The shares cost US$18.98 at the start of the period, and Coeur Mining investors faced two very different stories that both sounded plausible.
The bullish script pointed to a fair value of US$21.6, a rough estimate of what the stock might be worth if its gold price reached US$4,000 and its silver price reached US$100. That narrative rested on aggressive assumptions, including 51.2% revenue growth and a 9.5% profit margin over five years.
The more cautious view argued for a fair value of US$13.64 and relied on steadier 14.3% revenue growth and a higher 33.2% margin assumption. That scenario also highlighted the risk that regulatory, operational, and financial pressures could limit profitability.
What The Results Changed For The Coeur Mining Story
The biggest development was sheer scale. Coeur Mining reported Q2 2026 revenue of US$1.09b and net income of US$121.9m, up from US$480.7m and US$70.7m in Q2 2025, helped by the New Gold acquisition and higher output. Net margin slipped from 14.7% to 11.2%. The period cut both ways for the original bullish and cautious scripts.
The contested assumption here was not just volume; it was profitability. When you assess another miner, compare the forecast margin in the pitch to the margin actually reported over time, then decide how much of the story to credit.
What Coeur Mining’s Lower Price Asks You To Believe
Coeur Mining now trades at US$13.45, with this Narrative’s Fair Value sitting above that level. The Narrative centers on stronger silver and gold demand combining with smoother mine integration and cost control to support higher revenue and wider margins.
For the recent fall to look like an opening rather than a warning, a buyer today would need confidence that Rochester and Las Chispas ramp issues are temporary and that production, costs, and mine life ultimately track the Narrative’s playbook.
"Key Takeaways: Rising industrial and investor demand for silver and gold, along with operational improvements, position the company for strong revenue growth and margin expansion. Exploration and asset integration efforts are set to extend mine life and underpin stable long-term production."
One Narrative disagrees with today's price. → See where this Narrative says Coeur Mining should trade
Looking Beyond Coeur Mining’s Pits
If Coeur Mining has you focused on producing ounces, take one small step back. Before ore ever reaches a mill, it begins as a drilled idea.
Exploration outfits chase that earlier stage. They handle mapping, geophysics, and core work that can turn rock into a defined mineral resource.
One such explorer is advancing a large gold copper system, updating an older resource model with fresh drilling and revised metal assumptions.
The next technical report will not build a mine on its own. It could still reshape how potential future operators judge what this ground is worth.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 194% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com