


Ithaca Energy (LSE:ITH) Gains On Iran Tensions As Valuation Questions Persist
Geopolitics and Ithaca Energy: Why the Stock Just Moved
Ithaca Energy (LSE:ITH) has been in focus after reports of potential US and Israeli military action on Iran pushed oil prices higher, lifting energy shares and helping the stock outperform a weaker FTSE 100.
The latest move fits into a strong run for Ithaca Energy, with an 85.22% year-to-date share price return and a 59.53% total shareholder return over the past year. A 181.19% three-year total shareholder return points to momentum that has been building for some time as investors react to both shifting oil prices and UK project approvals such as Rosebank, as well as broader regulatory signals like the Jackdaw green light.
Scan other energy names moving on similar headlines by reviewing our hand picked 35 elite gold producer stocks alongside Ithaca Energy.
Ithaca Energy has enjoyed a powerful run and a sharp geopolitical bump, yet the business itself still lives and dies by North Sea cash flows. How does that mix line up against the current valuation?
Most Popular Narrative: 14% Undervalued
Ithaca Energy last closed at £3.01, while the most followed narrative pins fair value closer to £3.50. That gap reflects a story built around long lived projects and basin diversification rather than just short term oil price spikes.
The acquisition of Terra Nova and White Rose in Eastern Canada introduces Ithaca Energy to a new operated hub with 103 mmboe of 2P reserves and a 17 year reserve to production ratio. This can support an additional stream of oil volumes that is separate from UK basin trends and could support group revenue and EBITDAX resilience over a longer horizon.
See why 6 investors see Ithaca Energy as 14% undervalued.
Result: Fair Value of £3.50 (UNDERVALUED)
Still, the bullish Ithaca Energy narrative leans heavily on UK tax clarity and Canadian hub execution, and either setback could quickly challenge that 14% undervaluation story.
Find out about the key risks to this Ithaca Energy narrative.
Another View: Ithaca Energy On Earnings Multiples
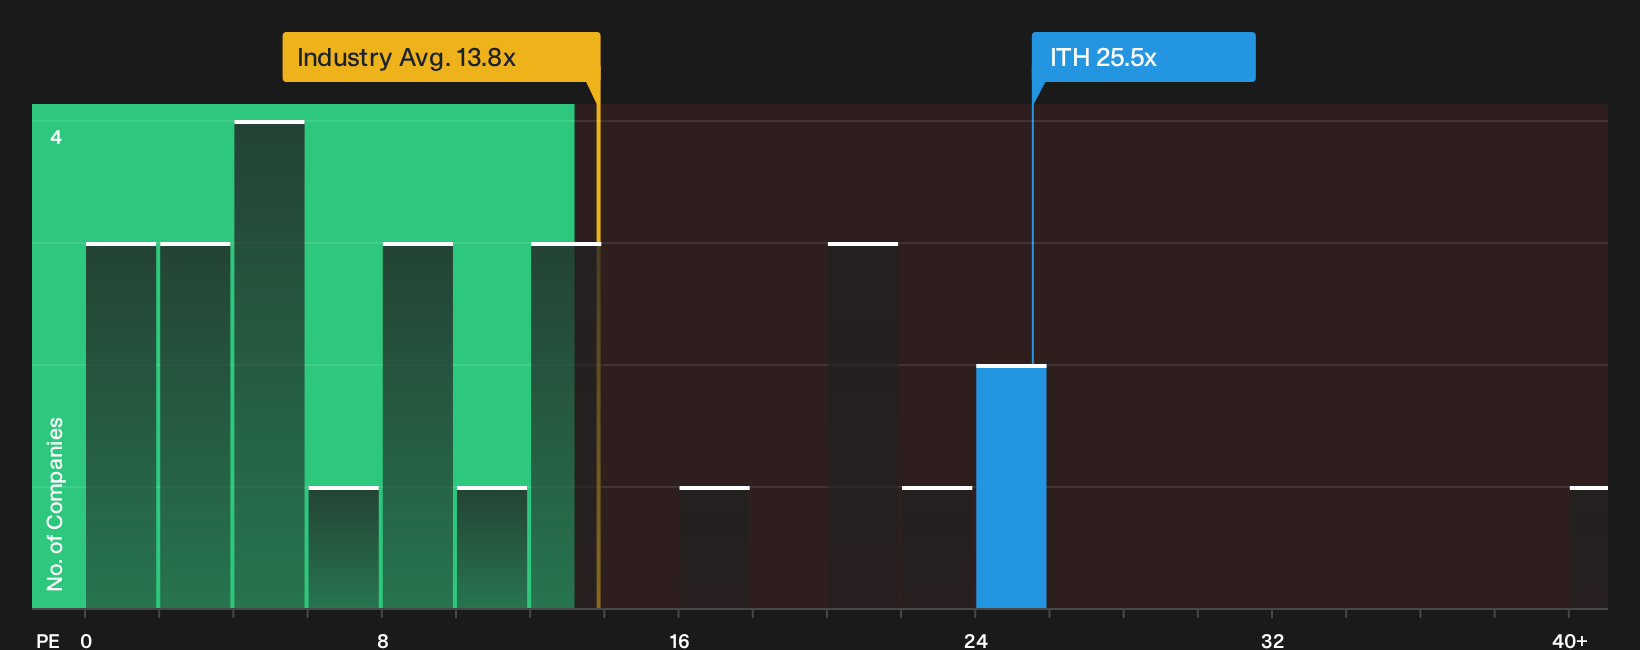
The story changes once you focus on Ithaca Energy’s earnings multiple instead of its cash flows. The shares trade on a P/E of 25.5x, while peers in the European Oil and Gas group sit closer to 13.8x and direct comparables average 17.1x. The fair ratio is 17.9x, which is the level the market could move towards. That gap points to valuation risk if sentiment cools or earnings forecasts slip even slightly.
See what the numbers say about this price in more depth in our valuation breakdown, starting with See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of enthusiasm and concern around Ithaca Energy feels familiar, consider reviewing the situation promptly and weighing the evidence yourself so the market does not decide for you. Start by reviewing the 3 key rewards and 2 important warning signs.
Looking for more Ithaca Energy sized ideas?
If Ithaca Energy has sharpened your focus on opportunities, do not stop here. Broaden your watchlist now so you are not reacting after the move.
- Target resilient compounding by scanning companies with healthy income streams and strong payout potential through our 5 dividend fortresses.
- Hunt for mispriced opportunities by filtering for quality businesses trading below estimated value using the 8 high quality undervalued stocks.
- Prioritise sleep at night holdings by focusing on companies with stronger finances and sturdier balance sheets through the list of solid balance sheet and fundamentals (9 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com