


Vail Resorts (MTN) Faces An Activist Test As Fair Value Sits Close By
Vail Resorts (MTN) is back in the spotlight after activist investor Oasis Management launched a proxy fight, pushing to replace four board members and challenge the group on pricing, resort sales and overall direction.
Recent trading in Vail Resorts reflects that proxy fight backdrop. The share price is at US$146.57 after a 4.66% 30 day share price return and a 9.41% year to date share price return. However, the 5 year total shareholder return is still down 46.70%, which signals that longer term momentum has been weak even as shorter term price action has improved.
Spot potential turnaround stories like Vail Resorts by scanning our hand picked 21 high quality undiscovered gems, which the broader market may still be overlooking.After a sharp short term rebound but a much weaker five year record, Vail Resorts now poses a practical decision. Investors can either lean into the recent move or wait for a clearer valuation cushion before getting involved.
Most Popular Narrative: 1% Undervalued
On Simply Wall St's most followed narrative, Vail Resorts is tagged with a fair value of $148.36 against the latest close at $146.57, which frames a small discount that matters more when tied to the underlying earnings story than the raw $1.79 gap.
Vail Resorts expects its Resource Efficiency Transformation Plan to move beyond the original goal, with $106 million of annualized savings targeted by the end of fiscal 2026 and a further $30 million of technology efficiencies identified through fiscal 2028, which points to ongoing support for net margins and earnings.
See why 12 investors see Vail Resorts as 1% undervalued.
Result: Fair Value of $148.36 (UNDERVALUED)
Still, the narrative around Vail Resorts can unravel quickly if weak visitation persists or if activist pressure drives asset sales and capital decisions that disappoint investors.
Find out about the key risks to this Vail Resorts narrative.
Another View: Vail Resorts Looks Expensive On Earnings
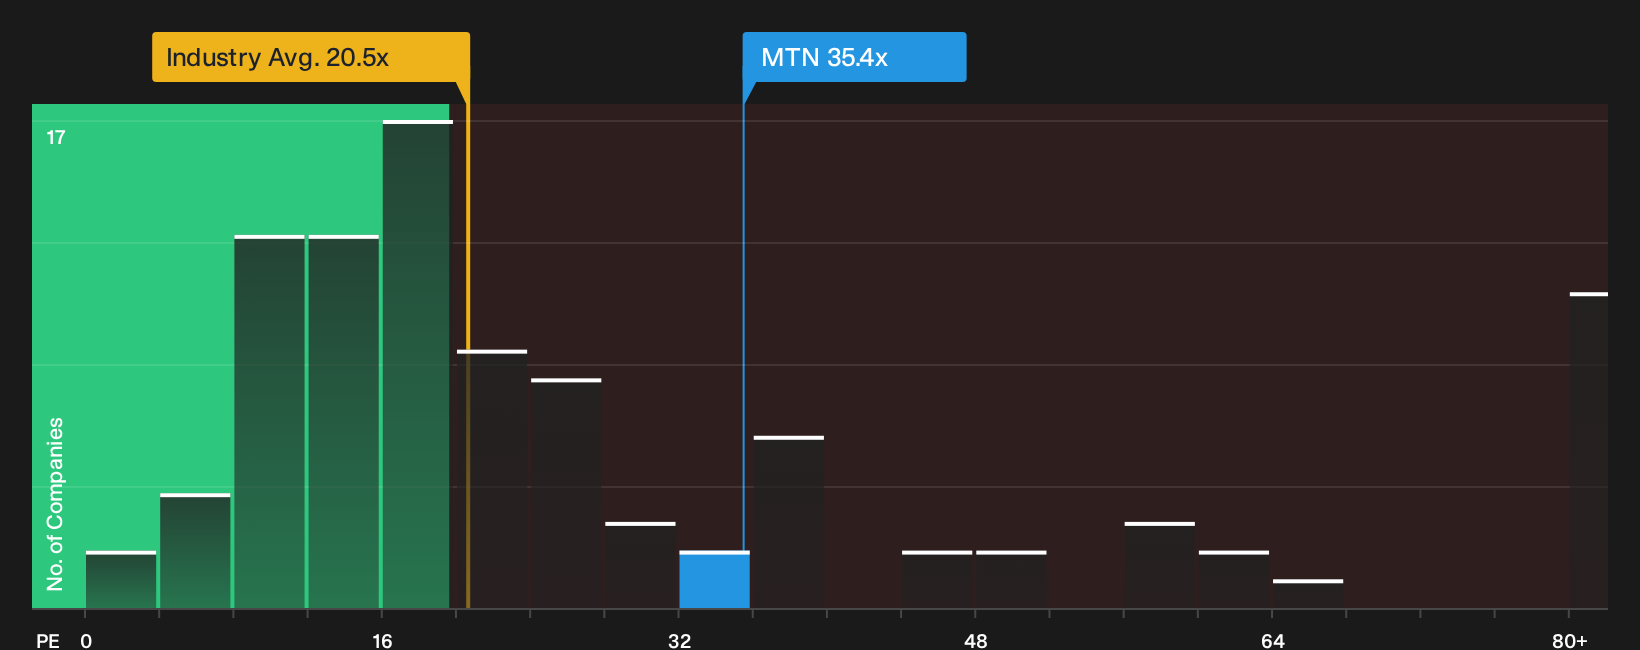
The fair value narrative around Vail Resorts leans on future cash flows and cost savings. Flip the lens to current earnings and the picture looks tougher. The stock trades on a P/E of 35.4x, compared with a peer average of 21.3x and a fair ratio of 23x.
That gap means investors today are paying a much richer multiple than both the industry and the level our fair ratio suggests the market could move toward. This raises the risk that any stumble in execution or demand is punished more harshly. Are you comfortable paying that kind of premium for this story?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views are already baked into Vail Resorts, with clear concerns and some bright spots in the data. Act quickly, review the numbers yourself, and weigh up the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Vail Resorts?
If Vail Resorts has your attention, do not stop there. Broaden your watchlist with fresh ideas that target different styles of risk and return.
- Target potential mispricing by scanning a curated set of quality companies trading at compelling valuations through the 27 high quality undervalued stocks.
- Prioritise resilience and downside protection by focusing on a 30 resilient stocks with low risk scores that screens for businesses with sturdier risk profiles.
- Hunt for future leaders before the market fully catches on by reviewing a 21 high quality undiscovered gems built around strong fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com