


AAK (OM:AAK) Q3 Results Highlight Profit Per Kilo Pressure
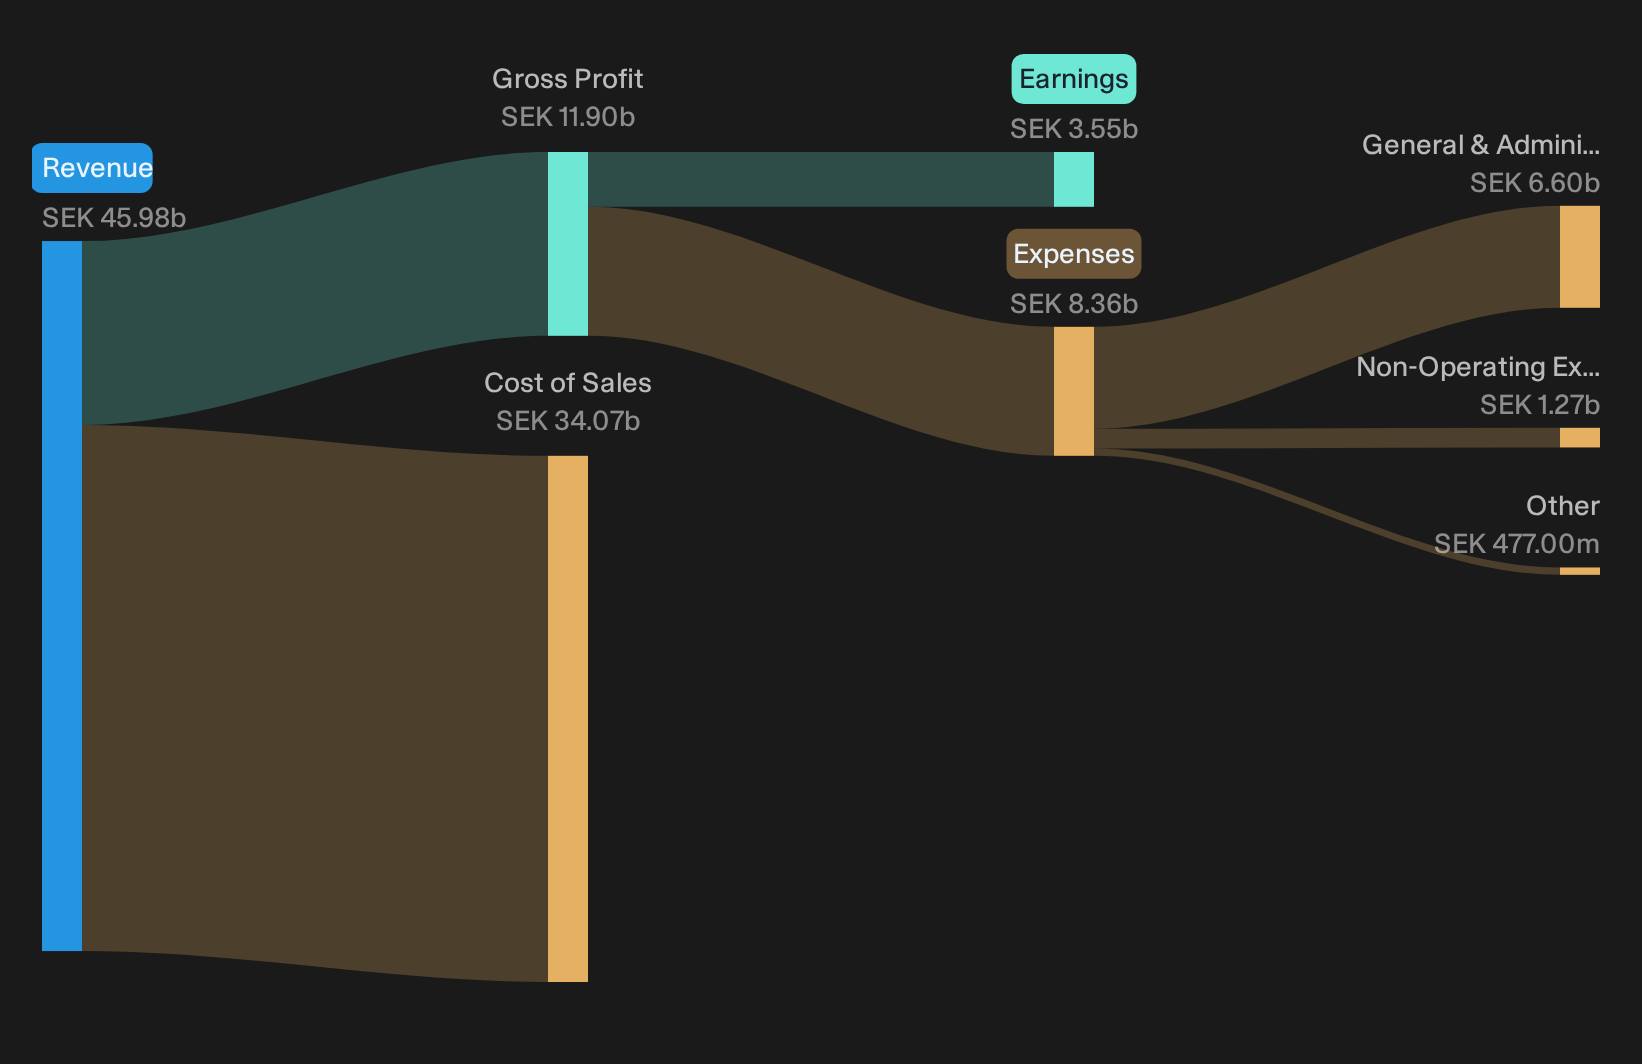
AAK AB came into this Q3 2026 report with a solid long run profit story and a stock that has cooled recently, with the share price at SEK182.6 after a weak week and softer 3 month stretch. The company then reported another quarter of healthy earnings power, with operating profit at SEK 1,154m and free cash flow close to SEK 1.1b, supported by a net debt to EBITDA ratio of 0.56.
The market focused on pressure in operating profit per kilo. The larger context is a cash rich, low leverage specialty fats producer that is still generating significant cash.
Like the cash generation at AAK AB but uneasy about profit per kilo pressure and a cooling share price? Scan our curated list of resilient, cash generative stocks with solid balance sheets in the list of solid balance sheet and fundamentals stocks (204 results).
Q3 2026 Earnings Summary
- Total Revenue (Q3 2026 vs. Q3 2025): SEK 11,910m vs. SEK 11,498m (up 3.6%)
- Net Income, Excl. Extra Items (Q3 2026 vs. Q3 2025): SEK 837m vs. SEK 909m (down 7.9%)
- Basic EPS (Q3 2026 vs. Q3 2025): SEK 3.22 vs. SEK 3.50 (down 7.9%)
- Operating Profit (Q3 2026 vs. Q3 2025): SEK 1,154m vs. SEK 1,255m (down 8.0%)
Earnings tell part of the story, but investors who care about what a business is worth usually focus on the cash coming in and out of the bank account. Look at AAK AB (publ.)'s cash flows on their own and the stock could be a hefty 48% undervalued.
Evaluating AAK’s Profit‑Per‑Kilo Ambition
The bullish story around AAK hinges on profit density, not just volume, so the long term goal needs to be checked against current execution.
"Bullish analysts expect AAK AB (publ.) to continue shifting its mix toward higher-value specialty fats and cocoa butter equivalents while pushing group-wide efficiency programs, with the aim that operating profit per kilo moves closer to the long-term SEK 3+ ambition."
Q3 moves the firm in the opposite direction. Group operating profit per kilo fell 8% to SEK 2.27, with Food Ingredients down about 9% and Chocolate & Confectionery Fats down 6%. Efficiency efforts are progressing, shown by Fit to Win reaching a SEK 250m run rate and strong cash generation. However, the SEK 3 per kilo ambition remains a future target rather than an achieved waypoint.
The price and this Narrative do not agree. → Uncover what this Narrative says AAK AB (publ.) is actually worth.
AAK Bear Case: Volumes Hold, Profit Density Slips
The bearish view argues that AAK could stumble if softer demand and operational issues collide with a heavy project slate.
"Bearish analysts expect AAK AB (publ.) to face continued pressure on revenue growth and margins if softer volumes in areas like Dairy and Foodservice persist and production setbacks reappear."
Q3 results partly address this. Group volumes were flat and Chocolate & Confectionery Fats increased by 1%, so the feared volume drop has not materialized. The impact is elsewhere. Operating profit per kilo fell 8% to SEK 2.27, Food Ingredients profitability weakened, and Fit to Win is still short of the SEK 300m target. Execution risk appears more in profit density and the timing of savings than in demand erosion so far.
Hunt For Mispriced Cash Engines
AAK AB (publ.) just reminded investors that steady cash generation can coexist with margin questions and a cooling share price. The real opportunity sits in spotting stocks that could be undervalued before sentiment catches up.
- Company 1 - 26% below our estimate - pivots from low margin hull construction toward underwater technology, digital control platforms and recurring defense services.
- Company 2 - 30% below our estimate - supplies photonic equipment enabling chip and medical manufacturers to expand capacity for precise, data intensive uses.
- Company 3 - 33% below our estimate - manages fee based investment vehicles directing infrastructure and renewable demand into long horizon real assets and private equity.
Those are three of them. See the full list of 192 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com