


Bilia (OM:BILI A) Q3 Earnings Lean On Record Service Strength
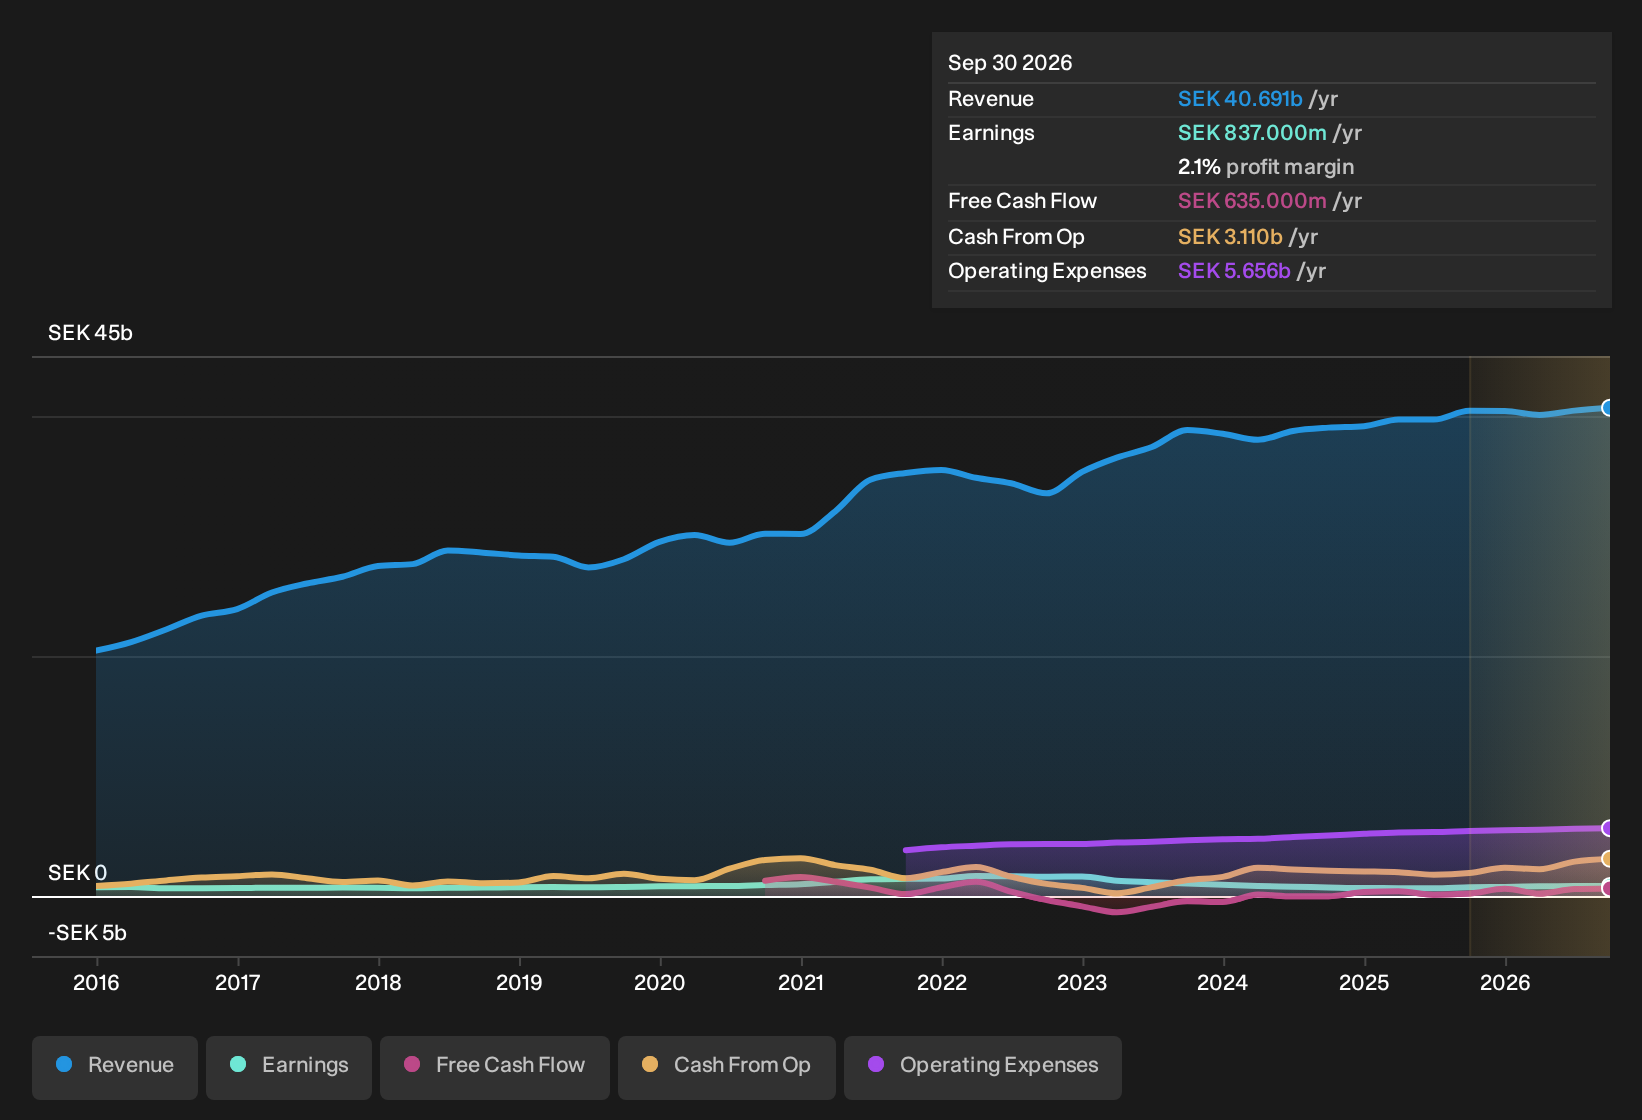
Bilia stock closed at SEK136.40 on Friday, capping a run in which the share price slipped roughly 6% over the past week as investors braced for fresh numbers. The Q3 2026 release told a different story. Operating profit reached SEK380m on a 3.8% margin and earnings per share came in at SEK2.02, powered by a service division that delivered its best third quarter on record. Short term trading focused on recent price weakness. The longer view now turns to whether this service profit engine can keep carrying the broader auto retail business.
Impressed by Bilia’s service profit engine but wary that a single division is carrying so much of the story right now? Use it as a benchmark and scan our list of solid balance sheet and fundamentals stocks (204 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): SEK 9,961m vs SEK 9,717m (up about 2.5%)
- Net Income (Excl. Extra Items, Q3 2026 vs Q3 2025): SEK 185m vs SEK 191m (down about 3.1%)
- Basic EPS (Q3 2026 vs Q3 2025): SEK 2.02 vs SEK 2.06 (down about 2.3%)
- Operating Margin (Q3 2026 vs Q3 2025): 3.8% vs 3.3% (improvement of about 0.5 percentage points)
Service delivered Bilia’s best-ever Q3 and 73% of profits. Ask Charlie what makes Bilia’s service margins so strong.
Bilia service thesis meets key profit milestones
The bullish story rests on Service and cost savings turning into a durable earnings engine for Bilia.
"Bilia is extending its focus on the older car fleet and fully electric models in workshops, with Service already contributing 70% to 79% of group profit and management now targeting a 14% Service margin. This points to Service mix and pricing as a continuing support for earnings and net margins."
Q3 backs that up. Service delivered SEK 293m, about 73% of operating profit, with a 12% margin and Sweden already at 14.2%. Group margin of 3.8% and SEK 479m operating cash flow show the earnings mix and cash engine moving in the direction the thesis wants.
Bilia risk thesis flags used car and execution pressure
The bear side focuses on whether capital allocation discipline and used car risk undermine that same earnings story.
"The main thing that has to go right is that Bilia continues to convert its strong cash generation and low leverage into disciplined capital allocation, including delivering the planned efficiency savings while managing used car margin pressure and car market volatility in the Nordics."
Q3 results show both progress and strain. Net debt to EBITDA sits at 1.2x and credit lines increased to SEK 3.1b, so balance sheet flexibility holds. Used cars tell a different story. Segment profit slipped to SEK 55m from SEK 68m, with margin pressure in Norway confirming that part of the risk is already visible in earnings.
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all.
Hunt For Mispriced Earnings Power
Bilia recently highlighted how a strong service engine can shift where earnings are generated. The real opportunity is assessing stocks that could be undervalued before the market revisits their earnings power.
- Company 1 - 49% below our estimate - wins long dated public mega projects that depend on disciplined bidding and strong contract protections.
- Company 2 - 23% below our estimate - leans into higher value packaged foods and marketing to steer spending toward branded staples and drinks.
- Company 3 - 24% below our estimate - supplies low voltage equipment and services to contractors focused on data centers and electrification projects.
Those are three of them. See the full list of 192 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com